Snack food company Utz Brands (NYSE: UTZ) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 2.3% year on year to $369.2 million. Its non-GAAP profit of $0.10 per share was 55.8% below analysts’ consensus estimates.
For more on Utz, read our full research report for free.
Utz (UTZ) Q3 2026 highlights:
- Revenue $369.2 million vs S&P consensus estimates of $384.4 million (2.3% year-on-year decline, 4% miss)
- Adjusted EPS $0.10 vs S&P consensus estimates of $0.23 (55.8% miss)
- Adjusted EBITDA $62.9 million vs analysts’ consensus estimates of $65.01 million (17% margin, 3.2% miss)
- Operating margin -5.9%, down from 0.9% in the same quarter last year
- Free cash flow -$21 million, down from $27.7 million in the same quarter last year
- Organic revenue fell 2.3% year on year (miss)
- Sales volumes fell 5.2% year on year (4.5% in the same quarter last year)
- Market capitalization $1.26 billion
“Our results were impacted by industry-wide headwinds that intensified throughout the quarter, including abrupt, significant inflation and a modestly weaker consumer,” said Howard Friedman, Chief Executive Officer of Utz. “I have been proud to serve as CEO of Utz for nearly four years and remain focused on supporting Utz’s transition to a private company and John Lindeman’s transition to CEO in the coming weeks following the expected closing of the transaction.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can post a good quarter or two, but the best consistently grow over the long term.
With $1.44 billion in revenue over the past 12 months, Utz is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
Utz struggled to increase demand as its trailing 12-month revenue of $1.44 billion was close to its revenue three years ago. This is mainly because it failed to grow its volumes.
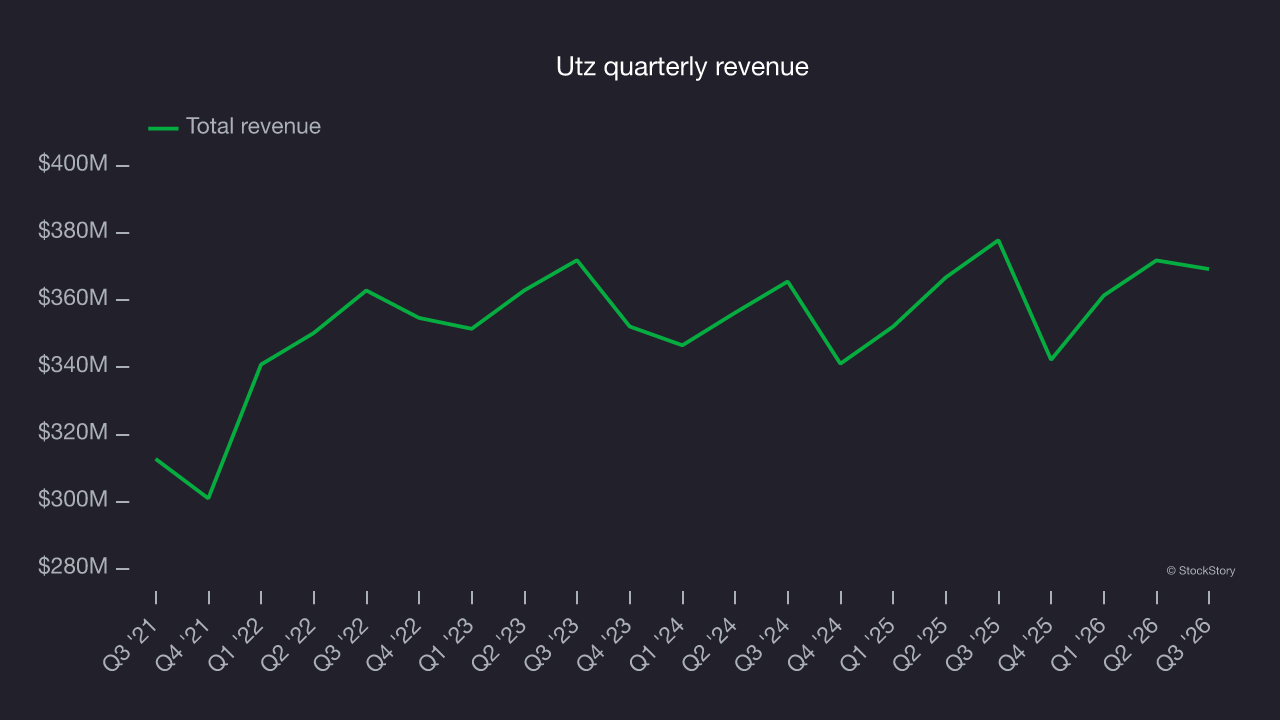
This quarter, Utz missed Wall Street’s consensus estimates and reported an uninspiring 2.3% year-on-year revenue decline, generating $369.2 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 3.1% over the next 12 months, according to S&P. Although this projection implies its newer products will fuel better top-line performance, it is still below average for the sector.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is central to a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
To analyze whether Utz generated its growth from changes in price or volume, we can compare its volume growth to its organic revenue growth, which excludes non-fundamental impacts on company financials like mergers and currency fluctuations.
Over the last two years, Utz’s quarterly sales volumes have, on average, stayed about the same. This stability is normal as the quantity demanded for consumer staples products typically doesn’t see much volatility. The company’s flat volumes also indicate its average organic revenue growth of 1.4% was generated from price increases.
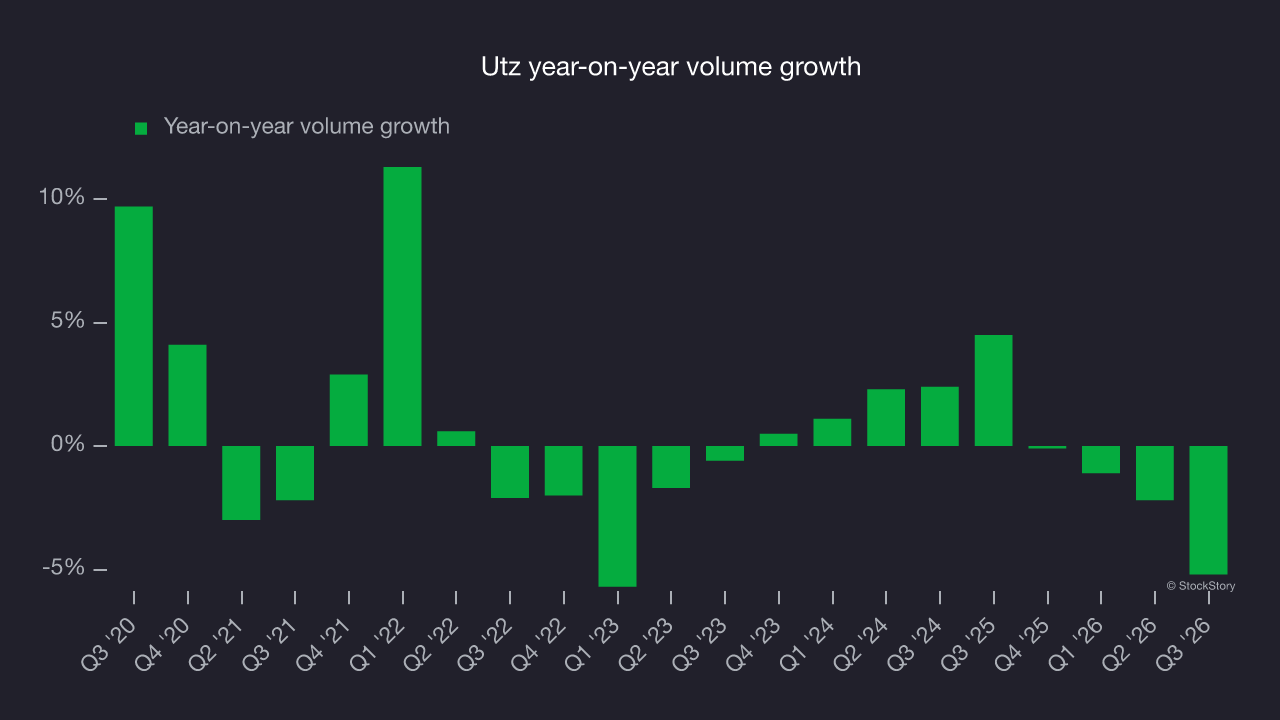
In Utz’s Q3 2026, sales volumes dropped 5.2% year on year. This result represents a further deceleration from its historical levels, showing the business is struggling to sell its products.
Key takeaways from Utz’s Q3 results
Utz’s Q3 results offered few positives: Organic revenue missed expectations, and gross margin also fell short of Wall Street’s consensus estimates. It was a quarter that could have been better. Shares remained flat at $14.26 immediately after the release.
For investors considering Utz at its current price, the latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Utz, read the full research report here (it’s free).