Household products company WD-40 (NASDAQ: WDFC) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q4 2026), with sales up 8.1% year on year to $176.8 million. The company expects the full year’s revenue to be around $725 million, close to analysts’ estimates. Its GAAP profit of $1.06 per share was 7.8% below analysts’ consensus estimates.
Is now the time to buy WD-40? Find out by accessing our full research report, it’s free.
WD-40 (WDFC) Q3 CY2026 highlights:
- Revenue: $176.8 million vs analyst estimates of $172.1 million (8.1% year-on-year growth, 2.7% beat)
- EPS (GAAP): $1.06 vs analyst expectations of $1.15 (7.8% miss)
- EPS (GAAP) guidance for the upcoming financial year 2027 is $6.55 at the midpoint, beating analyst estimates by 1.7%
- Operating Margin: 10.8%, down from 17.1% in the same quarter last year
- Free Cash Flow Margin: 26.4%, up from 17.5% in the same quarter last year
- Market Capitalization: $2.70 billion
Company overview
Short for “Water Displacement perfected on the 40th try”, WD-40 (NASDAQ: WDFC) is a renowned American consumer goods company known for its iconic and versatile spray, WD-40 Multi-Use Product.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $688 million in revenue over the past 12 months, WD-40 is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
As you can see below, WD-40’s 8.6% annualized revenue growth over the last three years was decent. This shows its offerings generated slightly more demand than the average consumer staples company, a helpful starting point for our analysis.
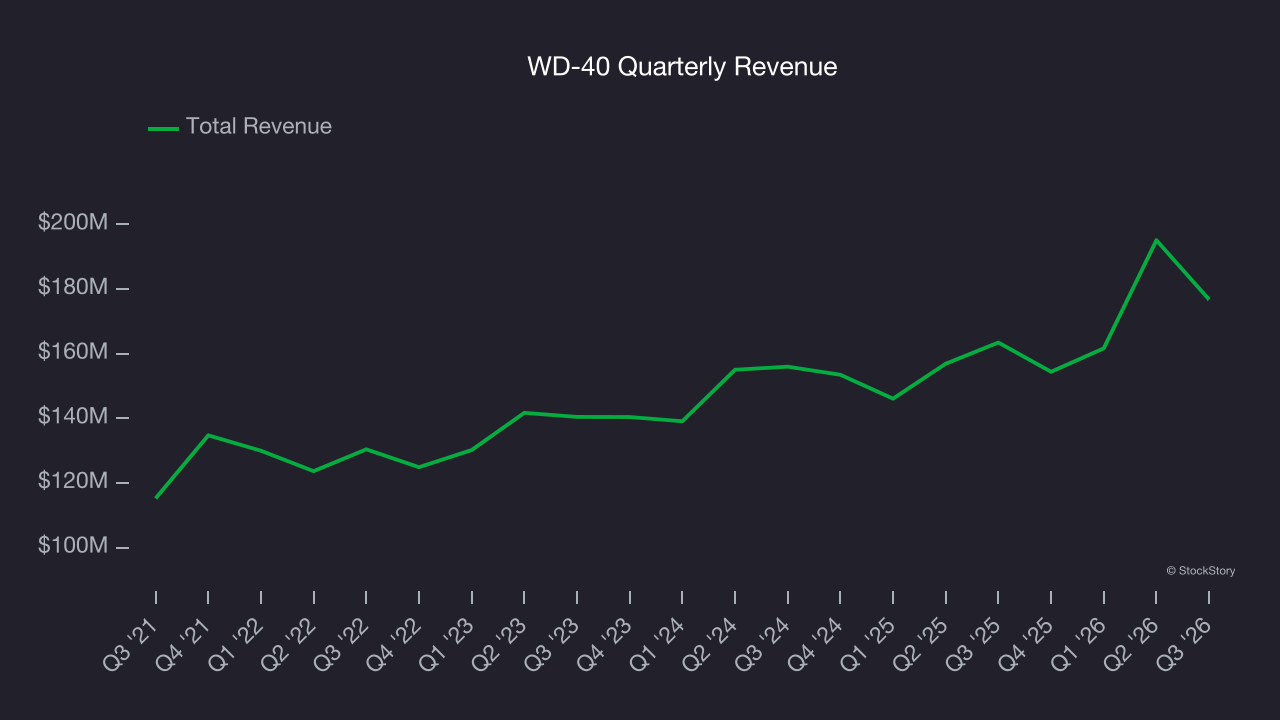
This quarter, WD-40 reported year-on-year revenue growth of 8.1%, and its $176.8 million of revenue exceeded Wall Street’s estimates by 2.7%.
Looking ahead, sell-side analysts expect revenue to grow 5.4% over the next 12 months, a deceleration versus the last three years. Despite the slowdown, this projection is above average for the sector and indicates the market sees some success for its newer products.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Cash is king
Although earnings are undoubtedly valuable for assessing company performance, we believe cash is king because you can’t use accounting profits to pay the bills.
WD-40 has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 13.8% over the last two years.
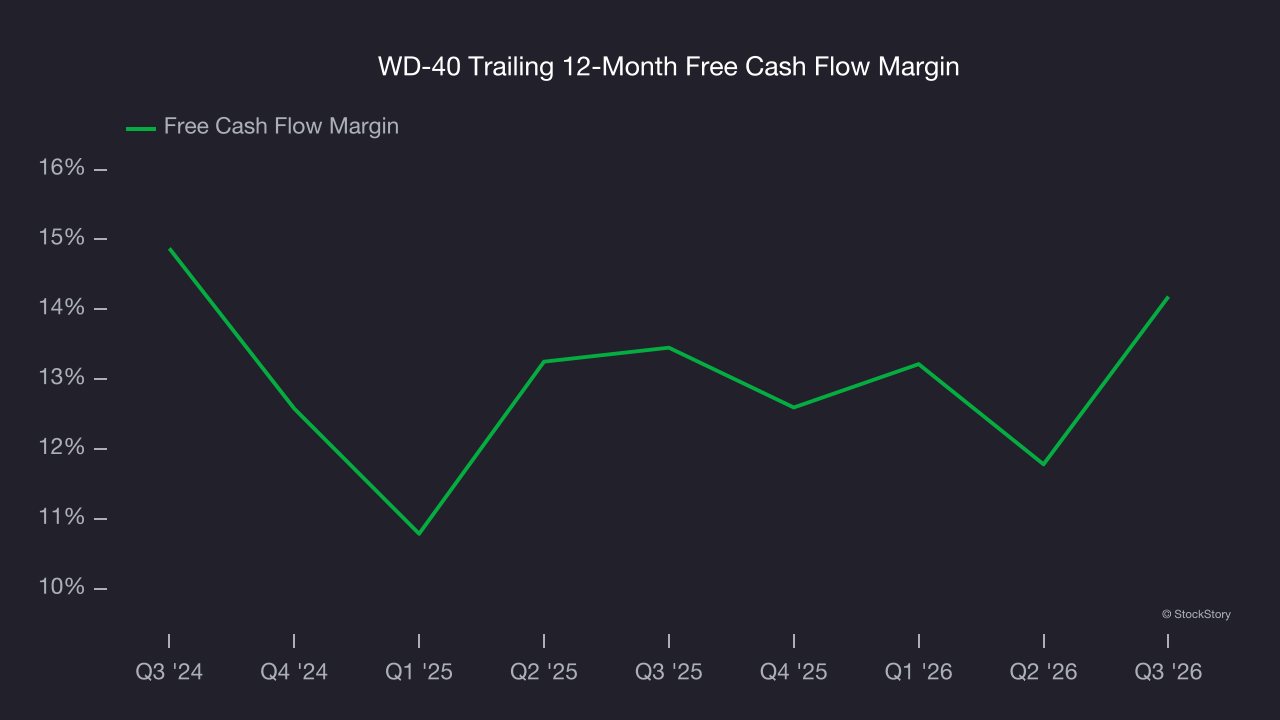
WD-40’s free cash flow clocked in at $46.67 million in Q3, equivalent to a 26.4% margin. This result was good as its margin was 8.9 percentage points higher than in the same quarter last year. Its cash profitability was also above its two-year level, and we hope the company can build on this trend.
Key takeaways from WD-40’s Q3 results
It was encouraging to see WD-40 beat analysts’ revenue expectations this quarter. We were also glad its full-year EPS guidance exceeded Wall Street’s estimates. On the other hand, its EPS missed. Overall, this quarter could have been better. The stock remained flat at $192.92 immediately following the results.
Is WD-40 an attractive investment opportunity at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).