What a brutal six months it’s been for Opendoor. The stock has dropped 63.1% and now trades at a new 52-week low of $1.98, rattling many shareholders. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Opendoor, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Opendoor Will Underperform?
Even with the cheaper entry price, we’re cautious about Opendoor. Here are three reasons why there are better opportunities than OPEN, plus one stock we’d rather own.
1. Decline in Homes Sold Points to Weak Demand
Revenue growth can be broken down into changes in price and volume (for companies like Opendoor, our preferred volume metric is homes sold). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Opendoor’s homes sold came in at 2,339 in the latest quarter, and over the last two years, averaged 17% year-on-year declines. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Opendoor might have to lower prices or invest in product improvements to grow, factors that can hinder near-term profitability. 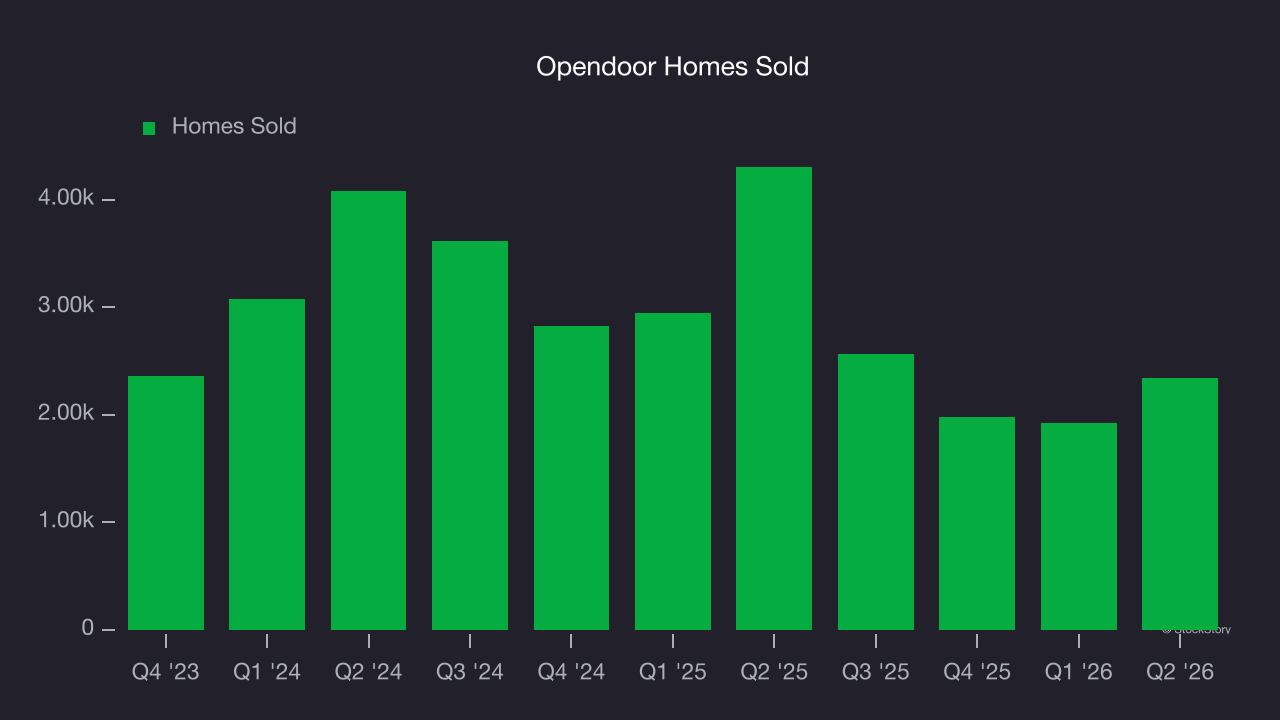
2. Breakeven Free Cash Flow Limits Reinvestment Potential
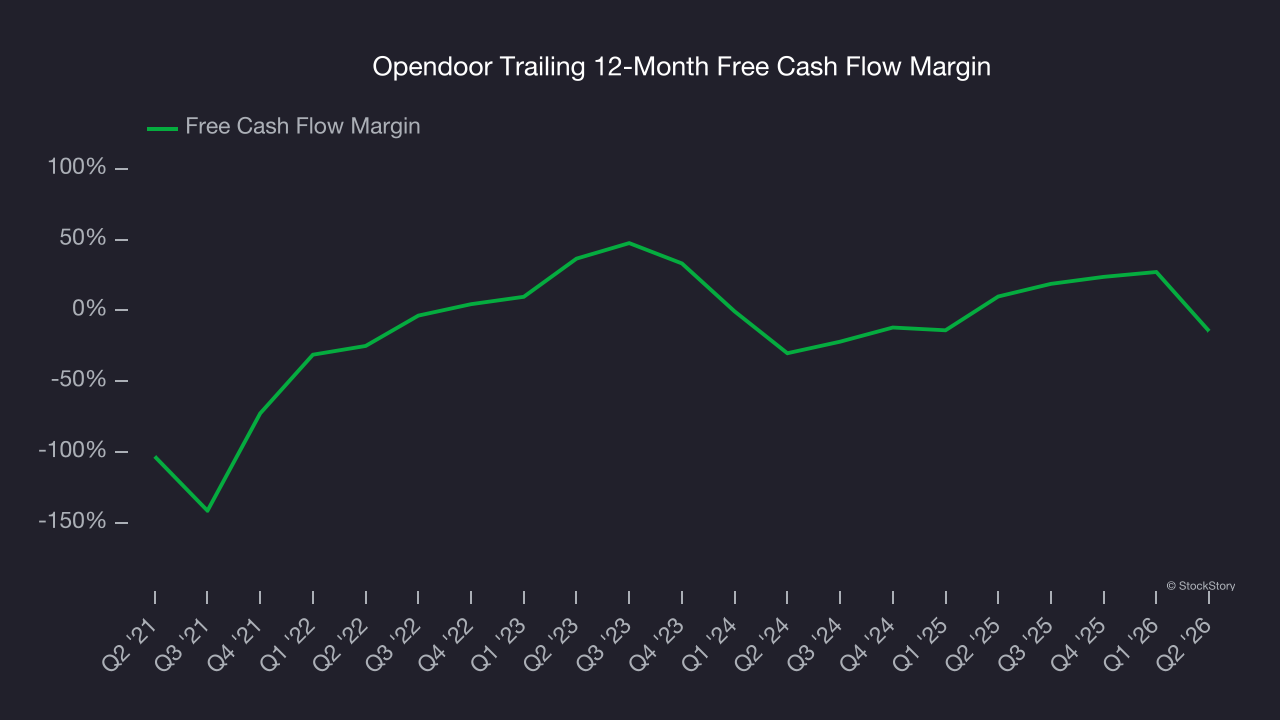
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Opendoor broke even from a free cash flow perspective over the last two years, giving the company limited opportunities to return capital to shareholders.
3. Short Cash Runway Exposes Shareholders to Potential Dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Opendoor burned through $474 million of cash over the last year, and its $1.96 billion of debt exceeds the $896 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
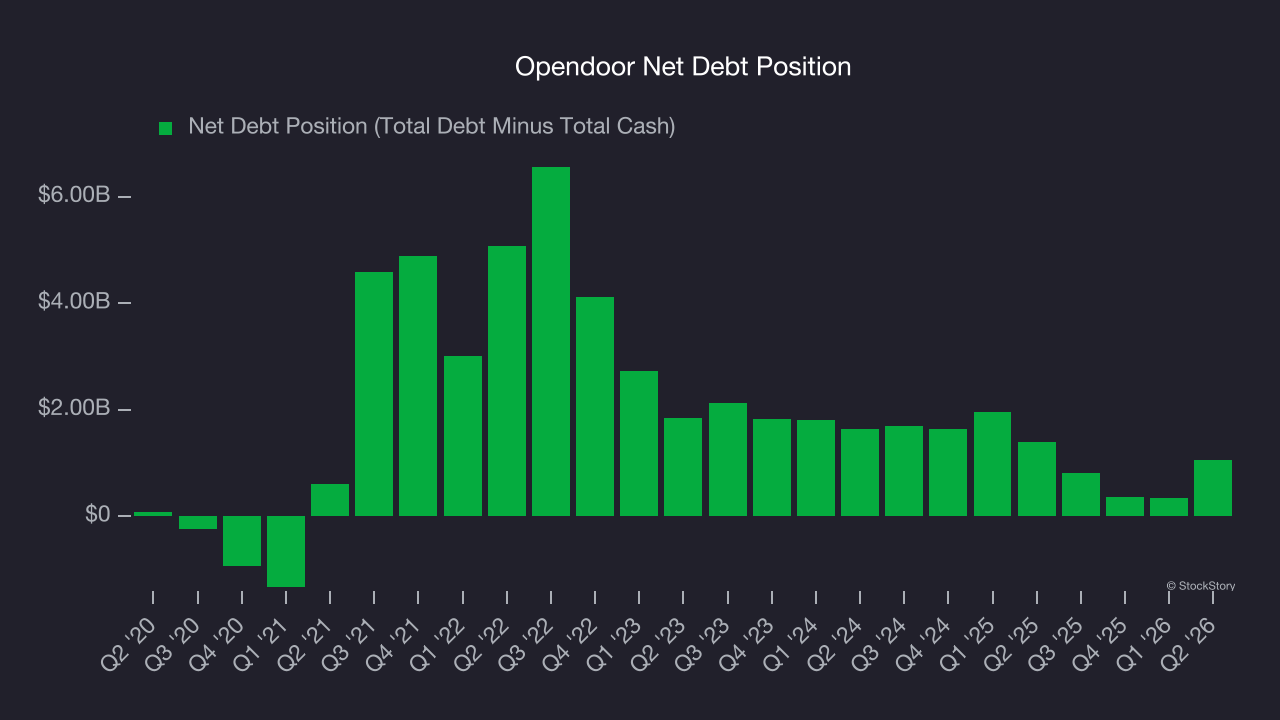
Unless the Opendoor’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of Opendoor until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Opendoor, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 148.4× forward EV-to-EBITDA (or $1.98 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better opportunities elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks We Would Buy Instead of Opendoor
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.