Wingstop has gotten torched over the last six months - since March 2026, its stock price has dropped 29.8% to $108.57 per share. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Following the pullback, is now a good time to buy WING? Find out in our full research report, it’s free.
Why Is Wingstop a Good Business?
The passion project of two chicken wing aficionados in Texas, Wingstop (NASDAQ: WING) is a popular fast-food chain known for its flavorful and crispy chicken wings offered in a variety of sauces and seasonings.
1. New Restaurants Opening at Breakneck Speed
A restaurant chain’s total number of dining locations often determines how much revenue it can generate.
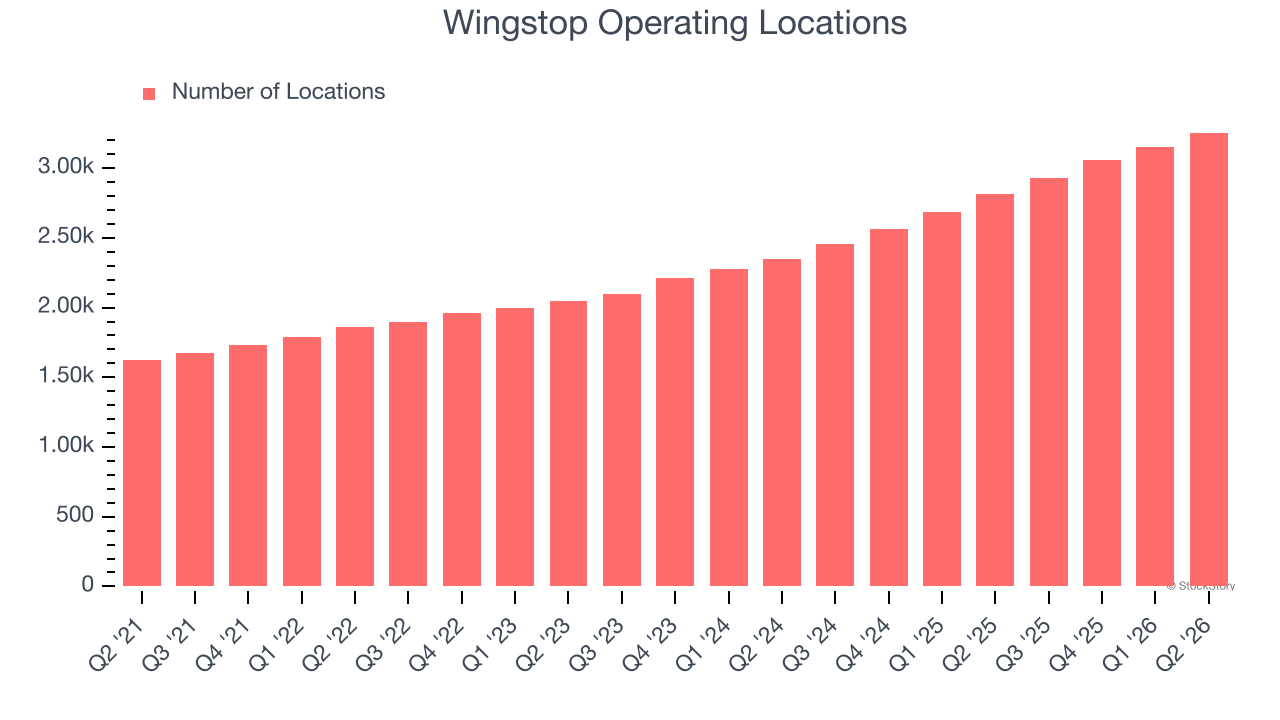
Wingstop sported 3,255 locations in the latest quarter. Over the last two years, it has opened new restaurants at a rapid clip by averaging 17.7% annual growth, among the fastest in the restaurant sector. This gives it a chance to scale into a mid-sized business over time. Additionally, one dynamic making expansion more seamless is the company’s franchise model, where franchisees are primarily responsible for opening new restaurants while Wingstop provides support.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
2. Elite Gross Margin Powers Best-In-Class Business Model
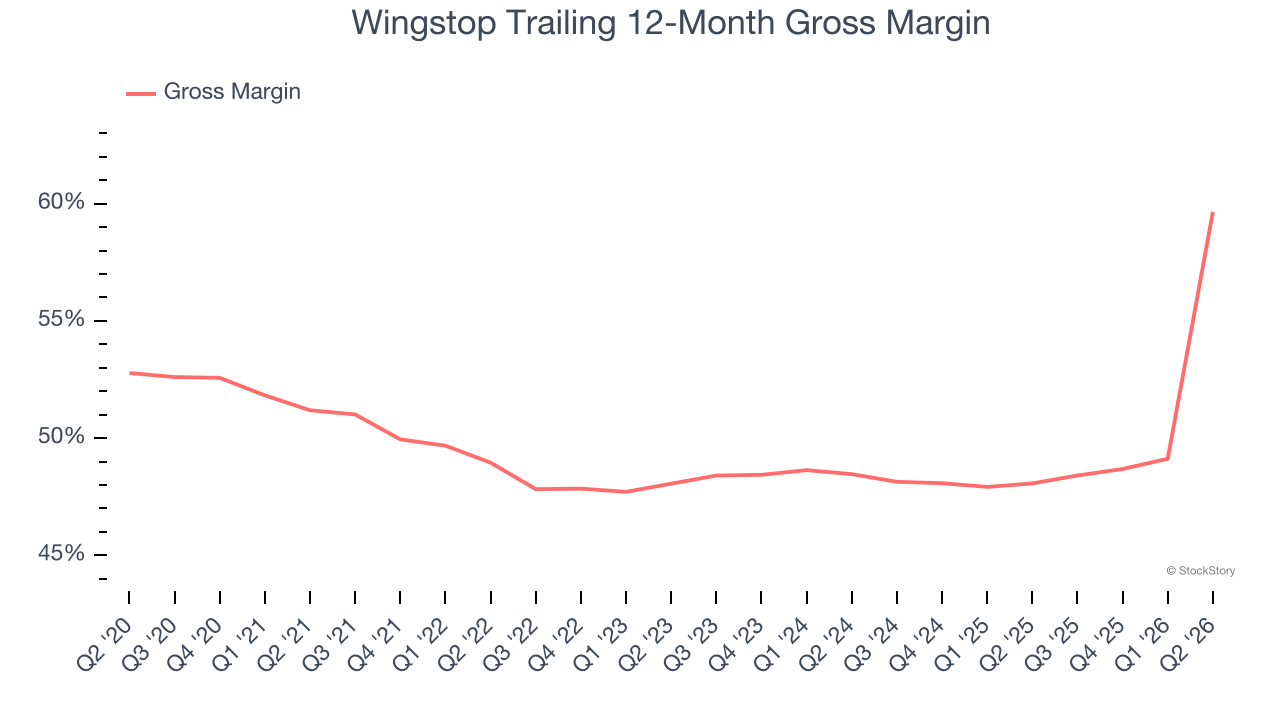
We prefer higher gross margins because they not only make it easier to generate more operating profits but also indicate pricing power and differentiation, whether it be the dining experience or quality and taste of food.
Wingstop has best-in-class unit economics for a restaurant company, enabling it to invest in areas such as marketing and talent. As you can see below, it averaged an elite 54.1% gross margin over the last two years. That means Wingstop only paid its suppliers $45.93 for every $100 in revenue.
3. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
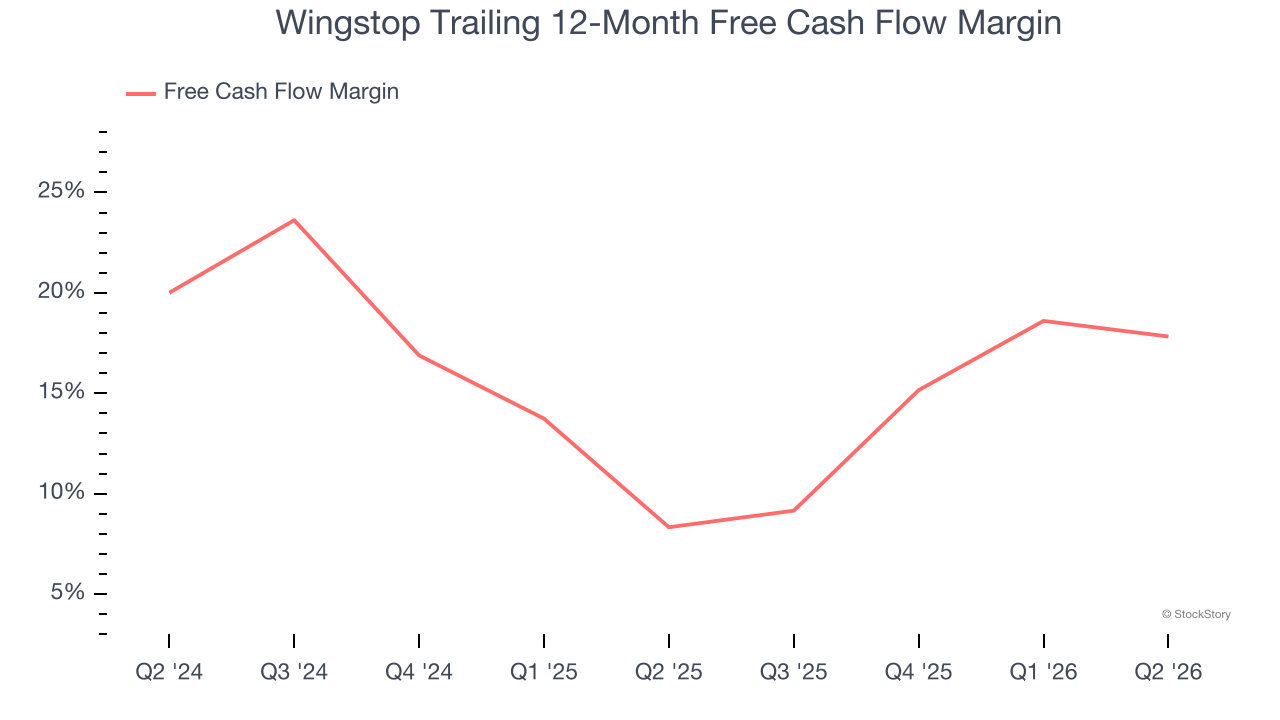
As you can see below, Wingstop’s margin expanded by 9.5 percentage points over the last year. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Wingstop’s free cash flow margin for the trailing 12 months was 17.8%.
Final Judgment
These are just a few reasons why we think Wingstop is a great business. After the recent drawdown, the stock trades at 21.5× forward P/E (or $108.57 per share). Is now the time to initiate a position? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.