Electronics manufacturing services provider Jabil (NYSE: JBL) reported calendar Q3 2026 (fiscal Q4 2026) results exceeding the market’s revenue expectations, with sales up 28.6% year on year to $10.62 billion. On top of that, next quarter’s revenue guidance ($11 billion at the midpoint) was surprisingly good and 9.9% above what analysts were expecting. Its non-GAAP profit of $4.40 per share was 8% above analysts’ consensus estimates.
Is now the time to buy Jabil? Find out by accessing our full research report, it’s free.
Jabil (JBL) Q3 CY2026 Highlights:
- Revenue: $10.62 billion vs analyst estimates of $9.66 billion (28.6% year-on-year growth, 9.8% beat)
- Adjusted EPS: $4.40 vs analyst estimates of $4.08 (8% beat)
- Revenue Guidance for Q4 CY2026 is $11 billion at the midpoint, above analyst estimates of $10.01 billion
- Adjusted EPS guidance for the upcoming financial year 2027 is $17.55 at the midpoint, beating analyst estimates by 3.8%
- Operating Margin: 5.7%, up from 4.1% in the same quarter last year
- Free Cash Flow Margin: 5.1%, down from 6.1% in the same quarter last year
- Market Capitalization: $33.41 billion
Company Overview
With manufacturing facilities spanning the globe from China to Mexico to the United States, Jabil (NYSE: JBL) provides electronics design, manufacturing, and supply chain solutions to companies across various industries, from healthcare to automotive to cloud computing.
Revenue Growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $35.95 billion in revenue over the past 12 months, Jabil is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For Jabil to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
As you can see below, Jabil’s sales grew at a mediocre 4.2% compounded annual growth rate over the last five years. This shows it couldn’t generate demand in any major way and is a tough (but perhaps misleading) starting point for our analysis.
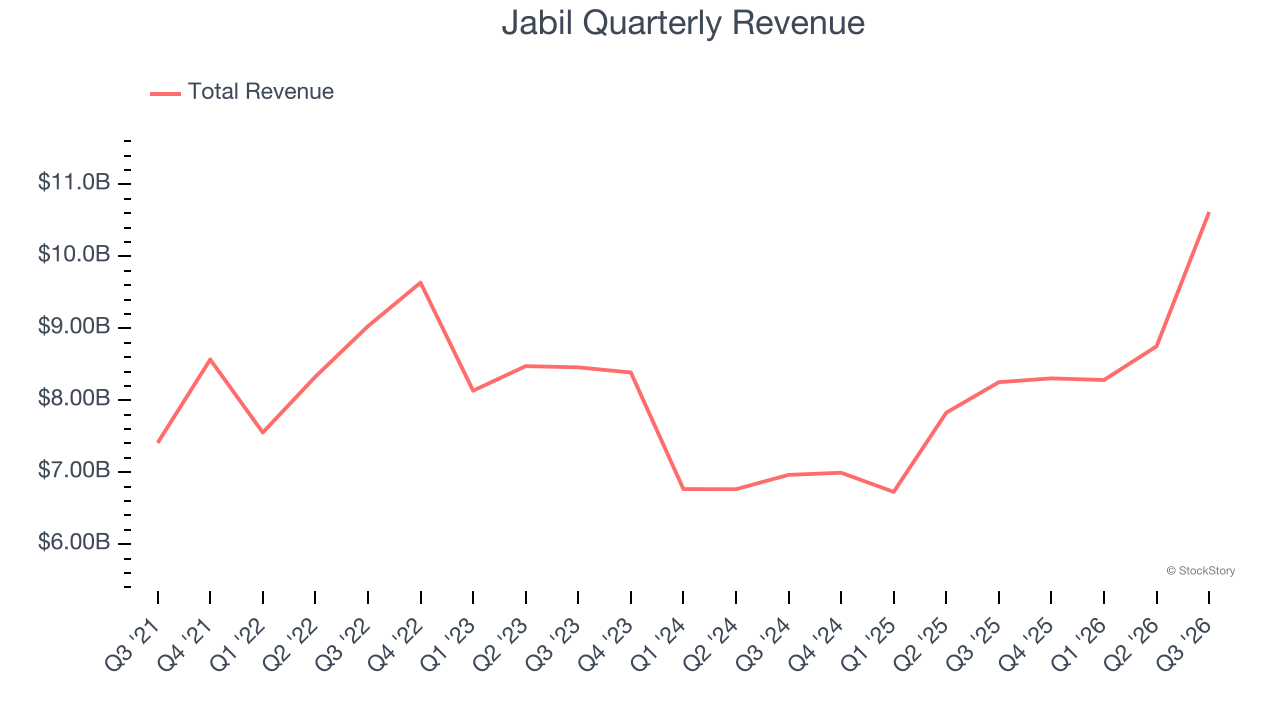
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Jabil’s annualized revenue growth of 11.6% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 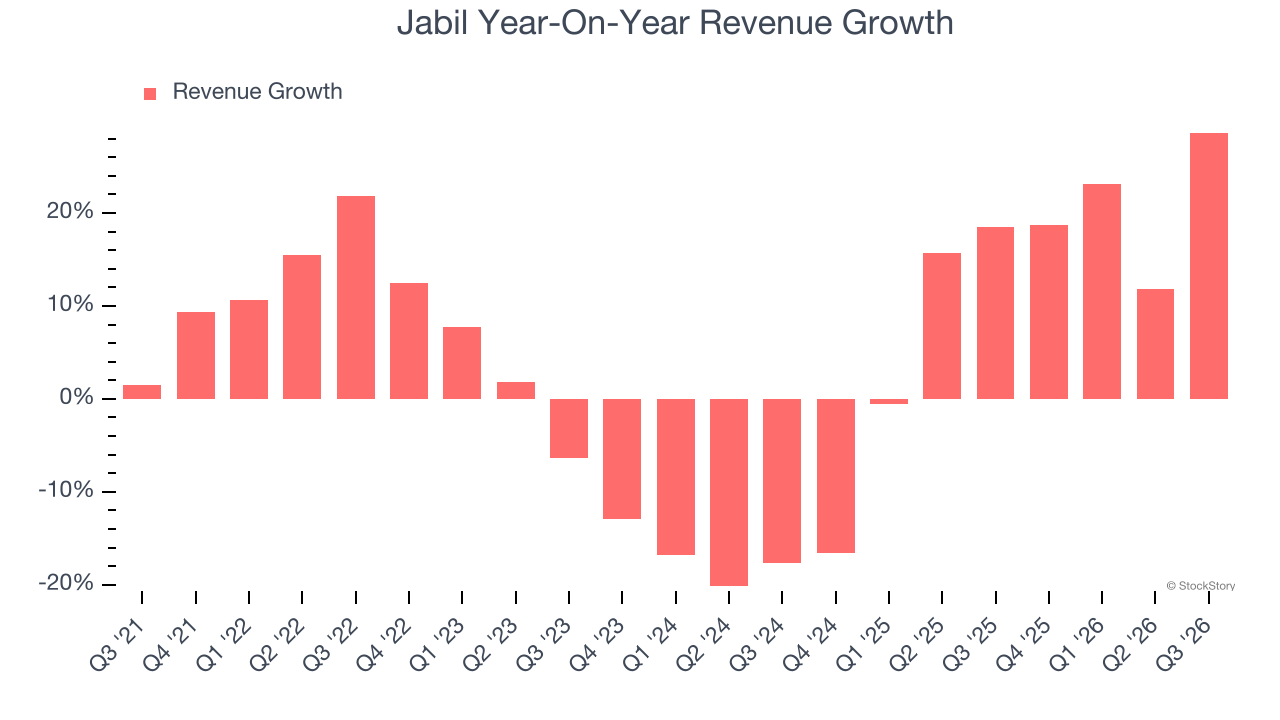
This quarter, Jabil reported robust year-on-year revenue growth of 28.6%, and its $10.62 billion of revenue topped Wall Street estimates by 9.8%. Company management is currently guiding for a 32.5% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 19% over the next 12 months, an improvement versus the last two years. This projection is eye-popping for a company of its scale and indicates its newer products and services will fuel better top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Jabil was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 5.3% was weak for a business services business.
On the plus side, Jabil’s adjusted operating margin rose by 1.3 percentage points over the last five years, as its sales growth gave it operating leverage.
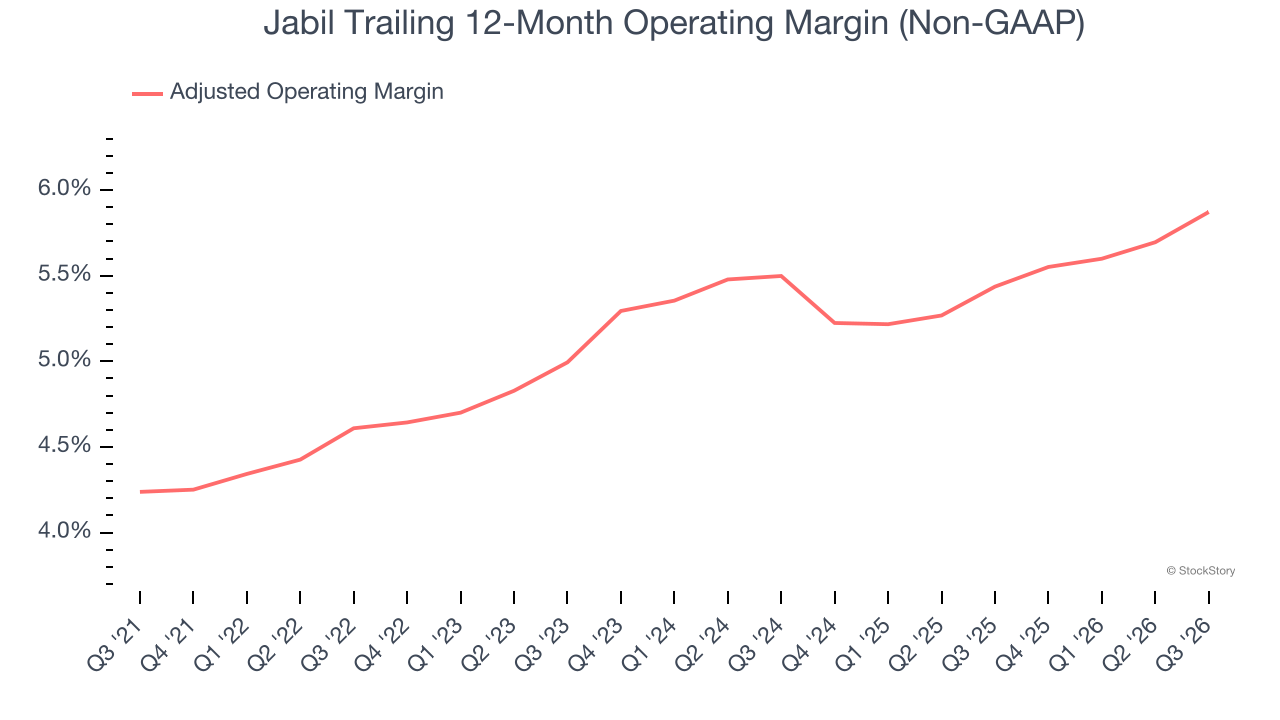
In Q3, Jabil generated an adjusted operating margin profit margin of 6.8%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Jabil’s EPS grew at 18.5% compounded annual growth rate over the last five years, higher than its 4.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
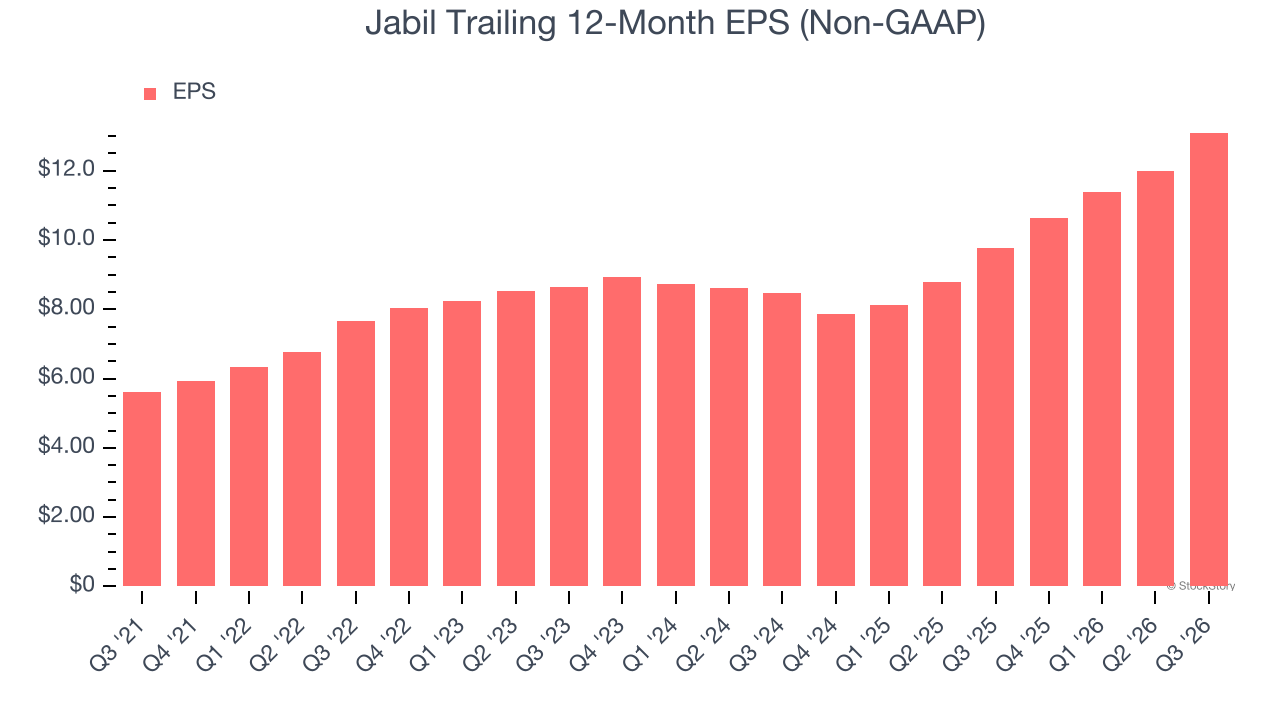
We can take a deeper look into Jabil’s earnings quality to better understand the drivers of its performance. As we mentioned earlier, Jabil’s adjusted operating margin was flat this quarter but expanded by 1.3 percentage points over the last five years. On top of that, its share count shrank by 29.4%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 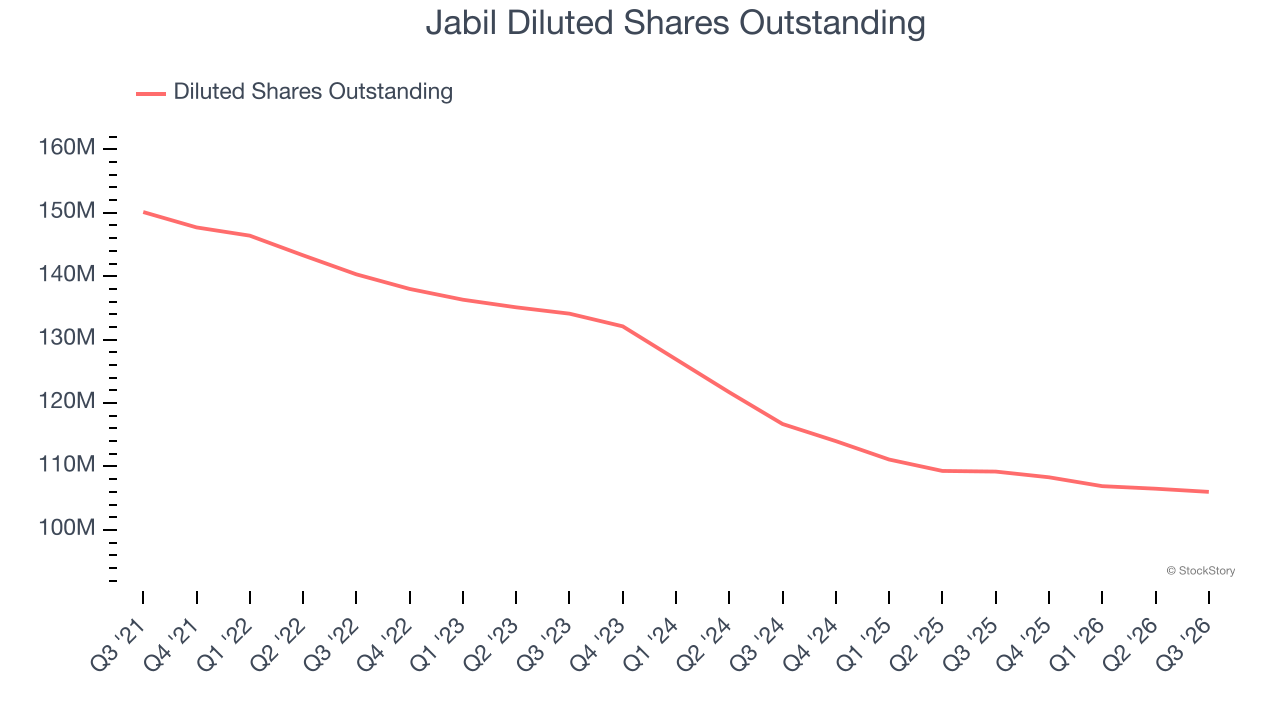
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Jabil, its two-year annual EPS growth of 24.4% was higher than its five-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, Jabil reported adjusted EPS of $4.40, up from $3.29 in the same quarter last year. This print beat analysts’ estimates by 8%. Over the next 12 months, Wall Street expects Jabil’s full-year EPS to grow 28.7% from $13.10 to $16.85.
Key Takeaways from Jabil’s Q3 Results
We were impressed by how significantly Jabil blew past analysts’ EPS guidance for next quarter expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The market seemed to be hoping for more, and the stock traded down 2.8% to $310.01 immediately after reporting.
Is Jabil an attractive investment opportunity right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).