As the craze of earnings season draws to a close, here’s a look back at some of the most exciting (and some less so) results from Q2. Today, we are looking at specialty finance stocks, starting with Oaktree Specialty Lending (NASDAQ: OCSL).
Specialty finance companies provide targeted lending or financial services for specific industries or needs. They benefit from expertise in particular sectors, often reduced competition in specialized niches, and tailored underwriting that can yield higher margins. Challenges include concentration risk in specific industries, difficulty achieving scale efficiencies, and potential vulnerability during sector-specific downturns affecting their specialized markets.
The 9 specialty finance stocks we track reported a strong Q2. As a group, revenues missed analysts’ consensus estimates by 4.1%.
While some specialty finance stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 3.6% since the latest earnings results.
Oaktree Specialty Lending (NASDAQ: OCSL)
Managed by Oaktree Capital Management, one of the world's premier alternative investment firms, Oaktree Specialty Lending (NASDAQ: OCSL) is a business development company that provides customized financing solutions to mid-market companies across various industries.
Oaktree Specialty Lending reported revenues of $69.43 million, down 7.8% year on year. This print was in line with analysts’ expectations, but overall, it was a mixed quarter for the company with a beat of analysts’ EPS estimates.
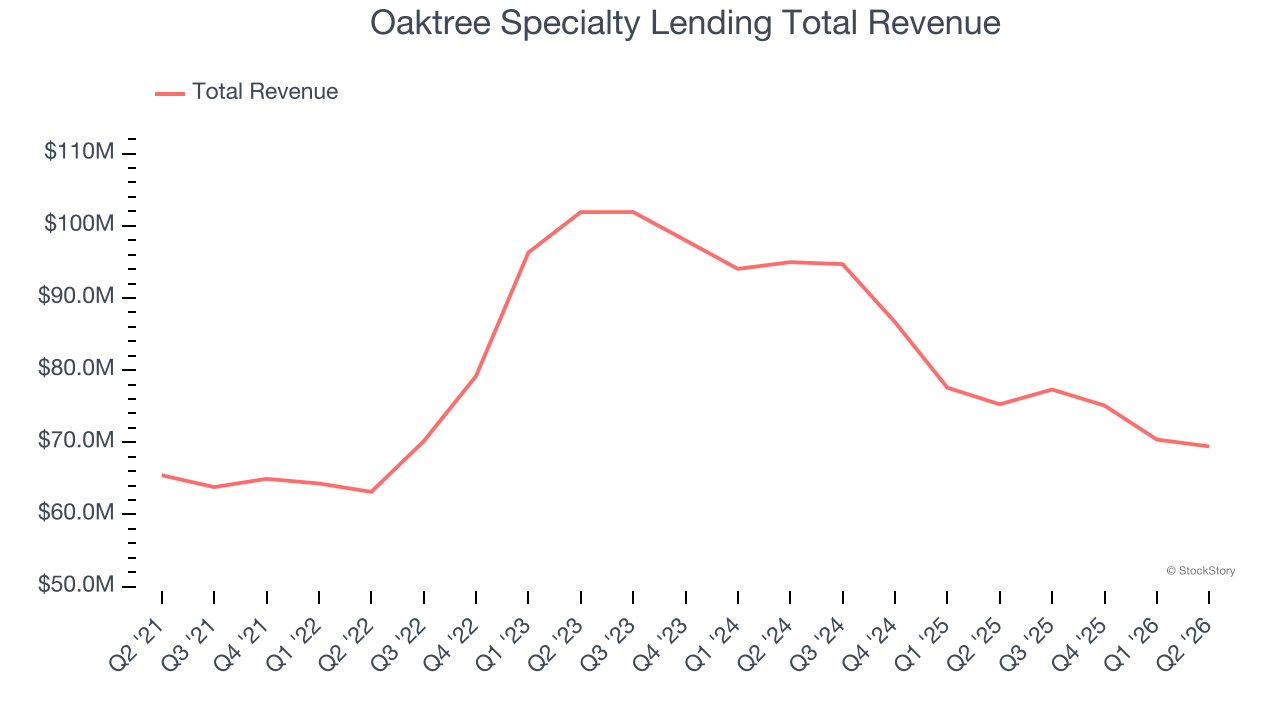
The market seems disappointed with the results as the stock is down 1.2% since reporting and currently trades at $11.99.
Is now the time to buy Oaktree Specialty Lending? Access our full analysis of the earnings results here, it’s free.
Best Q2: PROG (NYSE: PRG)
Evolving from its origins as Aaron's, Inc. before rebranding in 2020, PROG Holdings (NYSE: PRG) provides alternative payment solutions including lease-to-own options and second-look credit products for consumers who may not qualify for traditional financing.
PROG reported revenues of $719.7 million, up 22.3% year on year, outperforming analysts’ expectations by 6.9%. The business had an exceptional quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
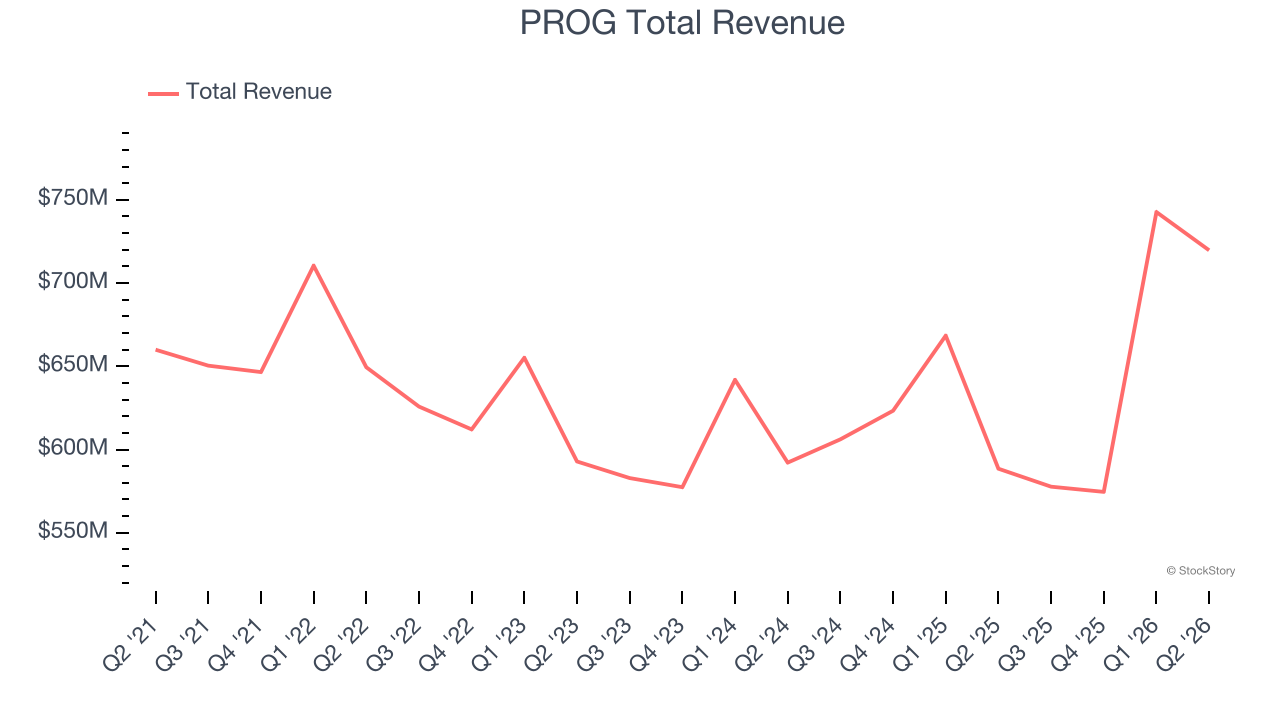
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 29.4% since reporting. It currently trades at $31.85.
Is now the time to buy PROG? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: HA Sustainable Infrastructure Capital (NYSE: HASI)
With a proprietary "CarbonCount" metric that quantifies the environmental impact of each dollar invested, HA Sustainable Infrastructure Capital (NYSE: HASI) is an investment firm that finances and develops climate-positive infrastructure projects across renewable energy, energy efficiency, and ecological restoration.
HA Sustainable Infrastructure Capital reported revenues of $36.32 million, down 64.9% year on year, falling short of analysts’ expectations by 63.1%. It was a softer quarter as it posted a significant miss of analysts’ EBITDA estimates.
HA Sustainable Infrastructure Capital delivered the weakest performance against analyst estimates and slowest revenue growth of the whole group. As expected, the stock is down 5.2% since the results and currently trades at $36.26.
Read our full analysis of HA Sustainable Infrastructure Capital’s results here.
Farmer Mac (NYSE: AGM)
Created by Congress in 1987 to build a bridge between Wall Street and rural America, Farmer Mac (NYSE: AGM) provides a secondary market for agricultural and rural loans, helping lenders increase their liquidity and lending capacity to serve rural America.
Farmer Mac reported revenues of $117.4 million, up 24.9% year on year. This result topped analysts’ expectations by 3.4%. It was a very strong quarter as it also produced a beat of analysts’ EPS estimates.
Farmer Mac scored the fastest revenue growth in the group. The stock is down 2.1% since reporting and currently trades at $215.77.
Read our full, actionable report on Farmer Mac here, it’s free.
Main Street Capital (NYSE: MAIN)
With a focus on building long-term partnerships rather than quick transactions, Main Street Capital (NYSE: MAIN) is a business development company that provides long-term debt and equity capital to lower middle market and middle market companies.
Main Street Capital reported revenues of $149.6 million, up 3.9% year on year. This number surpassed analysts’ expectations by 2.7%. Overall, it was a satisfactory quarter as it also logged EPS in line with analysts’ estimates.
The stock is down 2.8% since reporting and currently trades at $55.20.
Read our full, actionable report on Main Street Capital here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.