
Quarterly earnings results are a good time to check in on a company’s progress, especially compared to its peers in the same sector. Today we are looking at Chevron (NYSE: CVX) and the best and worst performers in the diversified upstream e&p industry.
Large cap diversified exploration and production (E&P) companies operate global portfolios spanning multiple basins and resource types, providing geographic and commodity diversification. Scale enables operational efficiencies, capital market access, and investment in advanced technologies. Tailwinds include disciplined capital allocation improving shareholder returns, diversified production bases reducing single-asset risk, and strong balance sheets supporting dividend programs. Headwinds include commodity price volatility affecting earnings, regulatory and geopolitical risks across operating regions, and ESG pressures challenging long-term investment theses. The energy transition creates strategic uncertainty around reserve life and future demand trajectories.
The 5 diversified upstream e&p stocks we track reported a stunning Q2. As a group, revenues beat analysts’ consensus estimates by 9.7%.
Luckily, diversified upstream e&p stocks have performed well with share prices up 13% on average since the latest earnings results.
Weakest Q2: Chevron (NYSE: CVX)
Operating everything from deepwater drilling rigs to corner gas stations, Chevron (NYSE: CVX) explores for, produces, and transports crude oil and natural gas, then refines that crude oil into gasoline, diesel, and other petroleum products.
Chevron reported revenues of $70.06 billion, up 56.3% year on year. This print exceeded analysts’ expectations by 6.2%. Overall, it was an exceptional quarter for the company with a beat of analysts’ EPS estimates.
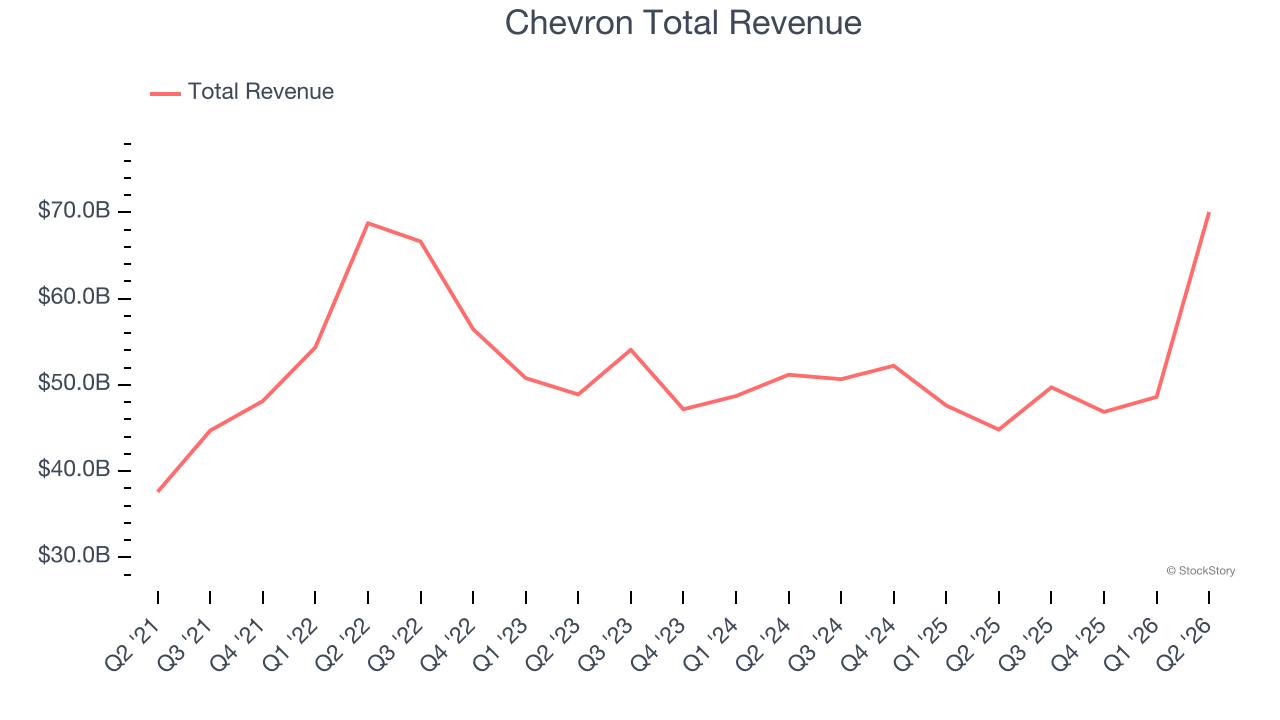
Chevron delivered the weakest performance against analyst estimates of the whole group. Interestingly, the stock is up 11.4% since reporting and currently trades at $214.20.
Is now the time to buy Chevron? Access our full analysis of the earnings results here, it’s free.
Best Q2: Occidental Petroleum (NYSE: OXY)
Backed by Warren Buffett's Berkshire Hathaway as a major shareholder, Occidental Petroleum (NYSE: OXY) explores for, develops, and produces oil, natural gas liquids, and natural gas, primarily in the United States and Middle East.
Occidental Petroleum reported revenues of $8.33 billion, up 57.1% year on year, outperforming analysts’ expectations by 15.3%. The business had an incredible quarter with a beat of analysts’ EPS estimates.
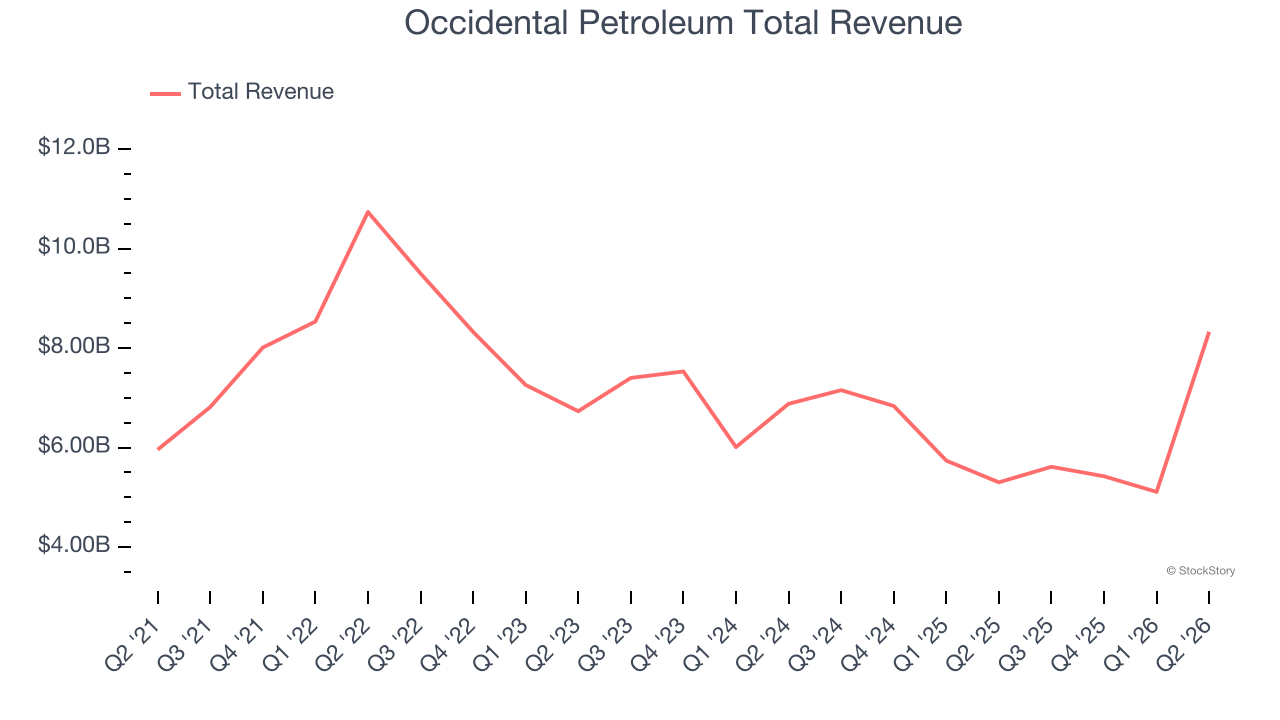
Occidental Petroleum pulled off the biggest analyst estimate beat in the group. The market seems happy with the results as the stock is up 14% since reporting. It currently trades at $61.35.
Is now the time to buy Occidental Petroleum? Access our full analysis of the earnings results here, it’s free.
ConocoPhillips (NYSE: COP)
Operating the famous Prudhoe Bay field discovered in 1968 that transformed Alaska's economy, ConocoPhillips (NYSE: COP) explores for and produces crude oil, natural gas, and liquefied natural gas across North America, Europe, Asia, and Africa.
ConocoPhillips reported revenues of $19.52 billion, up 32.4% year on year, exceeding analysts’ expectations by 9.6%. It may have had the worst quarter among its peers, but its results were still good as it also locked in a beat of analysts’ EPS estimates.
ConocoPhillips delivered the slowest revenue growth among its peers. Interestingly, the stock is up 19.6% since the results and currently trades at $137.64.
Read our full analysis of ConocoPhillips’s results here.
ExxonMobil (NYSE: XOM)
One of the successor companies to John D. Rockefeller's Standard Oil monopoly that was broken up in 1911, ExxonMobil (NYSE: XOM) explores for and produces crude oil and natural gas, refines and sells petroleum products, and manufactures petrochemicals.
ExxonMobil reported revenues of $116 billion, up 42.3% year on year. This number beat analysts’ expectations by 6.8%. It was a stunning quarter as it also recorded a beat of analysts’ EPS estimates.
The stock is up 5.9% since reporting and currently trades at $166.17.
Read our full, actionable report on ExxonMobil here, it’s free.
Devon Energy (NYSE: DVN)
With operations spanning from the oil-rich Delaware Basin to the Bakken formation of North Dakota, Devon Energy (NYSE: DVN) explores for and produces oil, natural gas, and natural gas liquids from wells drilled across the United States.
Devon Energy reported revenues of $6.89 billion, up 67.4% year on year. This result surpassed analysts’ expectations by 10.3%. Overall, it was an exceptional quarter as it also logged a beat of analysts’ EPS estimates.
Devon Energy achieved the fastest revenue growth of the whole group. The stock is up 14.2% since reporting and currently trades at $50.30.
Read our full, actionable report on Devon Energy here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.