
Over the past six months, Bright Horizons’s shares (currently trading at $65.12) have posted a disappointing 14.8% loss, well below the S&P 500’s 13.3% gain. This might have investors contemplating their next move.
Is now the time to buy Bright Horizons, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Bright Horizons Will Underperform?
Despite the more favorable entry price, we’re passing on Bright Horizons for now. Here are three reasons we avoid BFAM, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
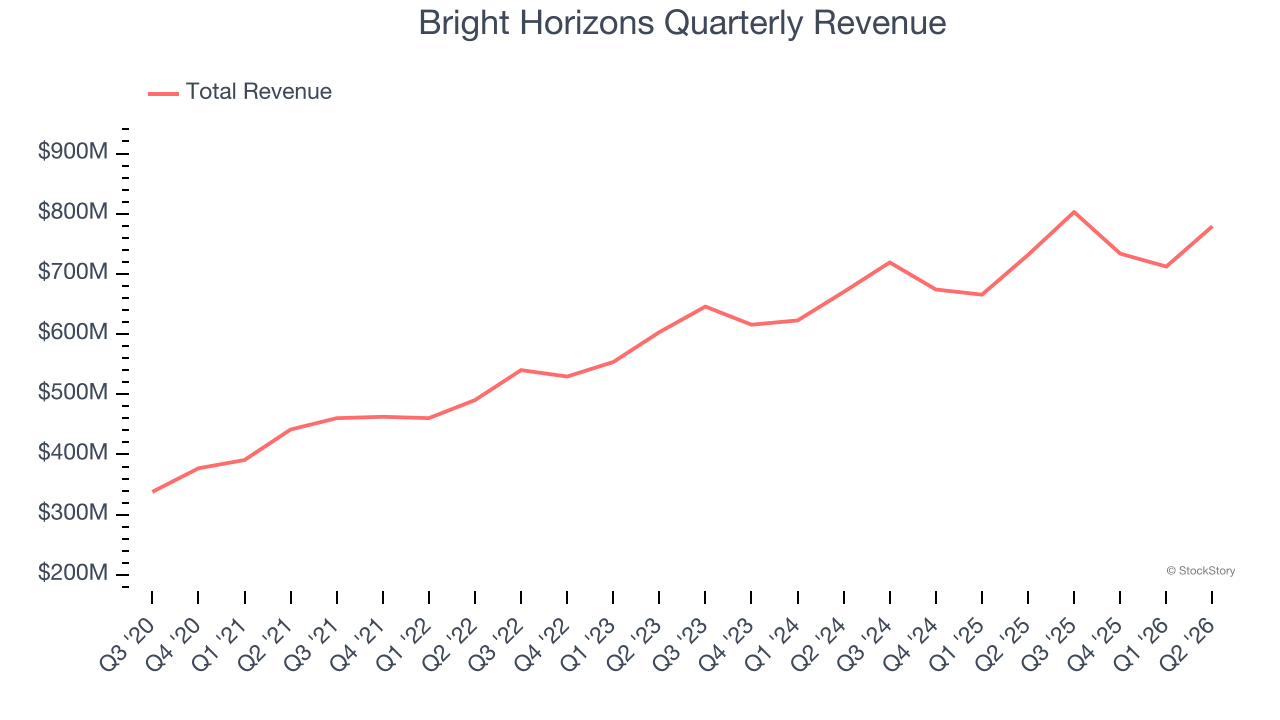
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Bright Horizons grew its sales at a 14.4% compounded annual growth rate. Although this growth is acceptable on an absolute basis, it fell short of our standards for the consumer discretionary sector, which enjoys a number of secular tailwinds.
2. Free Cash Flow Projections Disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates show they’re expecting Bright Horizons’s free cash flow margin of 7.8% for the last 12 months to remain the same.
3. New Investments Bear Fruit as ROIC Jumps
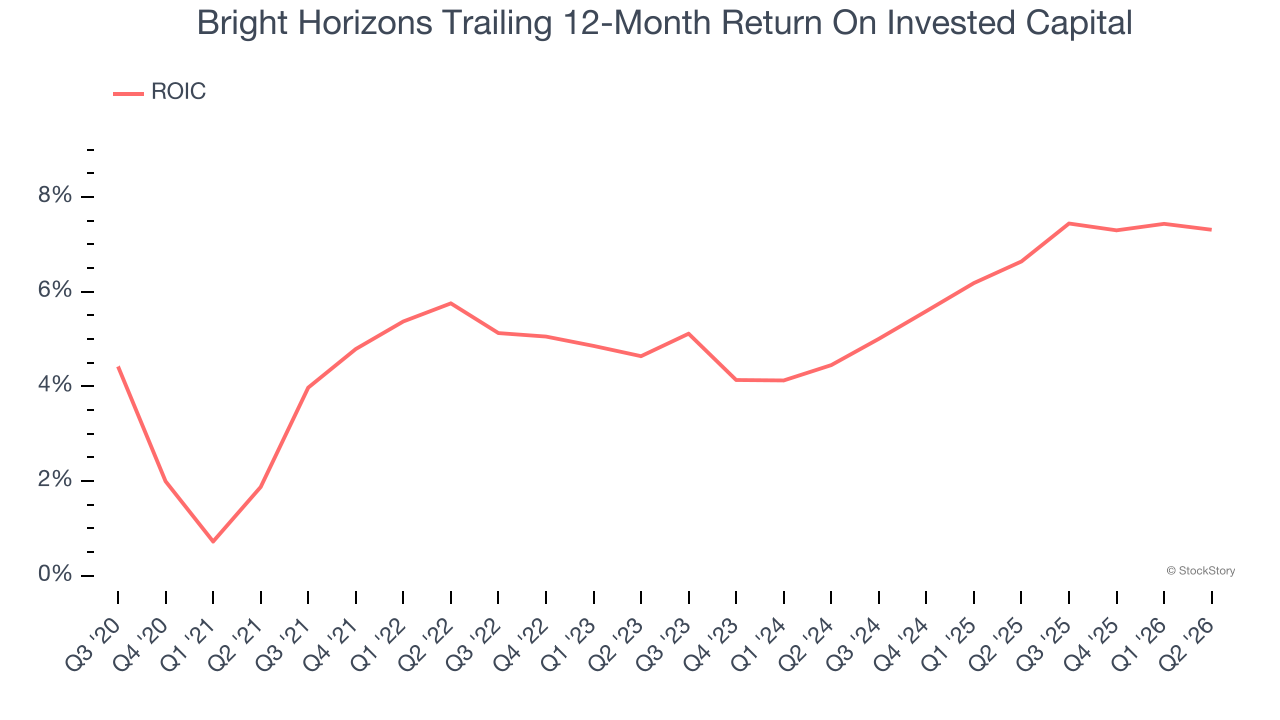
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Bright Horizons’s ROIC averaged 1.8 percentage point increases each year. This is a good sign, and we hope the company can continue improving.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Bright Horizons, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 11.9× forward P/E (or $65.12 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. There are better investments elsewhere. We’d recommend looking at a top digital advertising platform riding the creator economy.
Stocks We Like More Than Bright Horizons
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.