IT solutions provider CDW (NASDAQGS:CDW) announced better-than-expected revenue in Q3 2026, as revenue rose 17.7% year on year to $6.75 billion. Its non-GAAP profit of $3.26 per share was 9.4% above analysts’ consensus estimates.
For more on CDW, read our free full research report.
CDW (CDW) Q3 2026 highlights:
- Revenue $6.75 billion vs S&P analysts’ consensus estimates of $6.18 billion (17.7% year-on-year growth, 9.3% beat)
- Adjusted EPS $3.26 vs S&P analysts’ consensus estimates of $2.98 (9.4% beat)
- Operating margin 7.2%, in line with the same quarter last year
- Free cash flow margin 8%, up from 3.6% in the same quarter last year
- Market capitalization $18.72 billion
"In an environment defined by rapid technology change and increasing complexity, CDW’s role as a trusted advisor has never been more important," Leahy concluded. "Our ability to address customers’ needs across the full technology stack and lifecycle, together with our continued strategic investments, reinforces our confidence in our ability to outpace US IT addressable market growth by 200 to 300 basis points on a constant currency basis and drive sustainable long-term value for our customers and shareholders."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $24.52 billion in revenue over the past 12 months, CDW is a large company in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also gives it more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because finding new avenues for growth becomes difficult when it already has a substantial market presence. To accelerate revenue growth, CDW likely needs to optimize its pricing or focus on new offerings and international expansion.
CDW’s 3.9% annualized revenue growth over the last five years was tepid. This shows it failed to generate substantial demand growth.
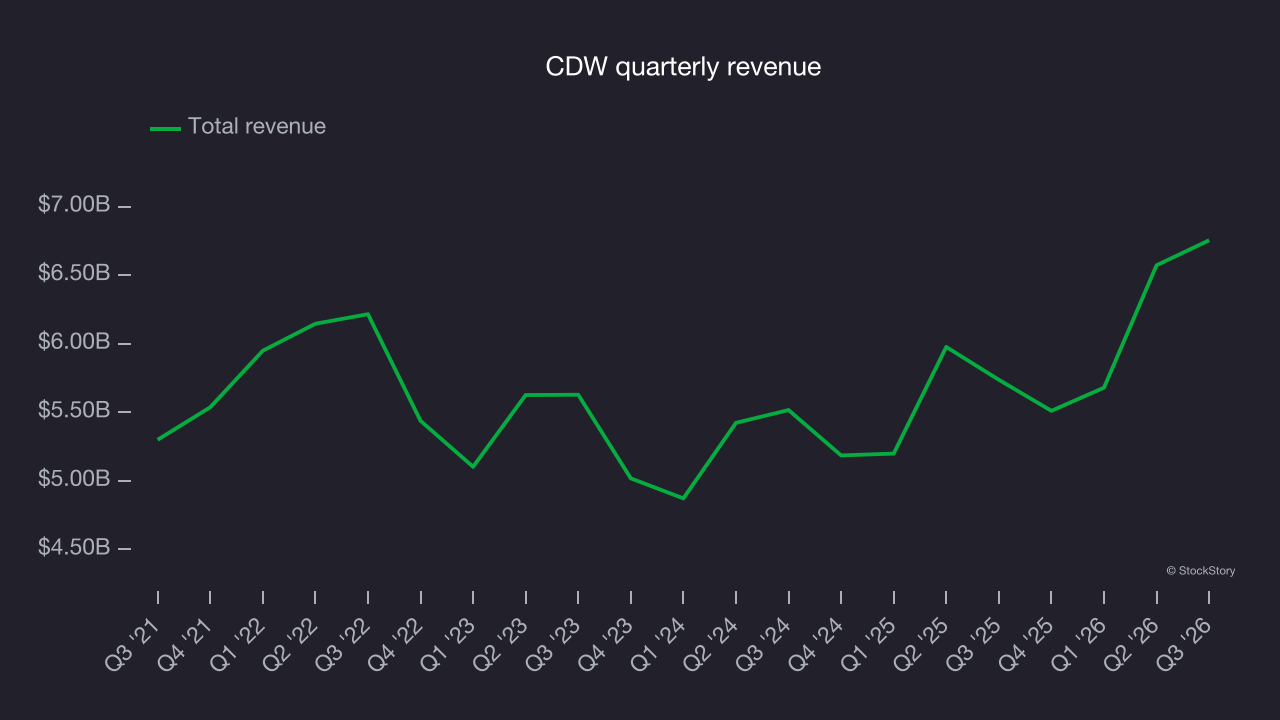
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. CDW’s annualized revenue growth of 8.5% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 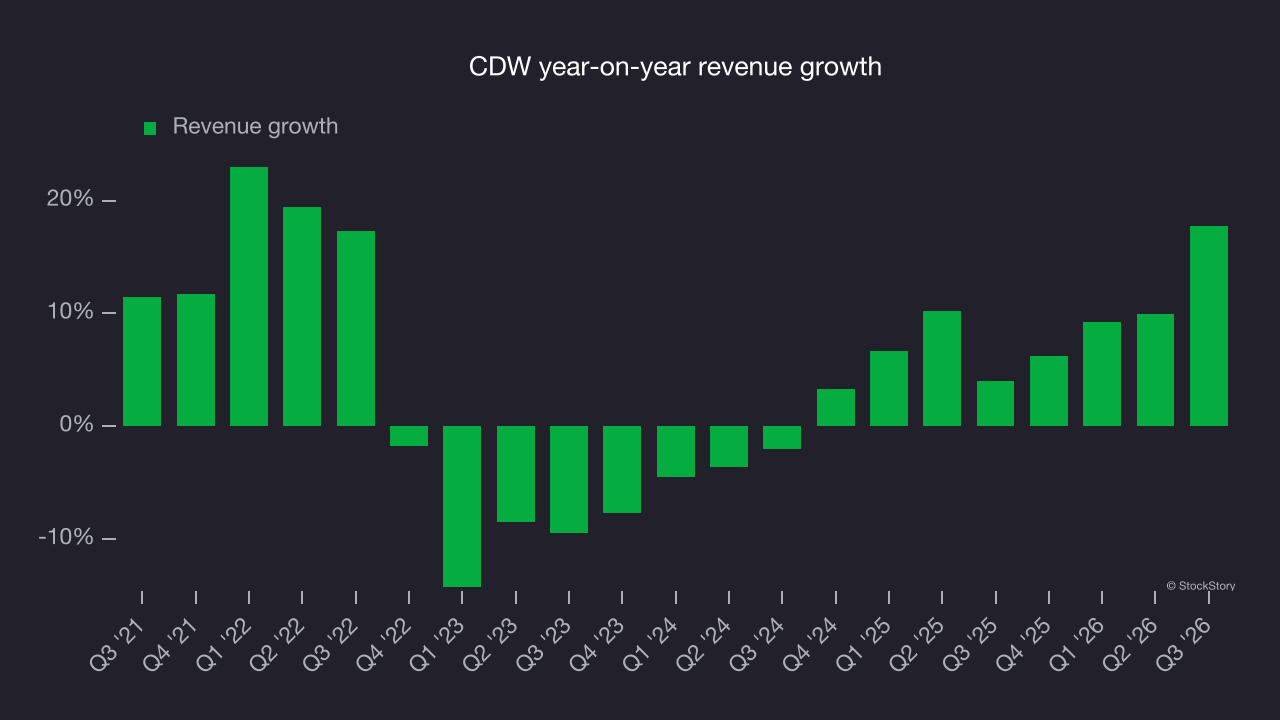
This quarter, CDW reported year-on-year revenue growth of 17.7%, and its $6.75 billion of revenue exceeded Wall Street’s consensus estimates by 9.3%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Adjusted operating margin
CDW’s adjusted operating margin has generally stayed the same over the last 12 months, averaging 8.8% over the last five years. This profitability was mediocre for a business services company and stemmed from its suboptimal cost structure.
Looking at the trend in its profitability, CDW’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
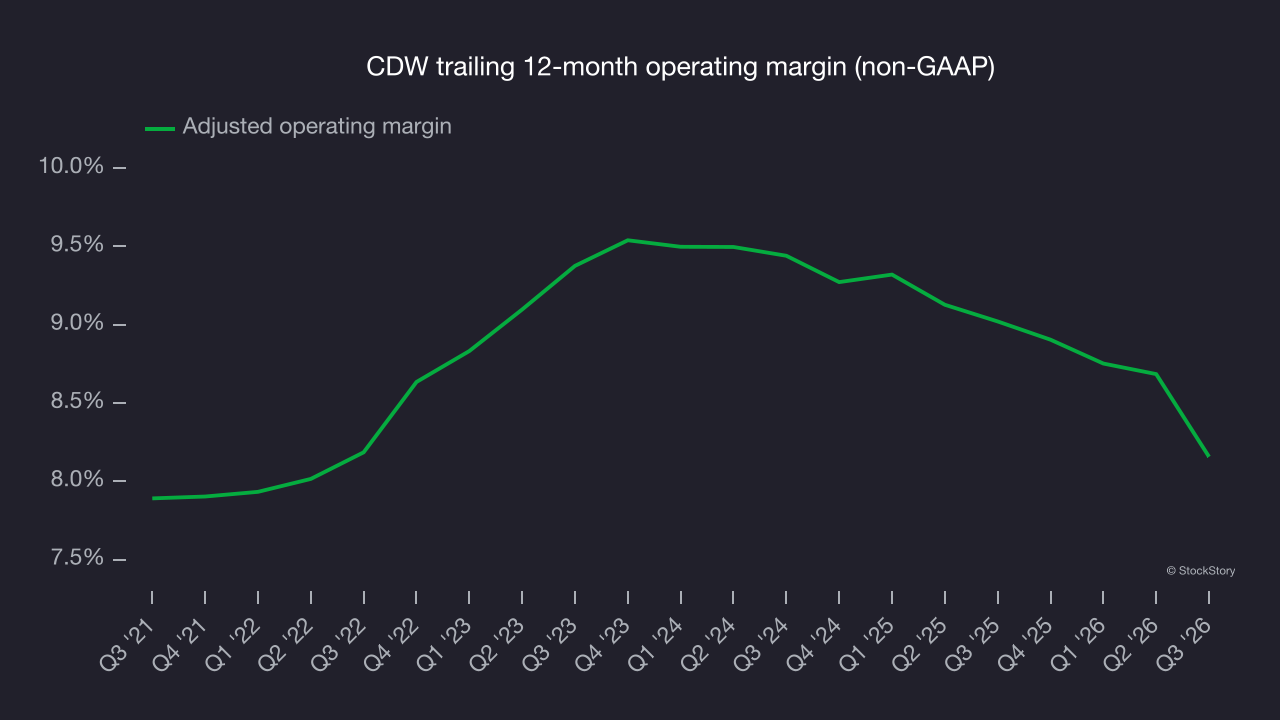
This quarter, CDW generated an adjusted operating margin of 7.2%, down 2 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
CDW’s EPS grew at a 7.4% compounded annual growth rate over the last five years. This performance was better than its revenue growth but says little about its business quality because its adjusted operating margin improved less than peers’ margins.
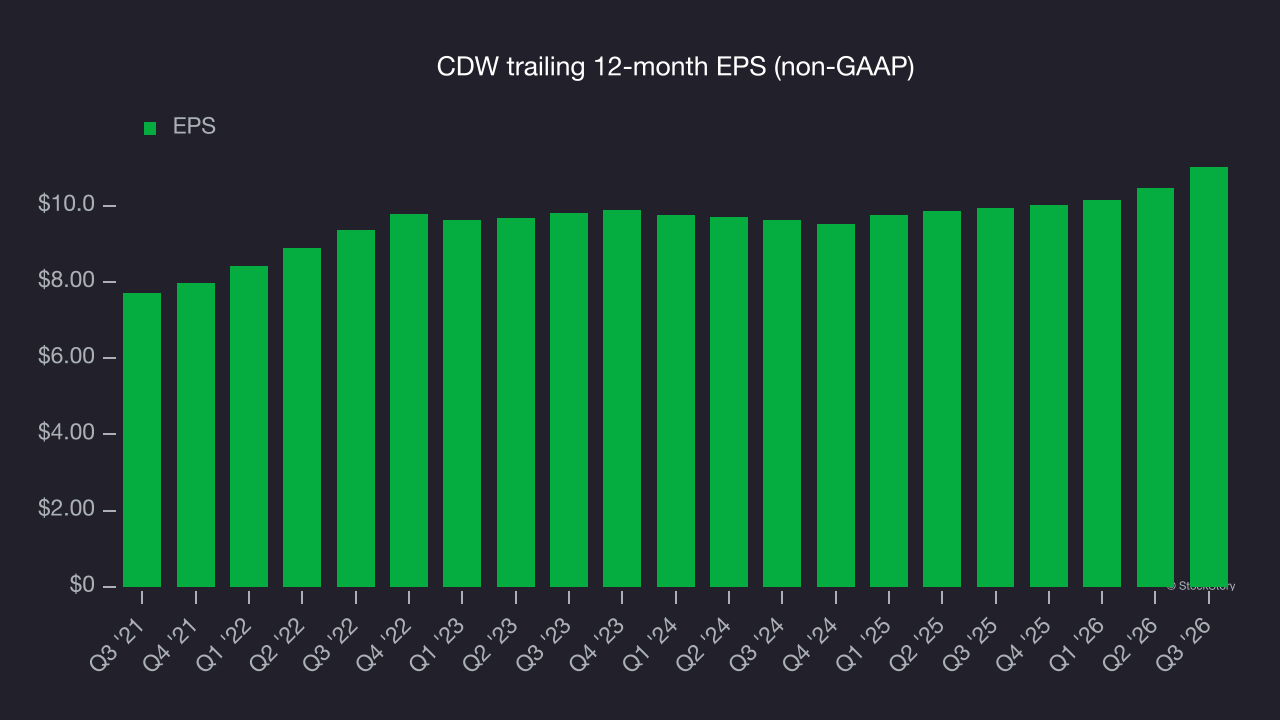
As with revenue, examining EPS over a shorter period can reveal changes in the business.
For CDW, its two-year annual EPS growth of 7% is similar to its five-year trend, implying stable earnings.
In Q3, CDW reported adjusted EPS of $3.26, up from $2.71 in the same quarter last year. This result beat analysts’ consensus estimates by 9.4%. Over the next 12 months, Wall Street expects CDW’s full-year EPS to grow 6.6% from $11.02 to $11.75, according to S&P.
Key takeaways from CDW’s Q3 results
CDW delivered a solid quarter, with revenue well ahead of analysts’ consensus estimates and EPS also topping Wall Street’s estimates. Shares rose 3.2% to $154.61 immediately after the release.
CDW had a solid quarter, but assessing the stock requires a broader view. The latest quarter matters, but longer-term fundamentals and valuation matter much more when deciding whether to invest. Read the full research report here (it’s free).