Beer, wine, and spirits company Constellation Brands (NYSE: STZ) reported calendar Q3 2026 (fiscal Q2 2027) results topping the market’s revenue expectations, with sales up 6.1% year on year to $2.63 billion. On the other hand, the company’s full-year revenue guidance of $9 billion at the midpoint came in 0.9% below analysts’ estimates. Its non-GAAP profit of $3.74 per share was 5.5% above analysts’ consensus estimates.
Is now the time to buy Constellation Brands? Find out by accessing our full research report, it’s free.
Constellation Brands (STZ) Q3 CY2026 Highlights:
- Revenue: $2.63 billion vs analyst estimates of $2.53 billion (6.1% year-on-year growth, 3.9% beat)
- Adjusted EPS: $3.74 vs analyst estimates of $3.55 (5.5% beat)
- The company reconfirmed its revenue guidance for the full year of $9 billion at the midpoint
- Management reiterated its full-year Adjusted EPS guidance of $11.55 at the midpoint
- Operating Margin: 30.6%, down from 35.2% in the same quarter last year
- Free Cash Flow Margin: 24.3%, down from 25.6% in the same quarter last year
- Market Capitalization: $19.35 billion
Company Overview
With a presence in more than 100 countries, Constellation Brands (NYSE: STZ) is a globally renowned producer and marketer of beer, wine, and spirits.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $9.21 billion in revenue over the past 12 months, Constellation Brands is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when your existing brands have penetrated most of the market. For Constellation Brands to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
As you can see below, Constellation Brands struggled to generate demand over the last three years. Its sales dropped by 2% annually, a tough starting point for our analysis.
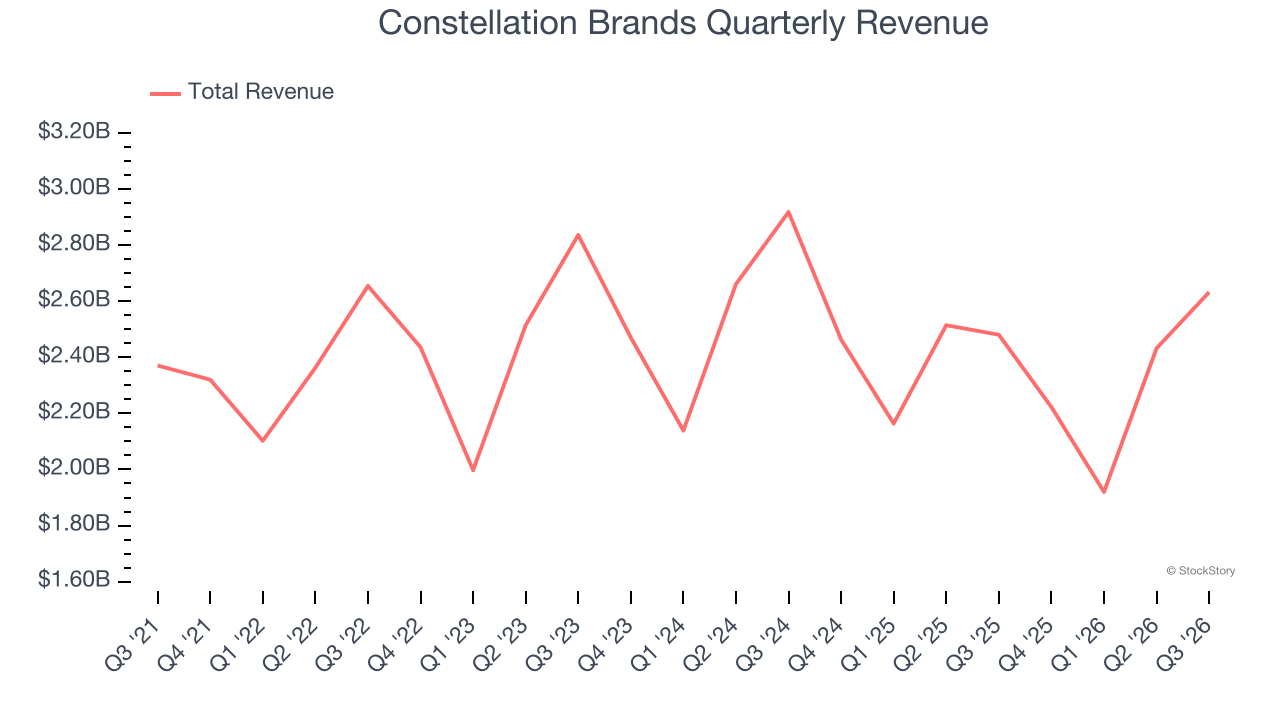
This quarter, Constellation Brands reported year-on-year revenue growth of 6.1%, and its $2.63 billion of revenue exceeded Wall Street’s estimates by 3.9%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months. Although this projection indicates its newer products will catalyze better top-line performance, it is still below the sector average.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Cash Is King
Although earnings are undoubtedly valuable for assessing company performance, we believe cash is king because you can’t use accounting profits to pay the bills.
Constellation Brands has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 19.6% over the last two years.
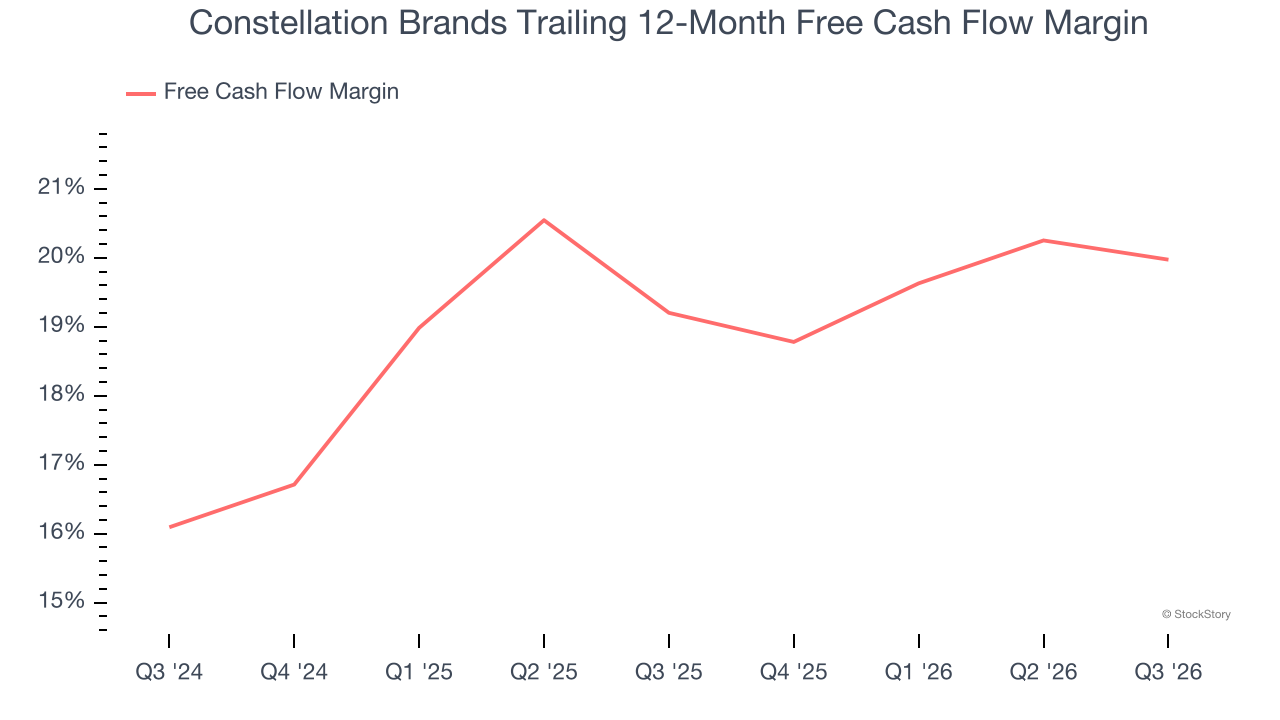
Constellation Brands’s free cash flow clocked in at $639.9 million in Q3, equivalent to a 24.3% margin. The company’s cash profitability regressed as it was 1.3 percentage points lower than in the same quarter last year, but it’s still above its two-year average. We wouldn’t read too much into this quarter’s decline because investment needs can be seasonal, causing short-term swings. Long-term trends are more important.
Key Takeaways from Constellation Brands’s Q3 Results
We enjoyed seeing Constellation Brands beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its full-year revenue guidance slightly missed and its full-year EPS guidance fell slightly short of Wall Street’s estimates. Zooming out, we think this was a mixed quarter. The market seemed to be hoping for more, especially with regards to guidance, and the stock traded down 5.4% to $110.15 immediately after reporting.
Is Constellation Brands an attractive investment opportunity right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).