Clothing and footwear retailer Boot Barn (NYSE: BOOT) met Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue up 15.1% year on year to $581.8 million. On the other hand, next quarter’s revenue guidance of $793.5 million was less impressive, coming in 3% below analysts’ consensus estimates. Its GAAP profit of $1.73 per share was 6% above analysts’ consensus estimates.
For more on Boot Barn, read the full research report, available free.
Boot Barn (BOOT) Q3 CY2026 highlights:
- Revenue $581.8 million vs S&P analysts’ consensus estimates of $580.5 million (15.1% year-on-year growth, in line)
- EPS (GAAP) $1.73 vs analysts’ consensus estimates of $1.63 (6% beat)
- Revenue guidance The company dropped its revenue guidance for the full year to $2.58 billion at the midpoint from $2.60 billion, a 0.9% decrease
- GAAP EPS guidance $8.86 at the midpoint for the full year, missing analysts’ consensus estimates by 1.6%
- Operating margin 12.1%, in line with the same quarter last year
- Free cash flow -$6.72 million compared to -$17.5 million in the same quarter last year
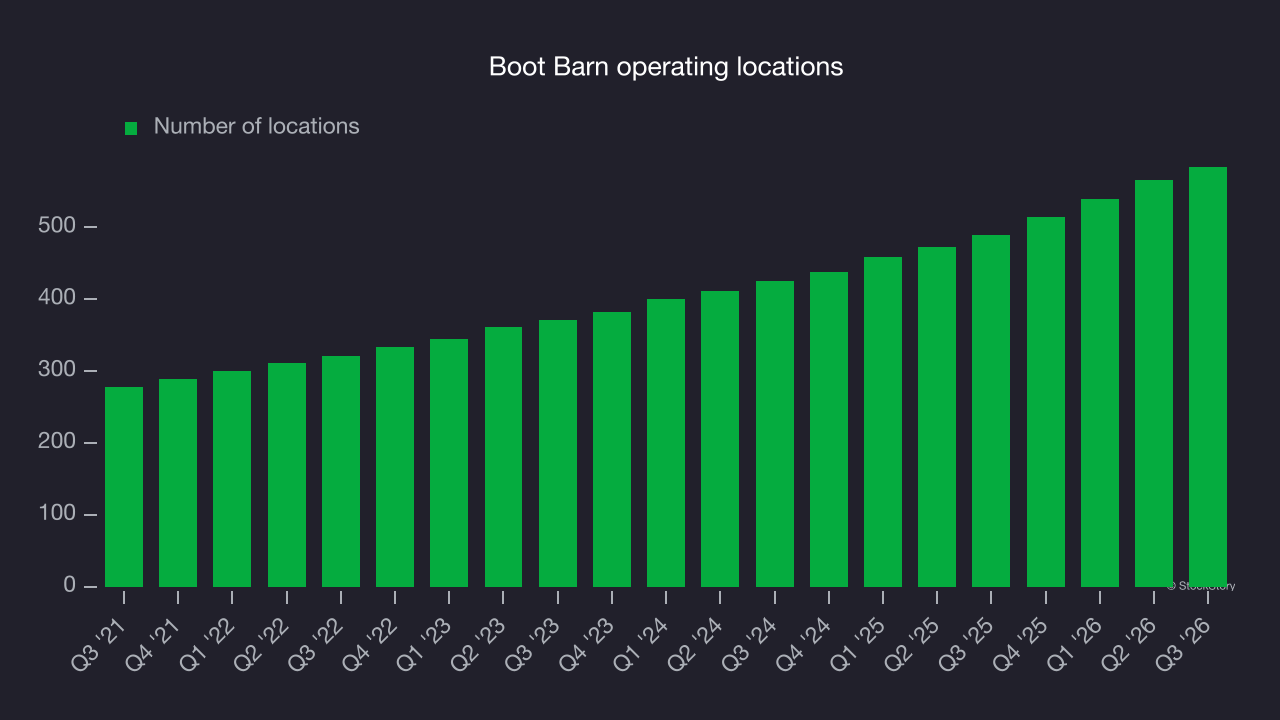
- Locations 584 at quarter end, up from 489 in the same quarter last year
- Same-store sales rose 1.4% year on year (8.4% in the same quarter last year)
- Market capitalization $3.38 billion
John Hazen, Chief Executive Officer, commented, “We are pleased with our second quarter results, as continued revenue growth and merchandise margin expansion contributed to a 26% increase in earnings per diluted share. Our new stores continue to exceed expectations, with recent openings generating sales above our original projections. This performance reflects the growing national reach of the Boot Barn brand and reinforces our confidence in the company's long-term expansion opportunity.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years.
With $2.42 billion in revenue over the past 12 months, Boot Barn is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers. On the positive side, it can grow faster because it has more room to build new stores.
Boot Barn’s 12.5% annualized revenue growth over the last three years was solid as it opened new stores and increased revenue at existing, established locations.
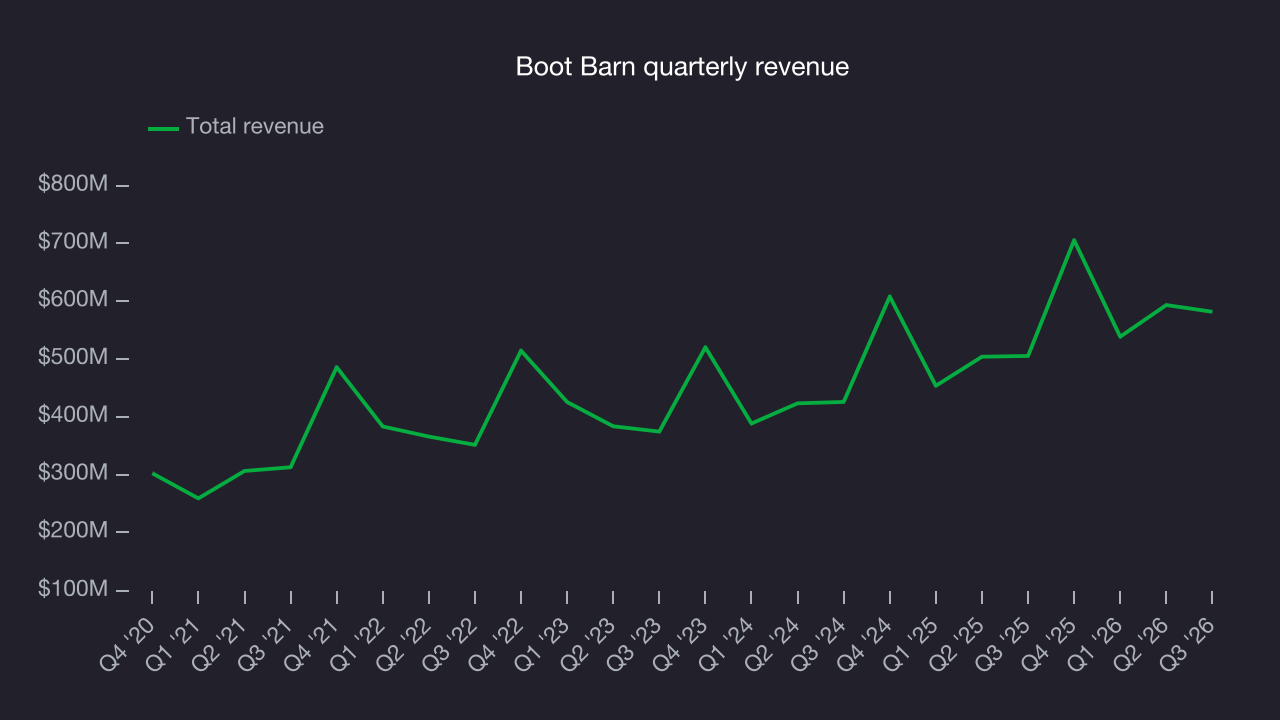
This quarter, Boot Barn’s year-on-year revenue growth was 15.1%, and its $581.8 million of revenue was in line with Wall Street’s consensus estimates. Company management is currently guiding for a 12.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 13.7% over the next 12 months, according to S&P, similar to its three-year rate. This strong projection indicates its newer products will spur better revenue performance.
Store performance
Number of stores
A retailer’s store count often determines how much revenue it can generate.
Boot Barn operated 584 locations in the latest quarter. It has opened new stores at a rapid pace over the last two years, averaging 16.7% annual growth, much faster than the broader consumer retail sector. This gives it a chance to scale into a mid-sized business over time.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provide a deeper understanding of this issue because they measure organic growth at brick-and-mortar shops open for at least a year.
Boot Barn has been one of the most successful retailers over the last two years thanks to strong demand within its existing locations. On average, the company has posted year-on-year same-store sales growth of 6.3%. This performance along with its meaningful buildout of new stores suggests it’s pursuing an aggressive growth strategy.
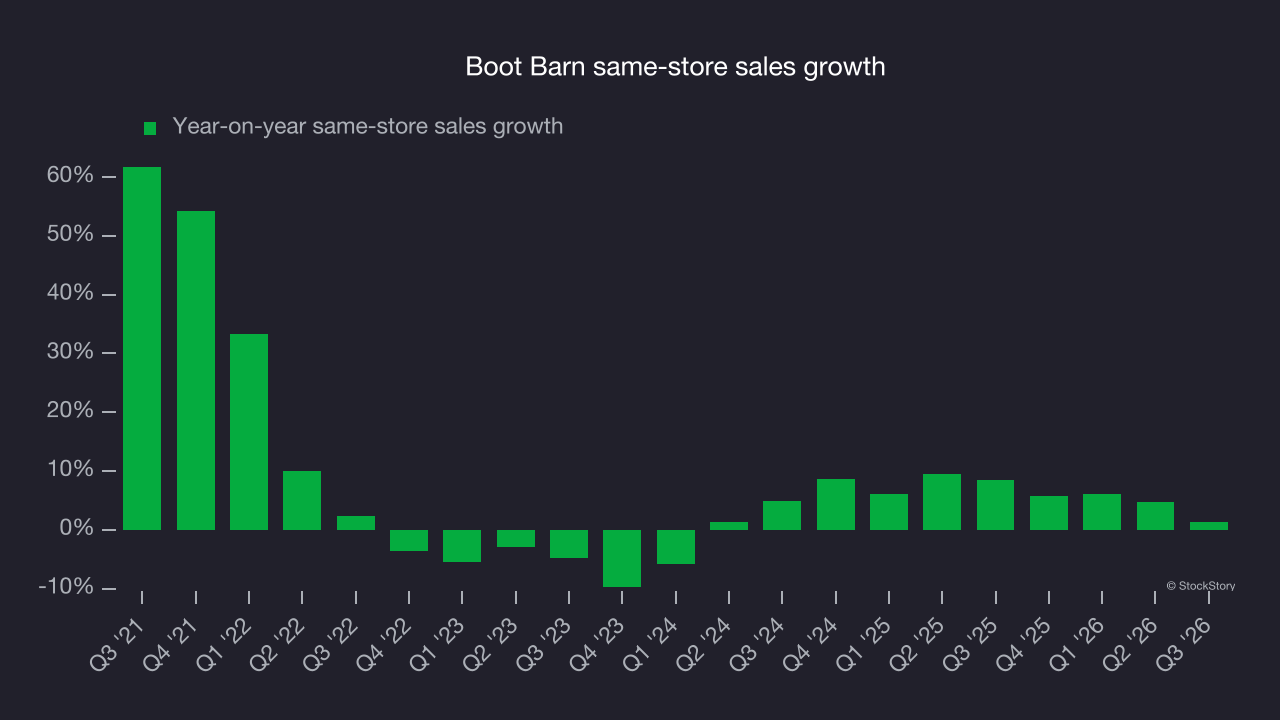
In the latest quarter, Boot Barn’s same-store sales rose 1.4% year on year. This was a meaningful deceleration from its historical levels. The question now is whether Boot Barn can reaccelerate growth.
Key takeaways from Boot Barn’s Q3 results
Boot Barn’s outlook made this a weaker quarter: Next-quarter EPS and revenue guidance both fell short of Wall Street’s consensus estimates. The current results offered some positives, with gross margin beating analysts’ consensus expectations and EPS also topping Wall Street’s consensus estimates. Shares fell 2.5% to $110.50 immediately after the results.
Boot Barn may have had a tough quarter, but that alone does not determine whether the stock is worth buying now. The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Boot Barn, read the full research report here (it’s free).