What a fantastic six months it’s been for Progyny. Shares of the company have skyrocketed 51.1%, hitting $27.77. This performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Progyny, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why is Progyny not exciting?
We’re happy investors have made money, but we’re passing on Progyny for now. Here are three reasons you should be careful with PGNY, plus one stock we’d rather own.
1. Weak sales volumes indicate waning demand
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful health insurance providers company because there’s a ceiling to what customers will pay.
Progyny’s units sold came in at 16,998 in the latest quarter, and over the last two years, averaged 3.8% year-on-year growth. This performance slightly lagged the sector and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 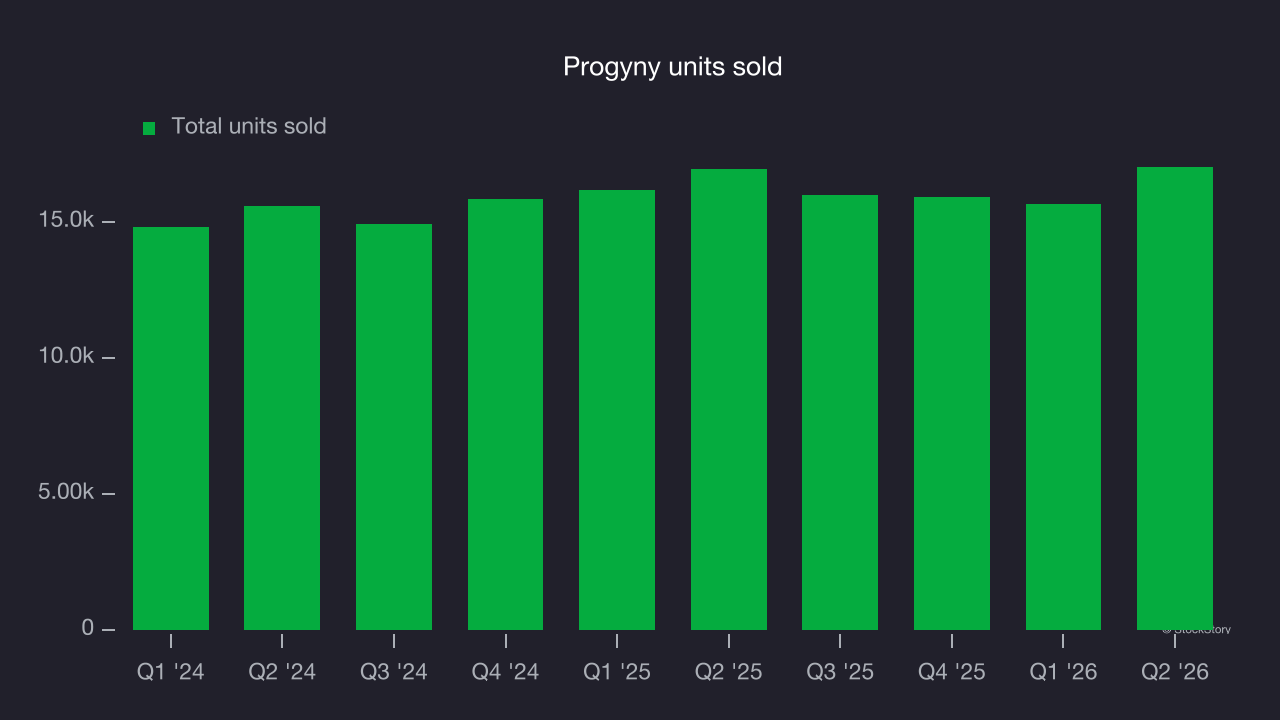
2. Fewer distribution channels limit its ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $1.31 billion in revenue over the past 12 months, Progyny is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
3. Adjusted operating margin in limbo
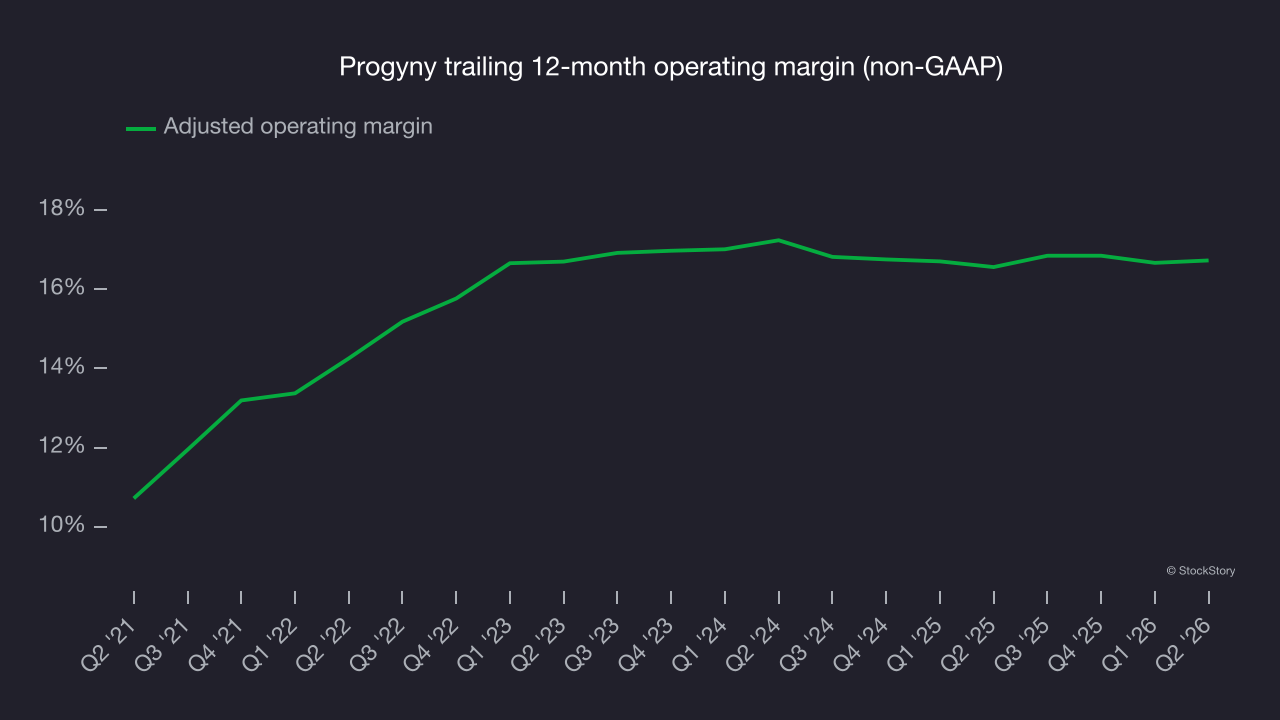
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
Analyzing the trend in its profitability, Progyny’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 16.7%.
Final judgment
Progyny’s business quality ultimately falls short of our standards. After the recent rally, the stock trades at 12.9× forward P/E (or $27.77 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d suggest looking at the most entrenched endpoint security platform on the market.
Stocks we like more than Progyny
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.