What a fantastic six months it’s been for Agilent. Shares of the company have skyrocketed 54.6%, hitting $177.58. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Agilent, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Agilent not exciting?
We’re glad investors have benefited from the price increase, but we’re sitting this one out for now. Here are three reasons why there are better opportunities than A, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
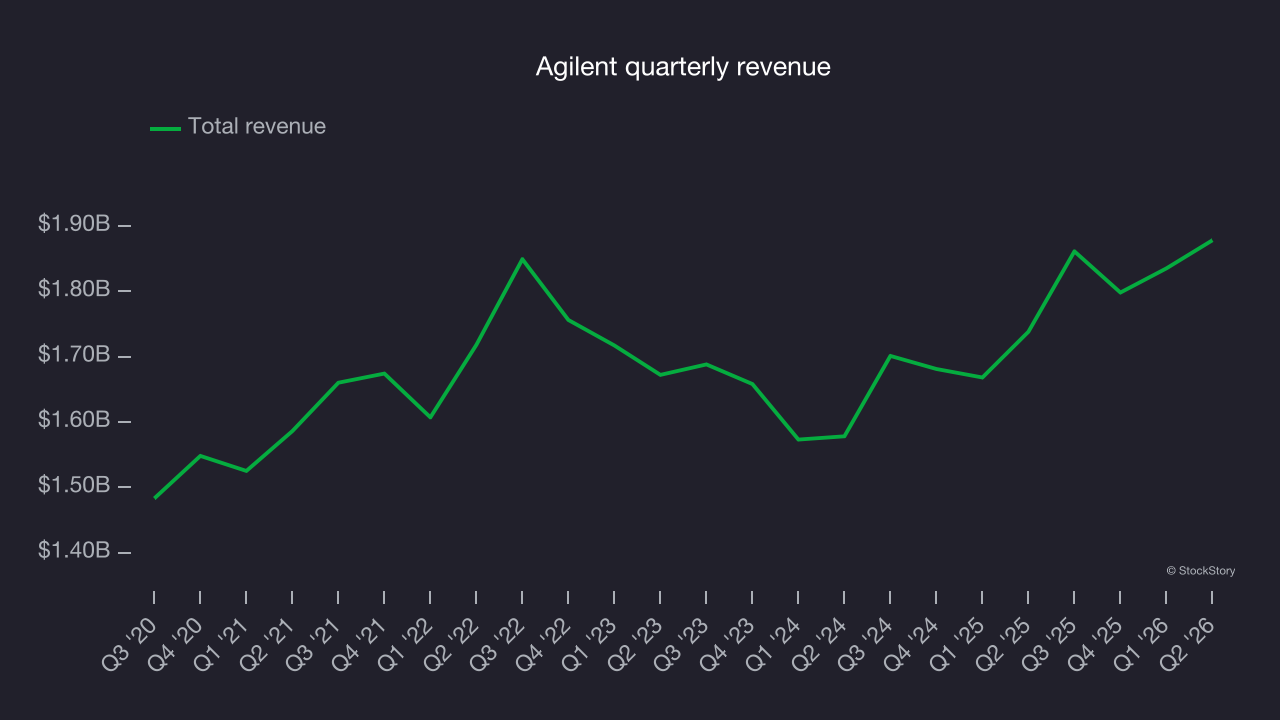
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Agilent grew its sales at a tepid 3.7% compounded annual growth rate. This was below our standard for the healthcare sector.
2. Slow organic growth suggests waning demand in core business
In addition to reported revenue, organic revenue is a useful data point for analyzing research tools & consumables companies. This metric gives visibility into Agilent’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Agilent’s organic revenue averaged 4.4% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 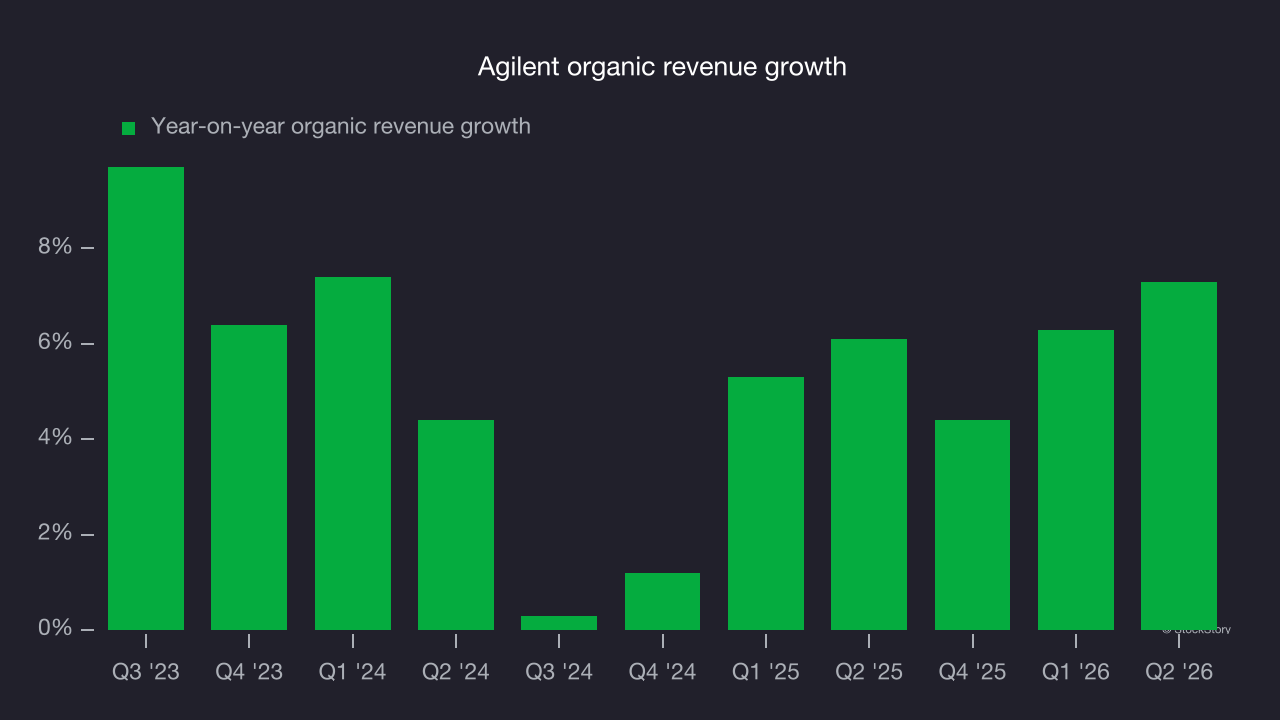
3. New investments fail to bear fruit as ROIC declines
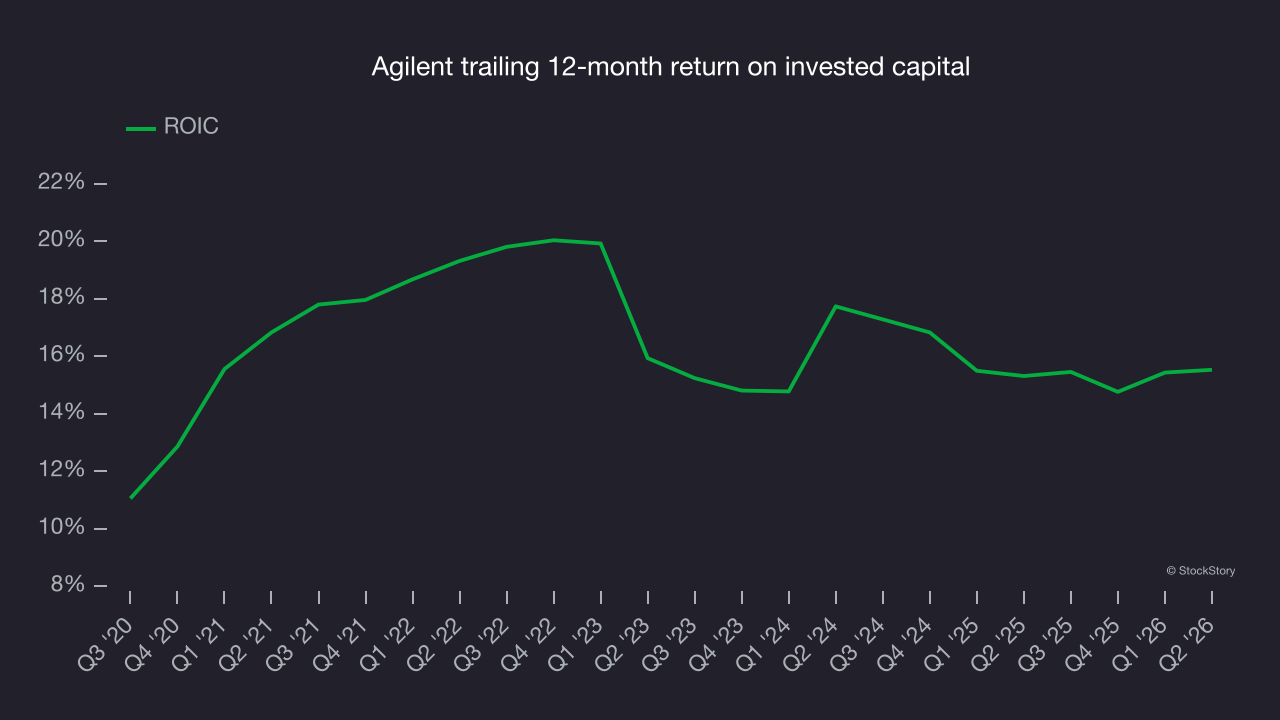
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
On average, Agilent’s ROIC decreased by 2.2 percentage points annually each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
Agilent isn’t a terrible business, but it isn’t one of our picks. After the recent surge, the stock trades at 26.8× forward P/E (or $177.58 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward one of our all-time favorite software stocks.
Stocks we like more than Agilent
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.