Electricity generation and hydrogen production company Bloom Energy (NYSE: BE) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 138% year on year to $1.24 billion. The company’s full-year revenue guidance of $4.5 billion at the midpoint came in 9.1% above analysts’ estimates. Its non-GAAP profit of $0.94 per share was 39.8% above analysts’ consensus estimates.
Is now the time to buy Bloom Energy? Find out by accessing our full research report, it’s free.
Bloom Energy (BE) Q3 2026 highlights:
- Revenue: $1.24 billion vs analyst estimates of $1.08 billion (138% year-on-year growth, 14.6% beat)
- Adjusted EPS: $0.94 vs analyst estimates of $0.67 (39.8% beat)
- Adjusted EBITDA: $299.5 million vs analyst estimates of $238.6 million (24.2% margin, 25.5% beat)
- The company lifted its revenue guidance for the full year to $4.5 billion at the midpoint from $4.05 billion, a 11.1% increase
- Management raised its full-year Adjusted EPS guidance to $3.25 at the midpoint, a 20.4% increase
- Operating Margin: 18.2%, up from 1.5% in the same quarter last year
- Free Cash Flow was -$180.6 million, down from $7.37 million in the same quarter last year
- Market Capitalization: $70.25 billion
KR Sridhar, Founder, Chairman and Chief Executive Officer of Bloom Energy, said, “Electricity is the foundation of economic growth, human well-being and national competitiveness. Today, the world is moving from a century-old model of centralized power to a new architecture that includes firm, distributed onsite generation. Bloom is leading that transformation. What began with hyperscalers is rapidly moving across market segments because every business needs reliable power to grow. We are building the electricity platform for the digital era: power where it is needed, when it is needed, clean and always on.”
Company overview
Working in stealth mode for eight years, Bloom Energy (NYSE: BE) designs, manufactures, and markets solid oxide fuel cell systems for on-site power generation.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Bloom Energy grew its sales at an incredible 34.2% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers, a great starting point for our analysis.
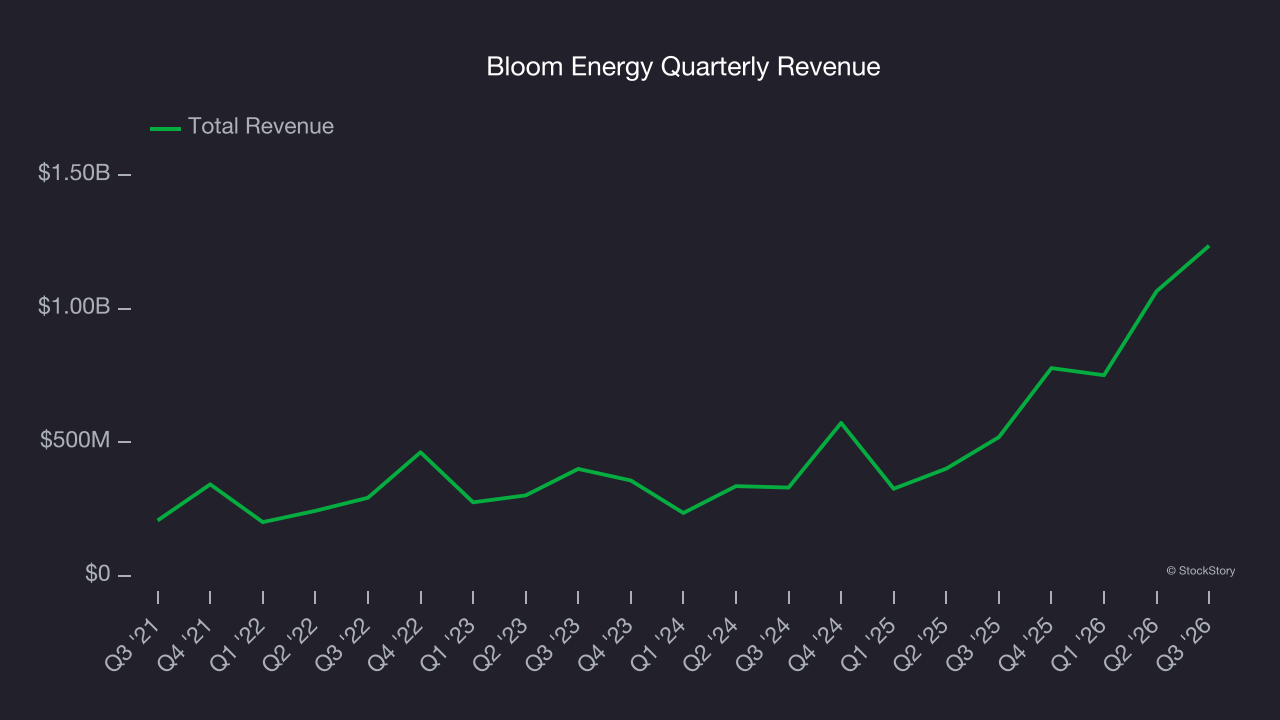
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Bloom Energy’s annualized revenue growth of 74.5% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 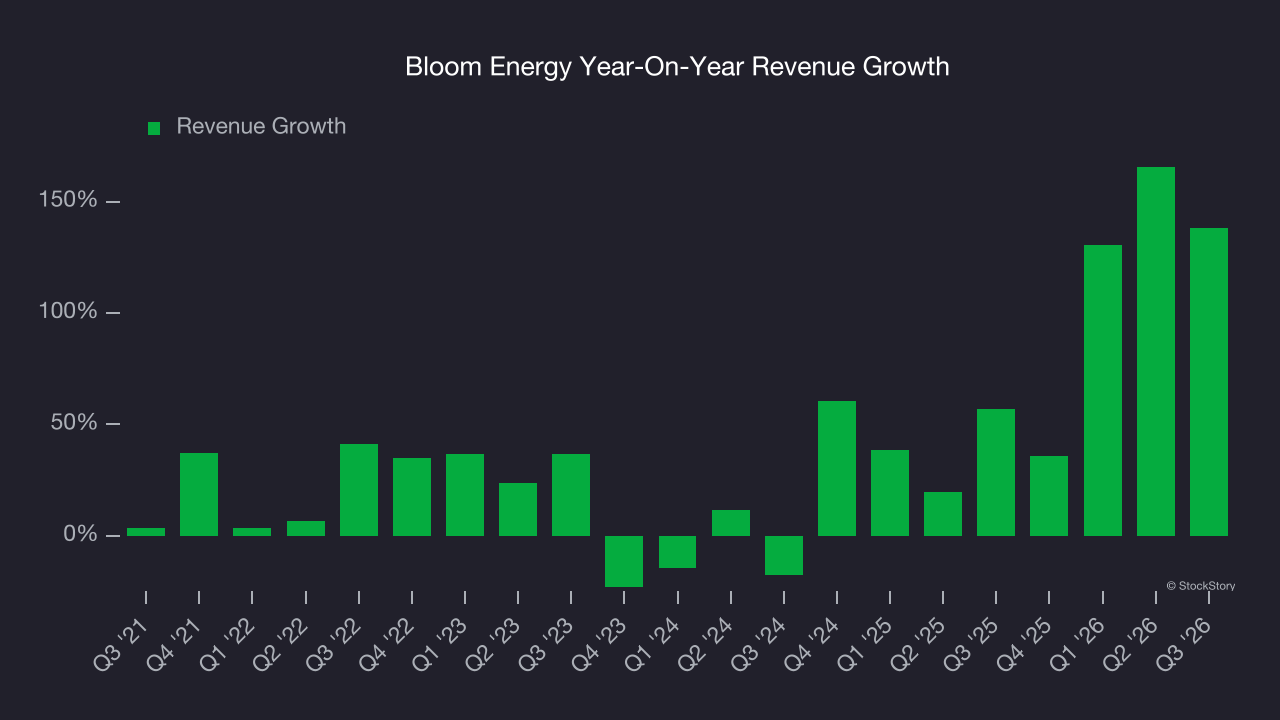
Bloom Energy also breaks out the revenue for its most important segment, Product. Over the last two years, Bloom Energy’s Product revenue (energy servers and electrolyzers) averaged 110% year-on-year growth. This segment has outperformed its total sales during the same period, lifting the company’s performance. 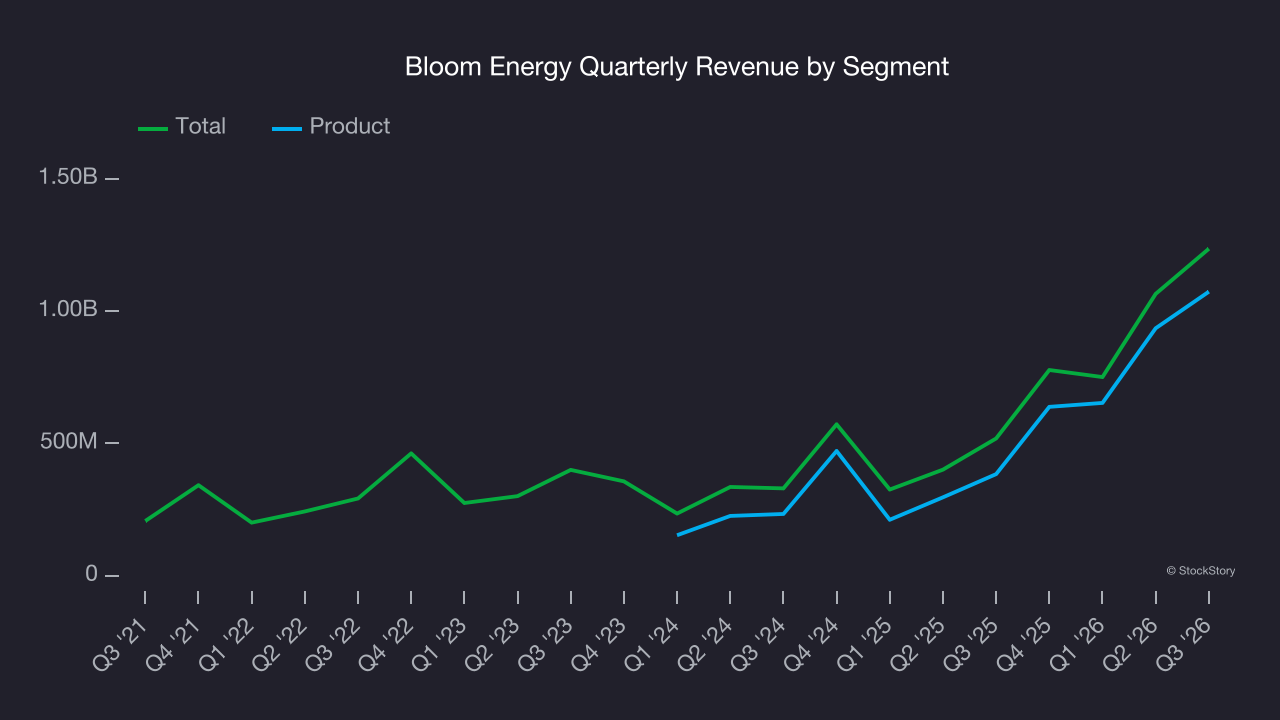
This quarter, Bloom Energy reported magnificent year-on-year revenue growth of 138%, and its $1.24 billion of revenue beat Wall Street’s estimates by 14.6%.
Looking ahead, sell-side analysts expect revenue to grow 59.1% over the next 12 months, a deceleration versus the last two years. Despite the slowdown, this projection is healthy and implies the market sees success for its products and services.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating margin
Bloom Energy was roughly breakeven when averaging the last five years of quarterly operating profits, inadequate for an industrials business. This result isn’t too surprising given its low gross margin as a starting point.
On the plus side, Bloom Energy’s operating margin rose by 36.5 percentage points over the last five years, as its sales growth gave it immense operating leverage.
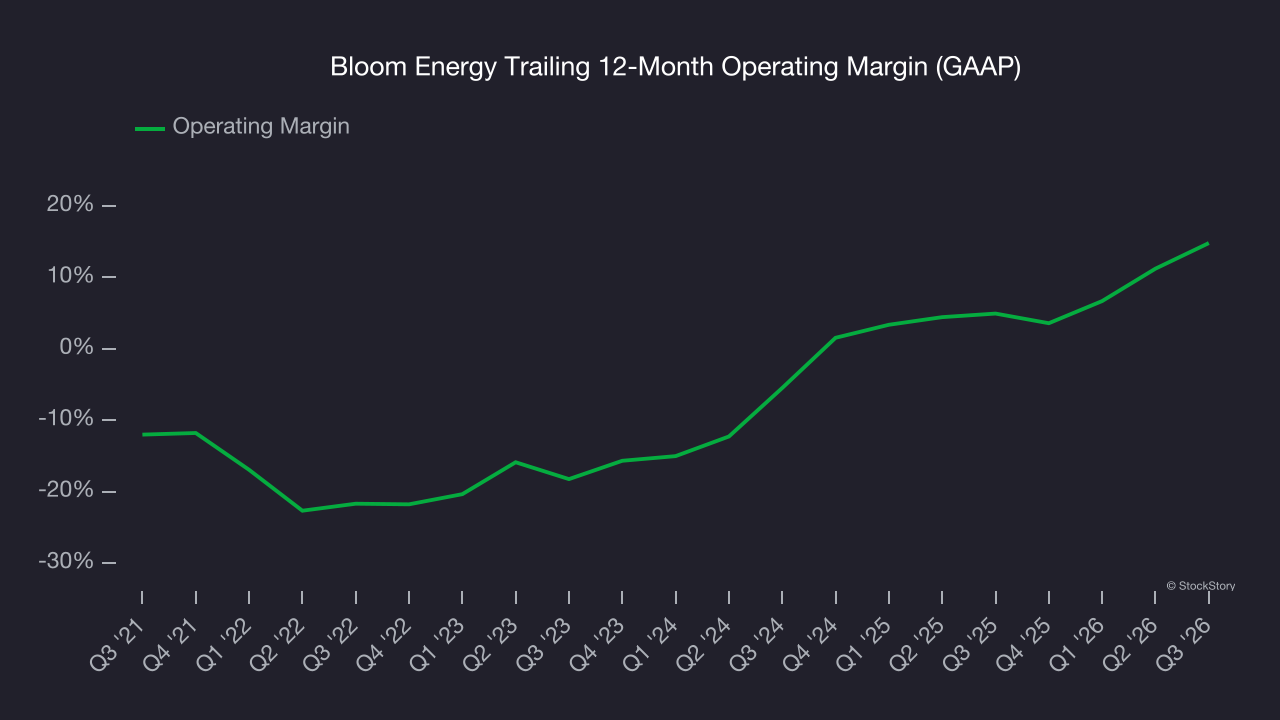
This quarter, Bloom Energy generated an operating margin profit margin of 18.2%, up 16.7 percentage points year on year. The increase was solid, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Bloom Energy’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
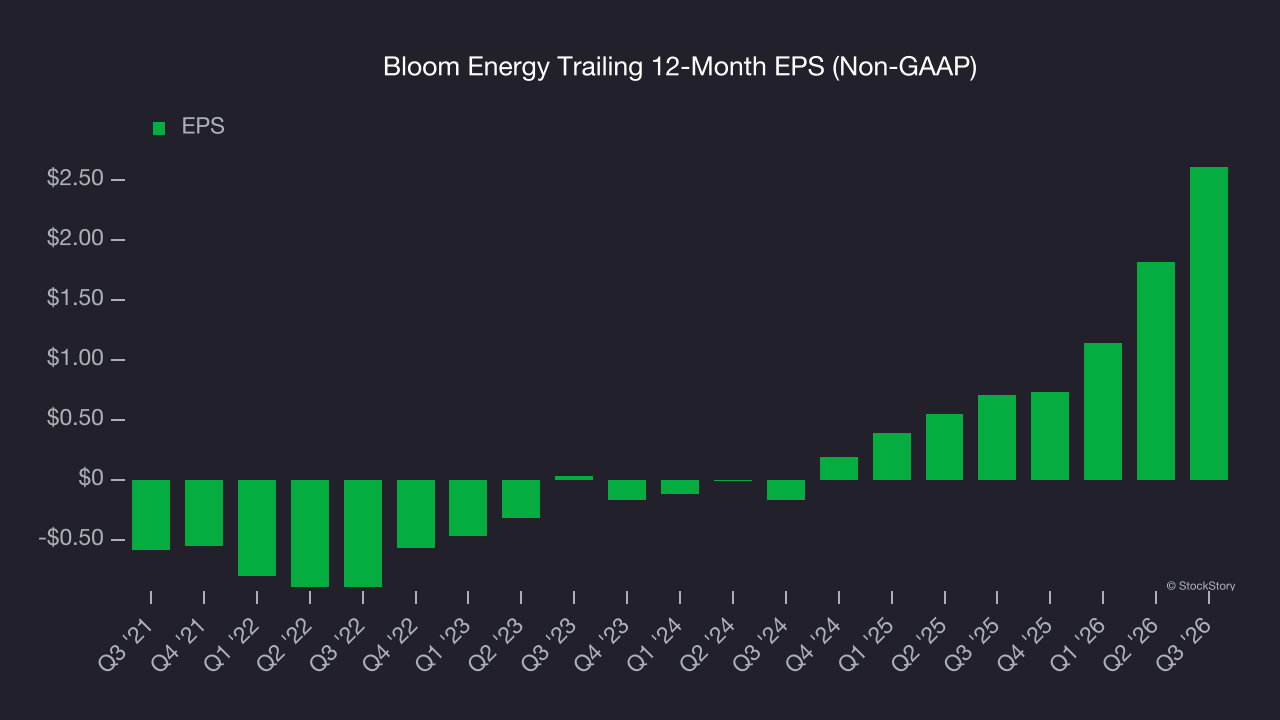
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Bloom Energy, its two-year annual EPS growth of 317% was higher than its five-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, Bloom Energy reported adjusted EPS of $0.94, up from $0.15 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Bloom Energy’s full-year EPS to grow 61.5% from $2.61 to $4.22.
Key takeaways from Bloom Energy’s Q3 results
It was good to see Bloom Energy beat analysts’ EPS expectations this quarter. We were also excited its EBITDA outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The market seemed to be hoping for more, and the stock traded down 2.6% to $213.14 immediately after reporting.
Should you buy the stock or not? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).