Equipment rental company United Rentals (NYSE: URI) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 15.7% year on year to $4.89 billion. The company’s full-year revenue guidance of $18.1 billion at the midpoint came in 1.9% above analysts’ estimates. Its non-GAAP profit of $15.55 per share was 10.8% above analysts’ consensus estimates.
Is now the time to buy United Rentals? Find out by accessing our full research report, it’s free.
United Rentals (URI) Q3 2026 highlights:
- Revenue: $4.89 billion vs analyst estimates of $4.69 billion (15.7% year-on-year growth, 4.4% beat)
- Adjusted EPS: $15.55 vs analyst estimates of $14.03 (10.8% beat)
- Adjusted EBITDA: $2.33 billion vs analyst estimates of $2.17 billion (47.6% margin, 7.4% beat)
- The company lifted its revenue guidance for the full year to $18.1 billion at the midpoint from $17.65 billion, a 2.5% increase
- EBITDA guidance for the full year is $8.35 billion at the midpoint, above analyst estimates of $8.07 billion
- Operating Margin: 28.8%, up from 26.3% in the same quarter last year
- Free Cash Flow was $272 million, up from -$365 million in the same quarter last year
- Market Capitalization: $64.97 billion
Matthew Flannery, chief executive officer of United Rentals, said, “I’m very pleased with our third-quarter results, which are a testament to our strategy, our team’s dedication to our customers, and the unmatched breadth and scale of our premier offering. We continued to lean into growth across both our general rentals and specialty businesses with the momentum from the first half of the year carrying through the quarter.”
Company overview
Owning the largest rental fleet in the world, United Rentals (NYSE: URI) provides equipment rental and related services to construction, industrial, and infrastructure industries.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Luckily, United Rentals’s sales grew at an exceptional 13.7% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
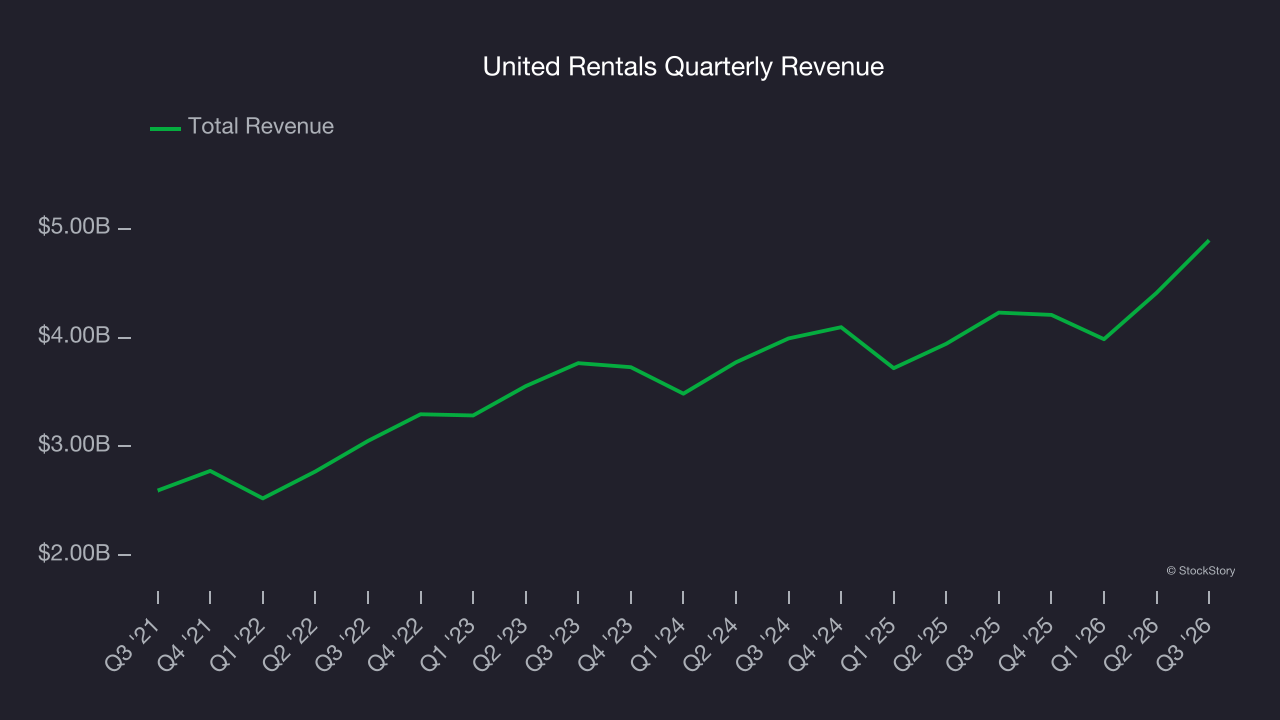
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. United Rentals’s annualized revenue growth of 8.1% over the last two years is below its five-year trend, but we still think the results were respectable. 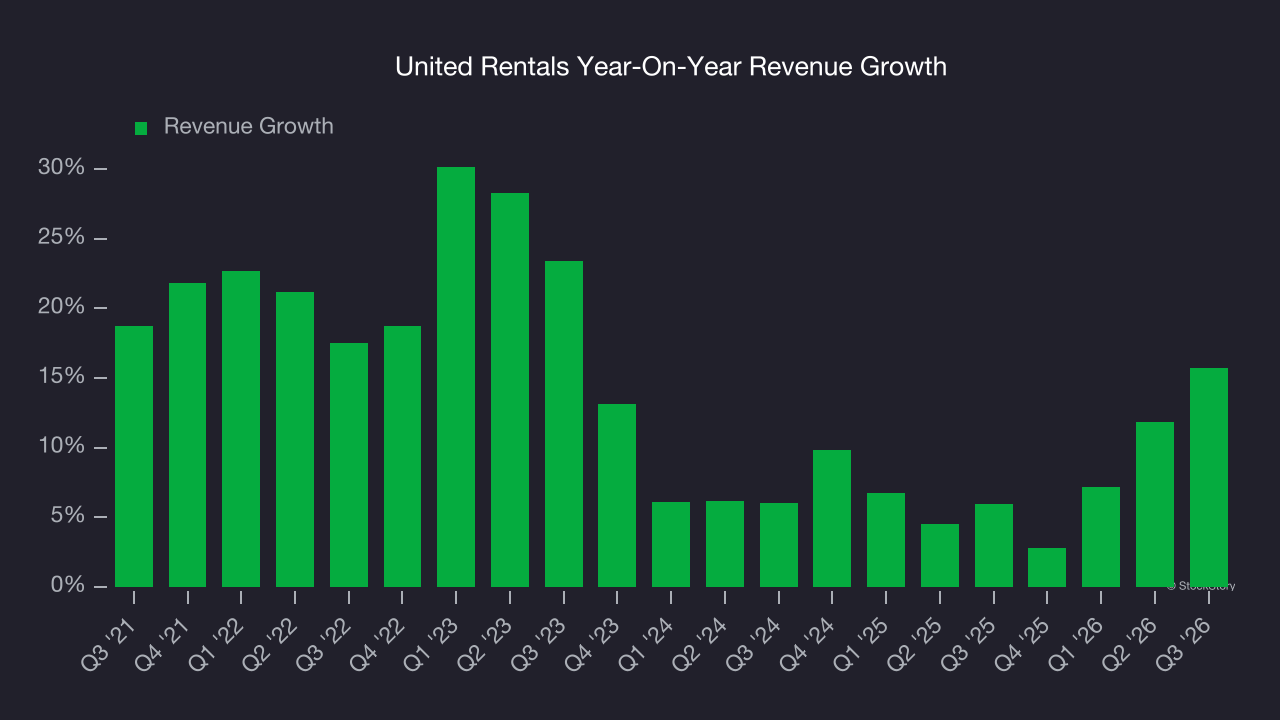
This quarter, United Rentals reported year-on-year revenue growth of 15.7%, and its $4.89 billion of revenue exceeded Wall Street’s estimates by 4.4%.
Looking ahead, sell-side analysts expect revenue to grow 7.8% over the next 12 months, similar to its two-year rate. This projection is above the sector average and implies its newer products and services will help maintain its recent top-line performance.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
United Rentals has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 26.2%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Looking at the trend in its profitability, United Rentals’s operating margin decreased by 1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
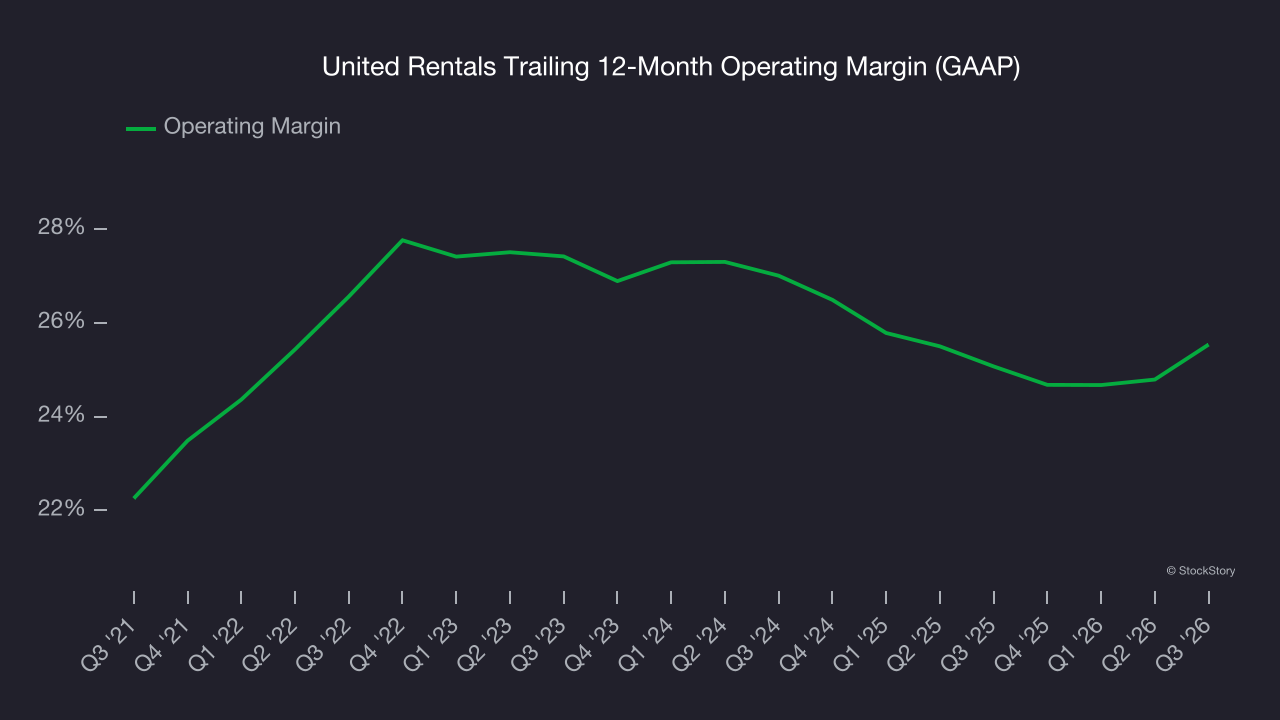
In Q3, United Rentals generated an operating margin profit margin of 28.8%, up 2.5 percentage points year on year. The increase was encouraging, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
United Rentals’s EPS grew at 20% compounded annual growth rate over the last five years, higher than its 13.7% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
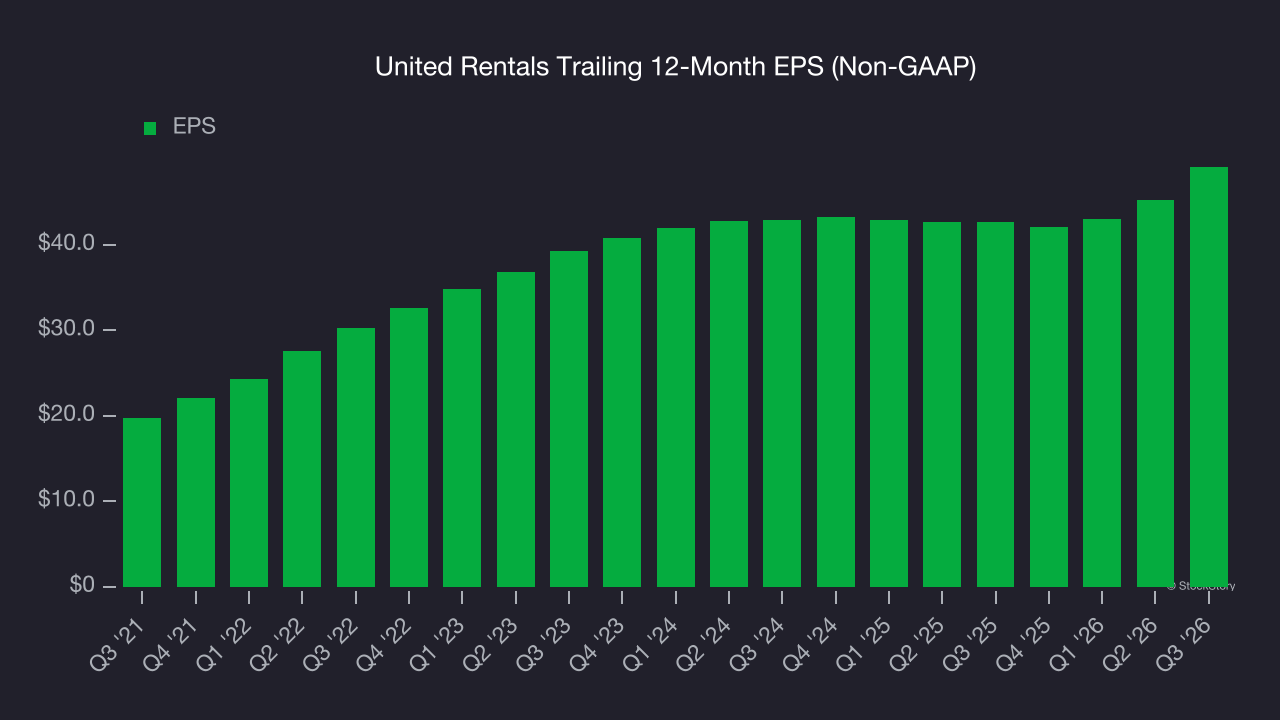
Diving into United Rentals’s quality of earnings can give us a better understanding of its performance. A five-year view shows that United Rentals has repurchased its stock, shrinking its share count by 14.3%. This tells us its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 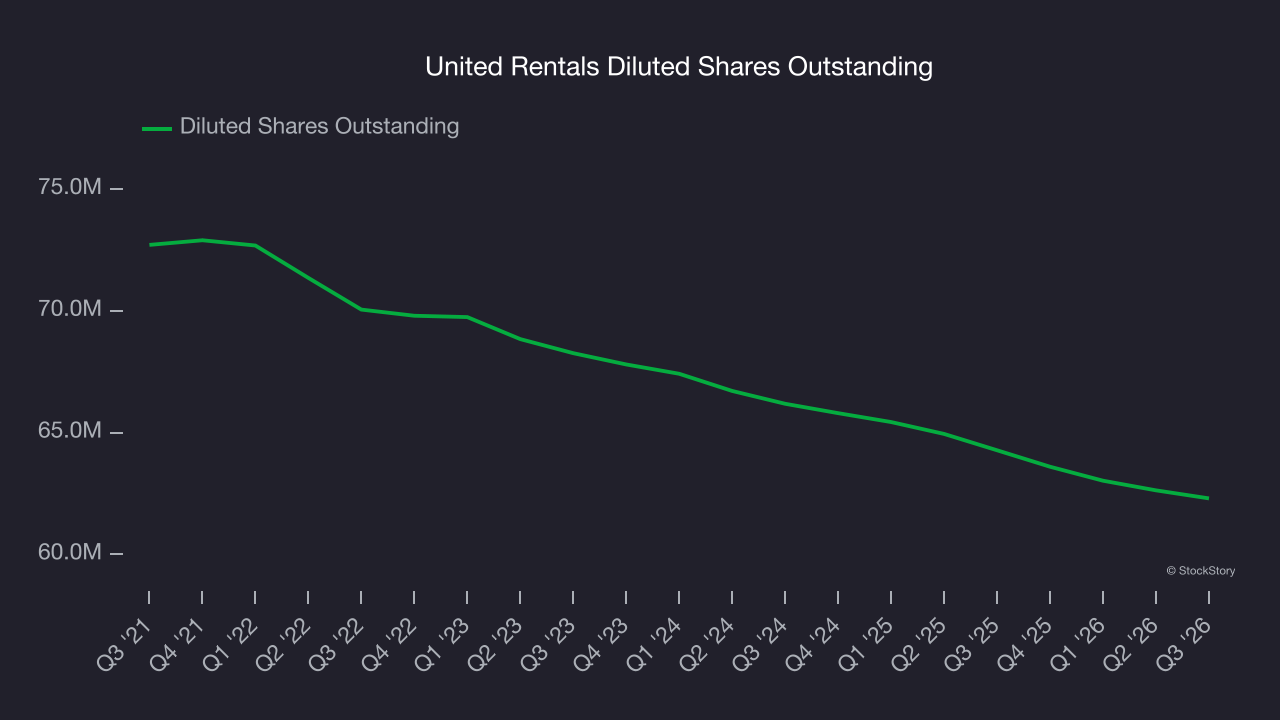
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For United Rentals, its two-year annual EPS growth of 7% was lower than its five-year trend. This wasn’t great, but at least the company was successful in other measures of financial health.
In Q3, United Rentals reported adjusted EPS of $15.55, up from $11.70 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects United Rentals’s full-year EPS to grow 12.3% from $49.11 to $55.17.
Key takeaways from United Rentals’s Q3 results
We were impressed by how significantly United Rentals blew past analysts’ revenue expectations this quarter. We were also glad its full-year EBITDA guidance trumped Wall Street’s estimates. Zooming out, we think this was a solid print. The stock remained flat at $1,082 immediately following the results.
Sure, United Rentals had a solid quarter, but if we look at the bigger picture, is this stock a buy? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).