Clinical research company Medpace Holdings (NASDAQ: MEDP) met Wall Street’s revenue expectations in Q3 2026, with sales up 8.5% year on year to $716 million. The company’s outlook for the full year was close to analysts’ estimates with revenue guided to $2.85 billion at the midpoint. Its GAAP profit of $4.84 per share was 9.3% above analysts’ consensus estimates.
Is now the time to buy Medpace? Find out by accessing our full research report, it’s free.
Medpace (MEDP) Q3 2026 highlights:
- Revenue: $716 million vs analyst estimates of $713.7 million (8.5% year-on-year growth, in line)
- EPS (GAAP): $4.84 vs analyst estimates of $4.43 (9.3% beat)
- Adjusted EBITDA: $172.1 million vs analyst estimates of $159.4 million (24% margin, 8% beat)
- The company reconfirmed its revenue guidance for the full year of $2.85 billion at the midpoint
- EPS (GAAP) guidance for the full year is $18.15 at the midpoint, beating analyst estimates by 3.2%
- EBITDA guidance for the full year is $645 million at the midpoint, above analyst estimates of $627.6 million
- Operating Margin: 23.1%, up from 21.5% in the same quarter last year
- Free Cash Flow Margin: 27.4%, down from 35.7% in the same quarter last year
- Market Capitalization: $17.37 billion
Company overview
Founded in 1992 as a scientifically-driven alternative to traditional contract research organizations, Medpace (NASDAQ: MEDP) provides outsourced clinical trial management and research services to help pharmaceutical, biotechnology, and medical device companies develop new treatments.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Thankfully, Medpace’s 21% annualized revenue growth over the last five years was excellent. Its growth beat the average healthcare company and shows its offerings resonate with customers, a helpful starting point for our analysis.
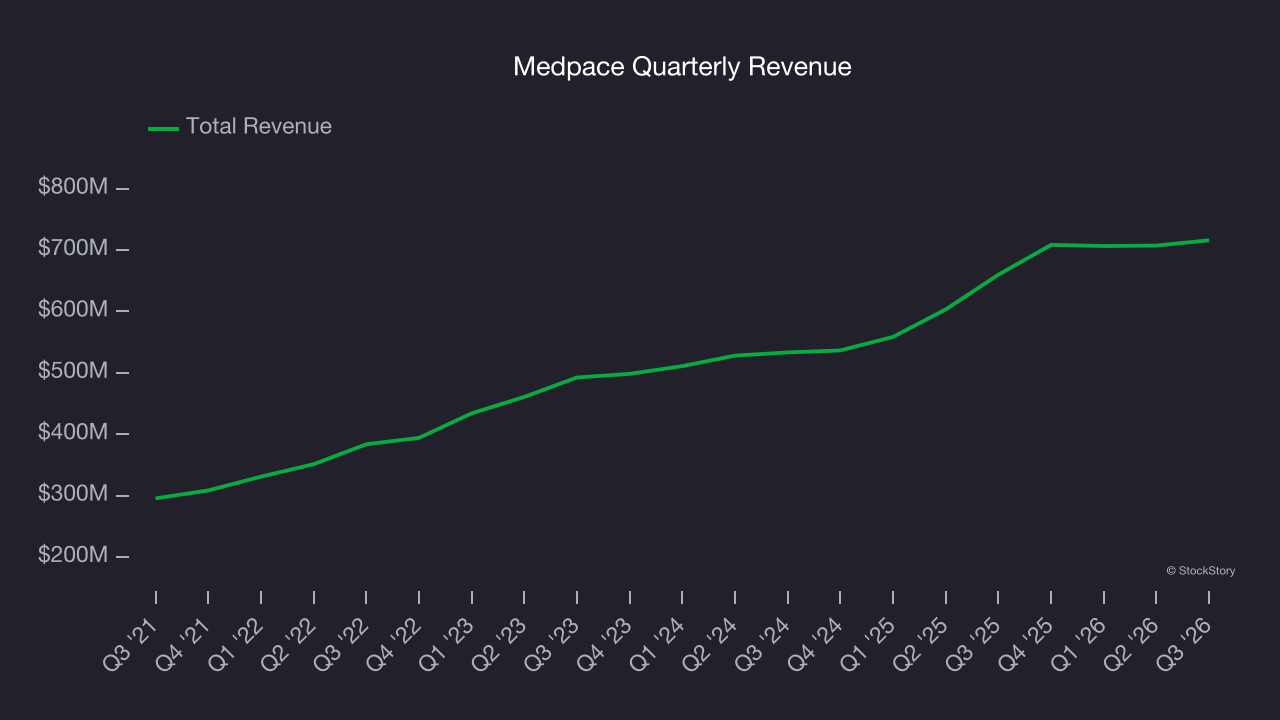
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Medpace’s annualized revenue growth of 17.1% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 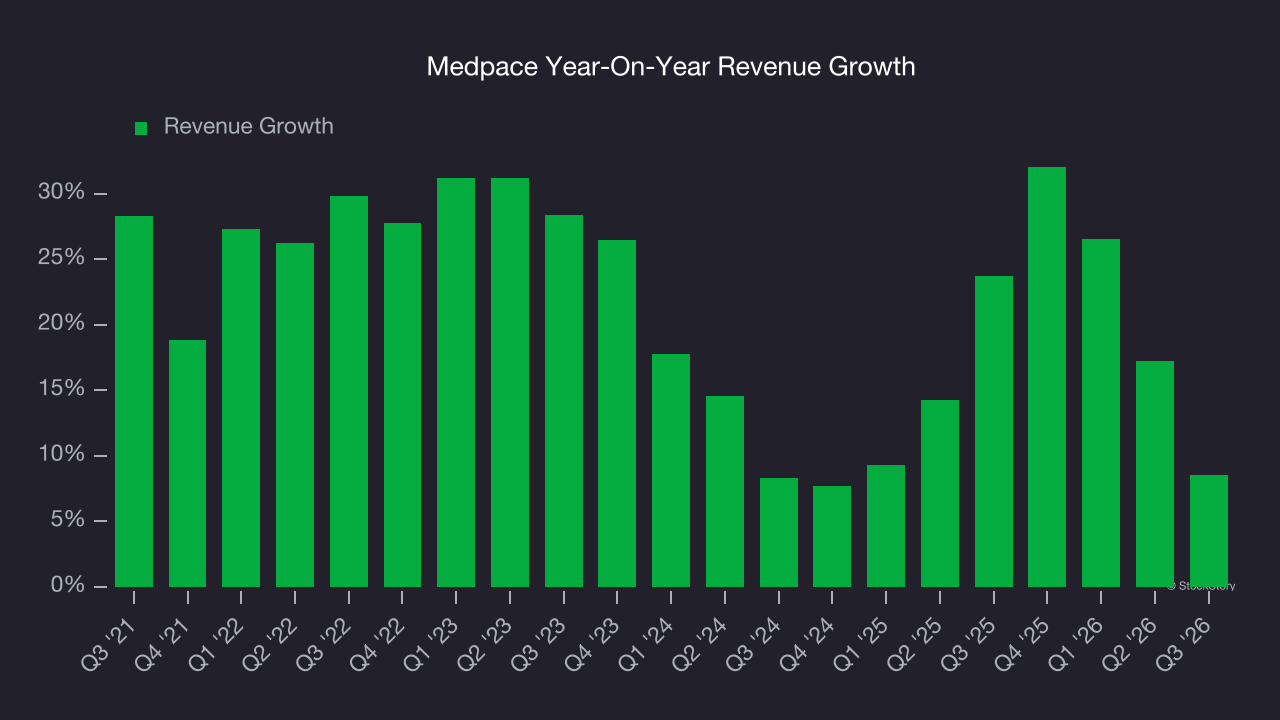
This quarter, Medpace grew its revenue by 8.5% year on year, and its $716 million of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.8% over the next 12 months, a deceleration versus the last two years. This projection doesn’t excite us and indicates its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted operating margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes, and interest on debt - metrics less connected to business fundamentals.
Medpace has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, boasting an average adjusted operating margin of 20.7%.
Analyzing the trend in its profitability, Medpace’s adjusted operating margin rose by 2.5 percentage points over the last five years, as its sales growth gave it operating leverage. The company’s two-year trajectory shows its performance was mostly driven by its recent improvements. These data points are very encouraging and show momentum is on its side.
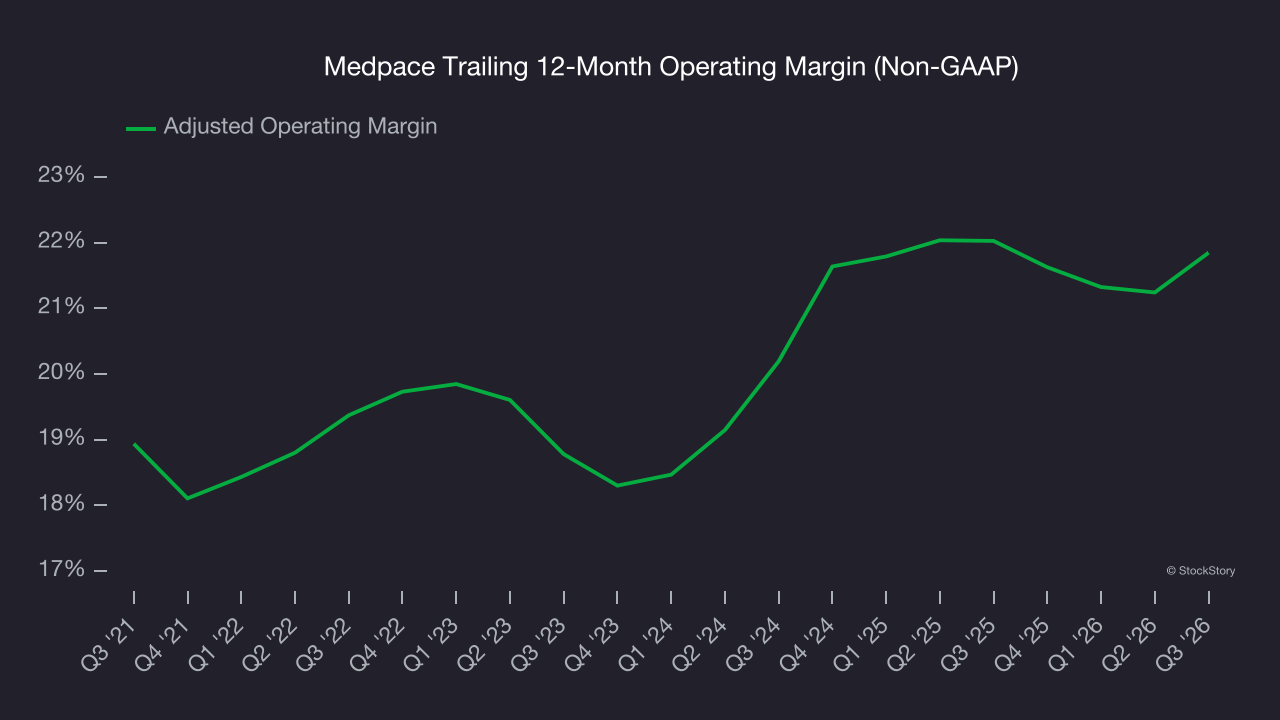
In Q3, Medpace generated an adjusted operating margin profit margin of 24.2%, up 2.3 percentage points year on year. This increase was a welcome development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Medpace’s EPS grew at 30% compounded annual growth rate over the last five years, higher than its 21% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
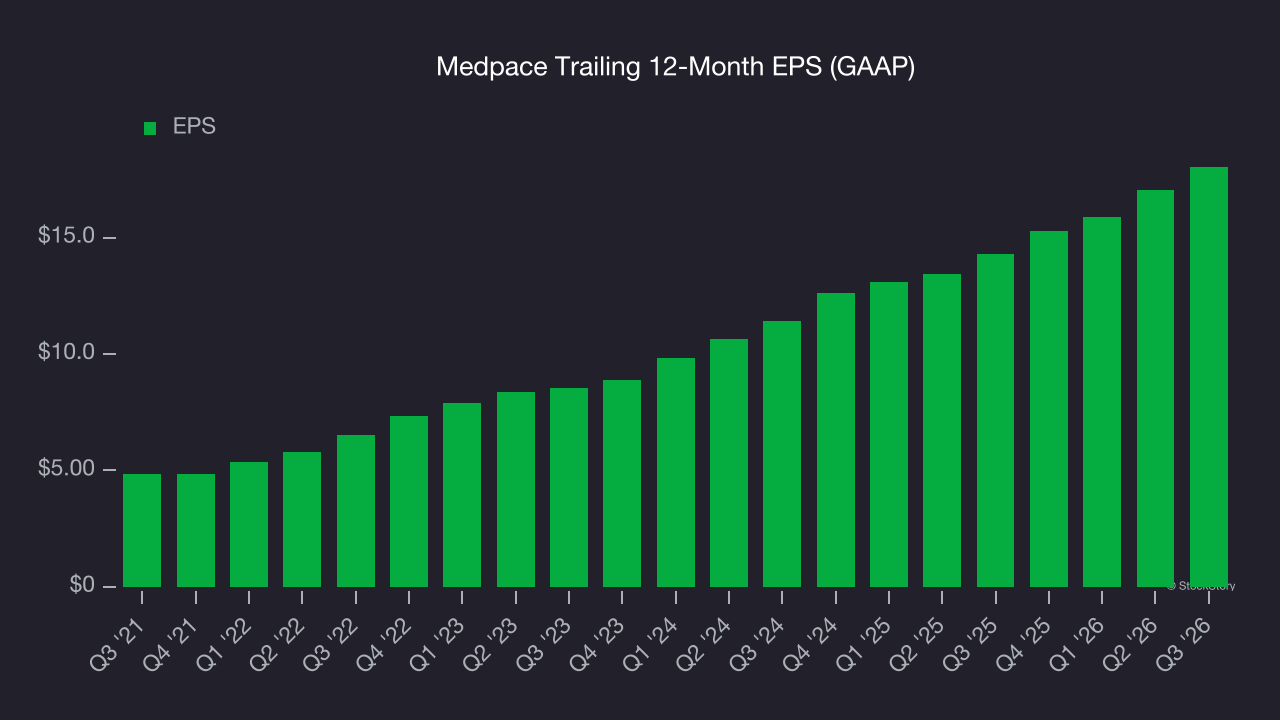
Diving into Medpace’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Medpace’s adjusted operating margin expanded by 2.5 percentage points over the last five years. On top of that, its share count shrank by 24.4%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 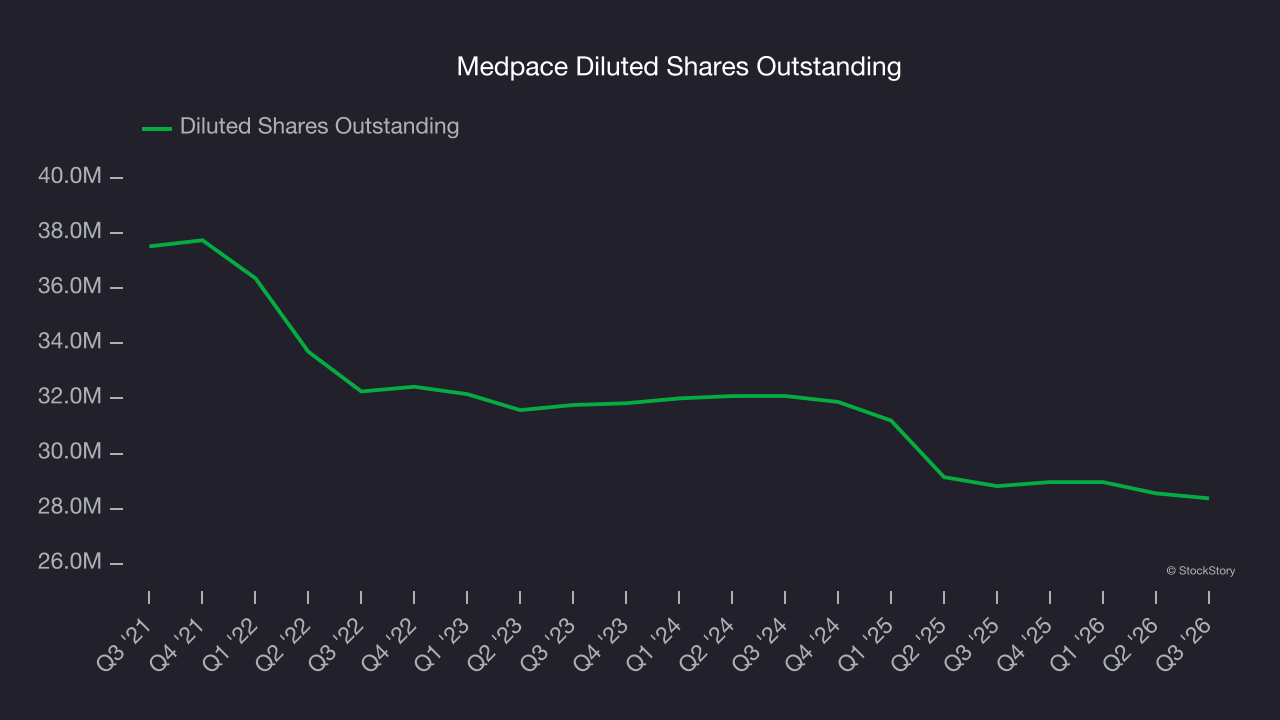
In Q3, Medpace reported EPS of $4.84, up from $3.86 in the same quarter last year. This print beat analysts’ estimates by 9.3%. Over the next 12 months, Wall Street expects Medpace’s full-year EPS to grow 4.1% from $18.03 to $18.76.
Key takeaways from Medpace’s Q3 results
We enjoyed seeing Medpace beat analysts’ full-year EPS guidance expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $657.90 immediately after reporting.
So should you invest in Medpace right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).