Aerospace and defense company Hexcel (NYSE: HXL) missed Wall Street’s revenue expectations in Q3 2026, but sales rose 8.8% year on year to $496.4 million. The company’s full-year revenue guidance of $2.08 billion at the midpoint came in 0.9% below analysts’ estimates. Its non-GAAP profit of $0.50 per share was in line with analysts’ consensus estimates.
Is now the time to buy Hexcel? Find out by accessing our full research report, it’s free.
Hexcel (HXL) Q3 2026 highlights:
- Revenue: $496.4 million vs analyst estimates of $502.8 million (8.8% year-on-year growth, 1.3% miss)
- Adjusted EPS: $0.50 vs analyst estimates of $0.50 (in line)
- The company reconfirmed its revenue guidance for the full year of $2.08 billion at the midpoint
- Management reiterated its full-year Adjusted EPS guidance of $2.35 at the midpoint
- Operating Margin: 11%, up from 7.9% in the same quarter last year
- Free Cash Flow Margin: 10.2%, down from 21.2% in the same quarter last year
- Market Capitalization: $6.91 billion
Chairman, CEO and President Tom Gentile said, “Consistent with what we communicated last quarter, our third quarter financial results reflected our typical summer sales seasonality, which impacted operating leverage. We also experienced near-term cost headwinds from accelerated hiring and training to support the strong demand signals we are receiving across our business for Q4 and 2027. In terms of market demand, commercial aerospace sales increased 21% year-over-year as the industry recovery continues to take hold, partially offset by temporary softness in a few fighter and space programs that impacted Defense, Space & Other sales. We are reaffirming our 2026 guidance and expect full year results to be within the sales and adjusted EPS ranges previously provided.”
Company overview
Founded shortly after World War II by a group of engineers from UC Berkley, Hexcel (NYSE: HXL) manufactures lightweight composite materials primarily for the aerospace and defense sectors.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Hexcel grew its sales at a solid 9.9% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
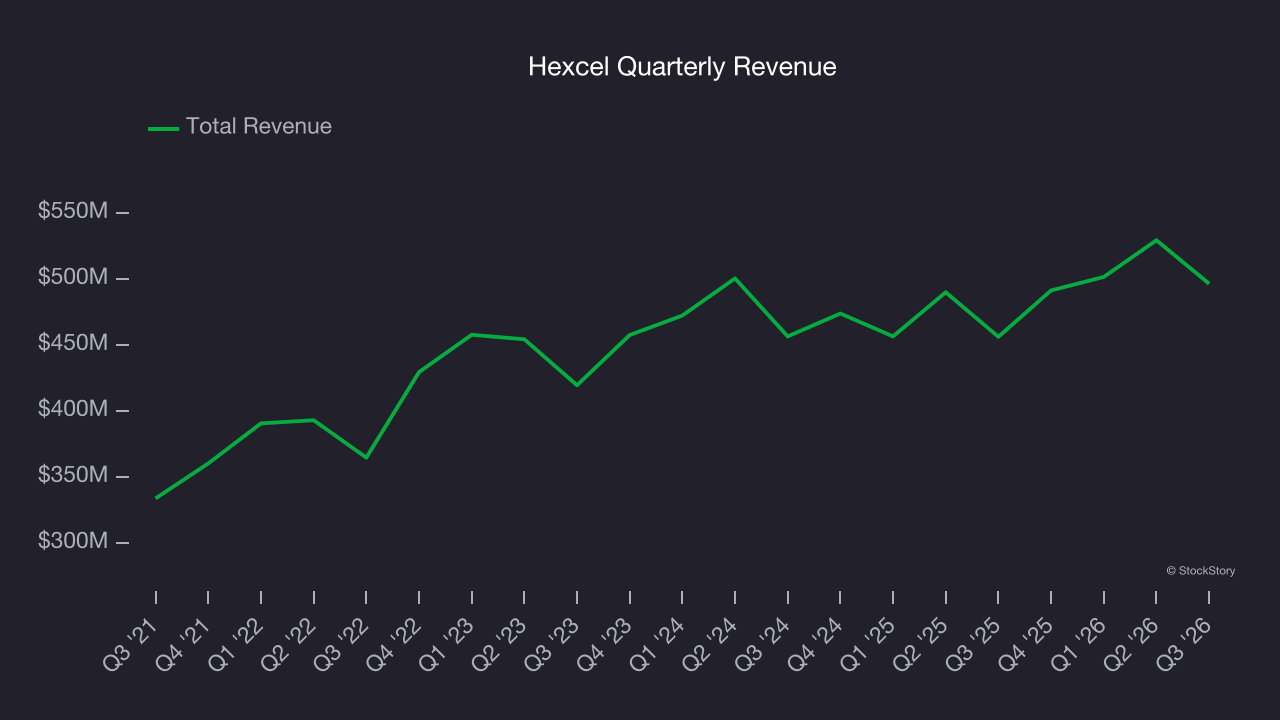
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Hexcel’s recent performance shows its demand has slowed as its annualized revenue growth of 3.4% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 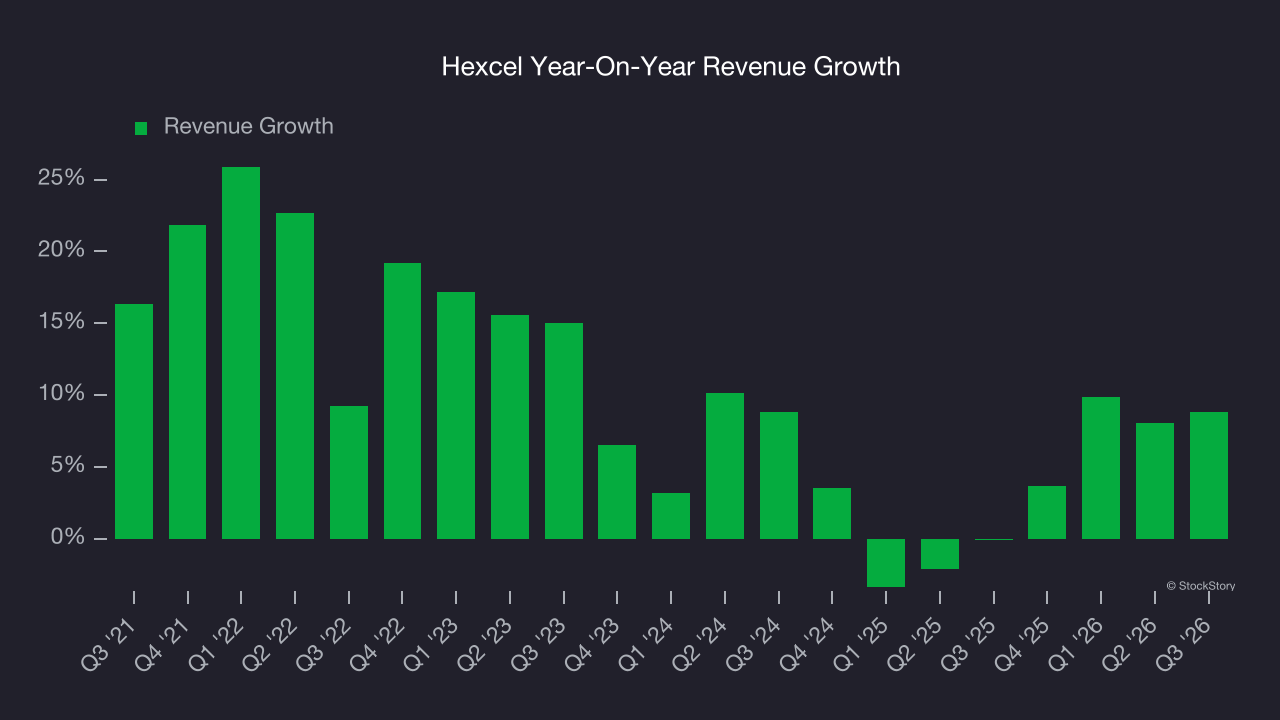
Hexcel also breaks out the revenue for its most important segments, Commercial aerospace and Space & defense, which are 66.5% and 33.5% of revenue. Over the last two years, Hexcel’s Commercial aerospace revenue (customers like Airbus, Boeing) averaged 6.1% year-on-year growth while its Space & defense revenue (government customers) averaged 15.4% growth. 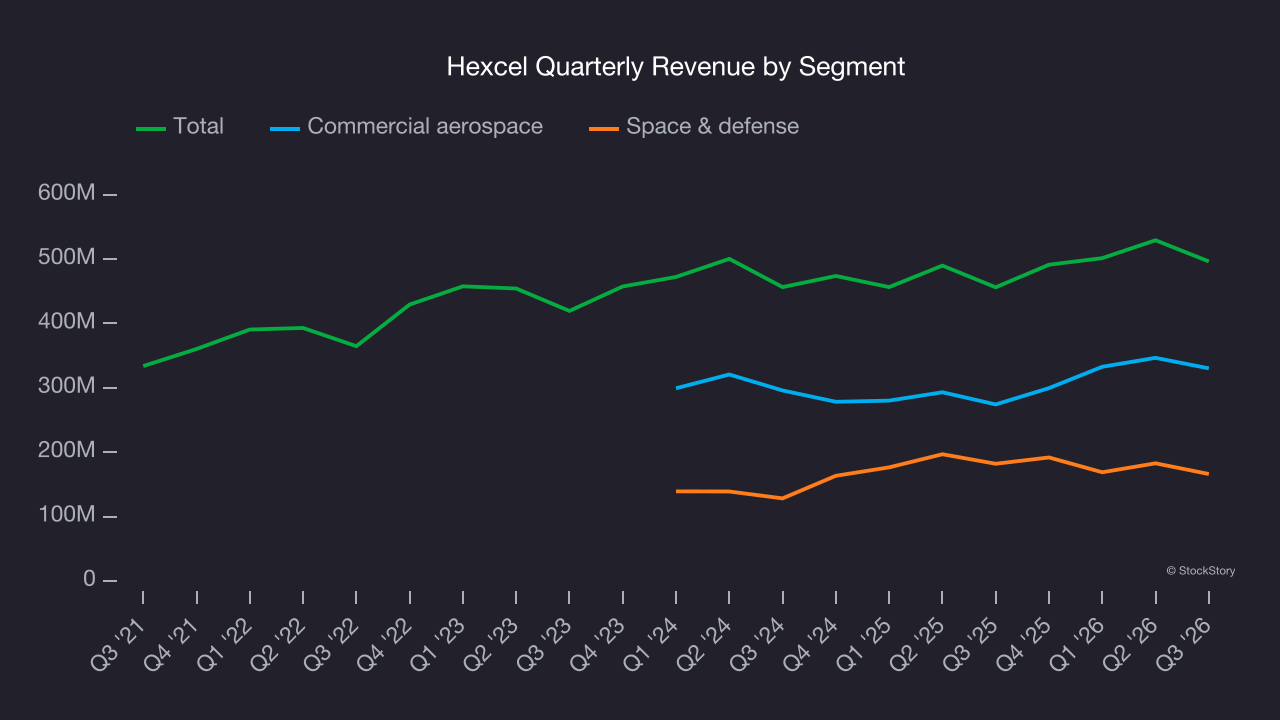
This quarter, Hexcel’s revenue grew by 8.8% year on year to $496.4 million, missing Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 10.7% over the next 12 months, an improvement versus the last two years. This projection is admirable and suggests its newer products and services will spur better top-line performance.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating margin
Hexcel has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 10.6%.
Analyzing the trend in its profitability, Hexcel’s operating margin rose by 1.8 percentage points over the last five years, as its sales growth gave it operating leverage.
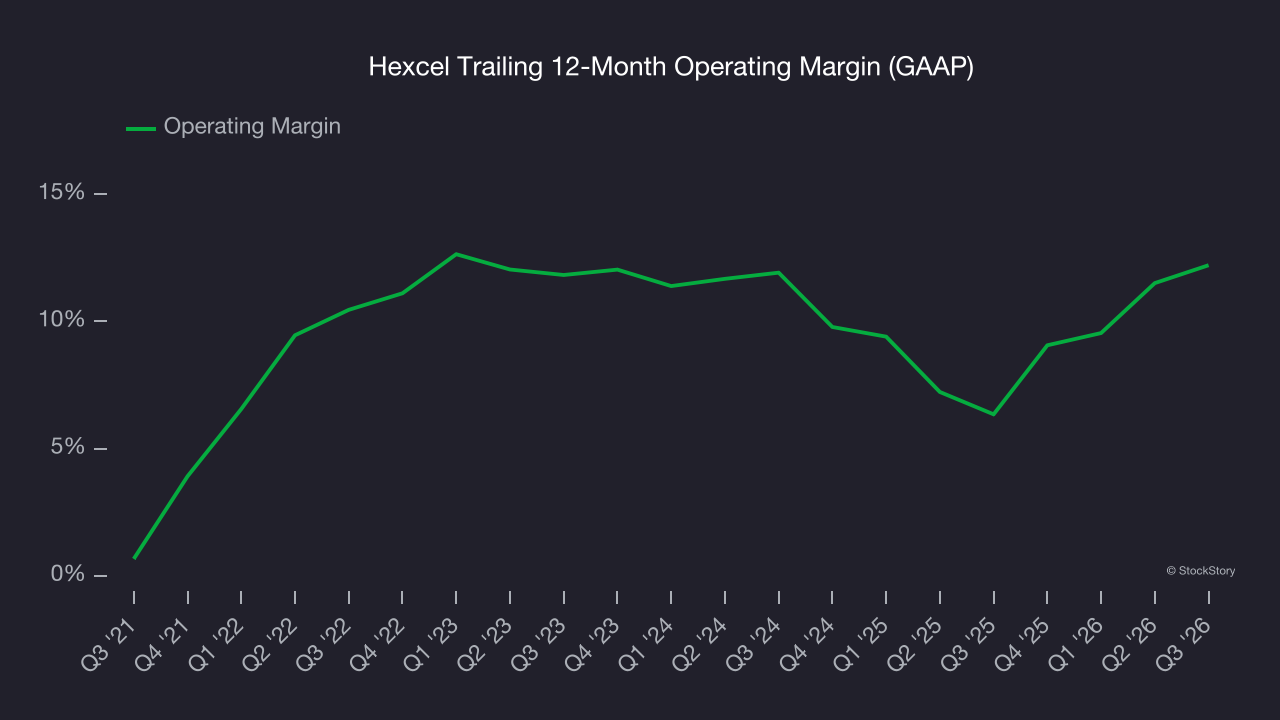
In Q3, Hexcel generated an operating margin profit margin of 11%, up 3.1 percentage points year on year. This increase was a welcome development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Hexcel’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
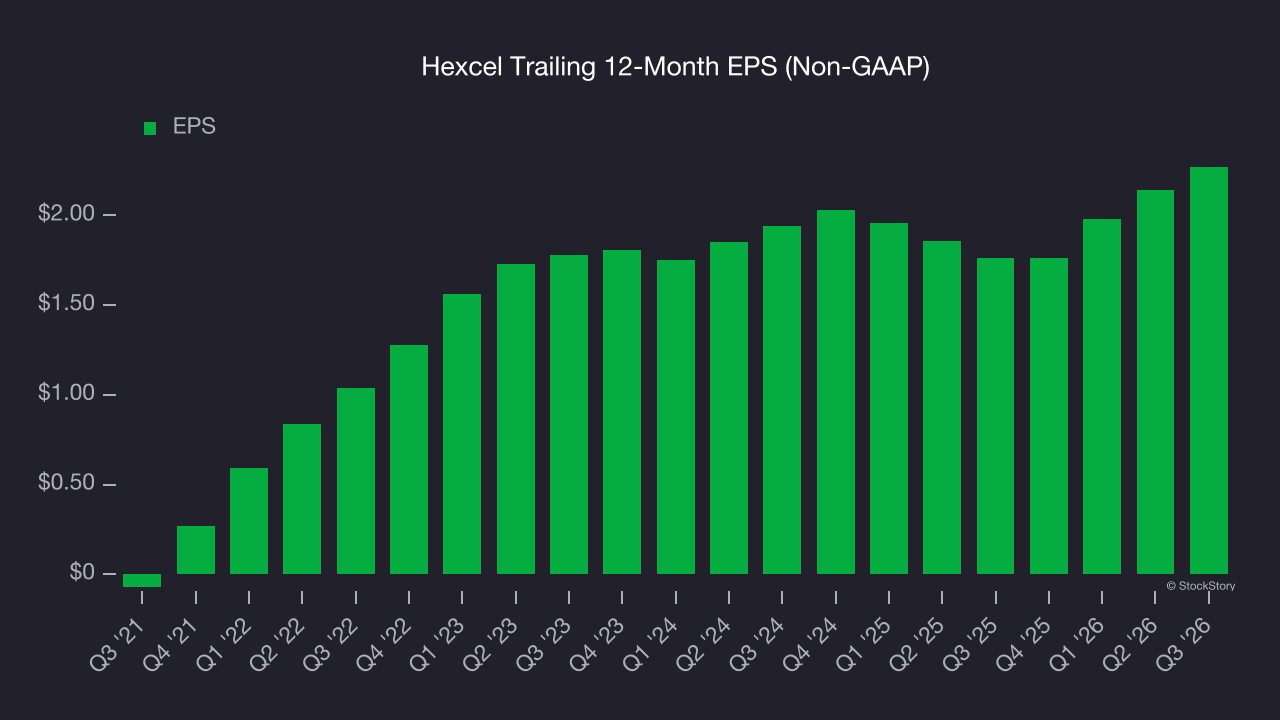
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Hexcel’s EPS grew at a decent 8.2% compounded annual growth rate over the last two years, higher than its 3.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Diving into the nuances of Hexcel’s earnings can give us a better understanding of its performance. A two-year view shows that Hexcel has repurchased its stock, shrinking its share count by 6.6%. This tells us its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 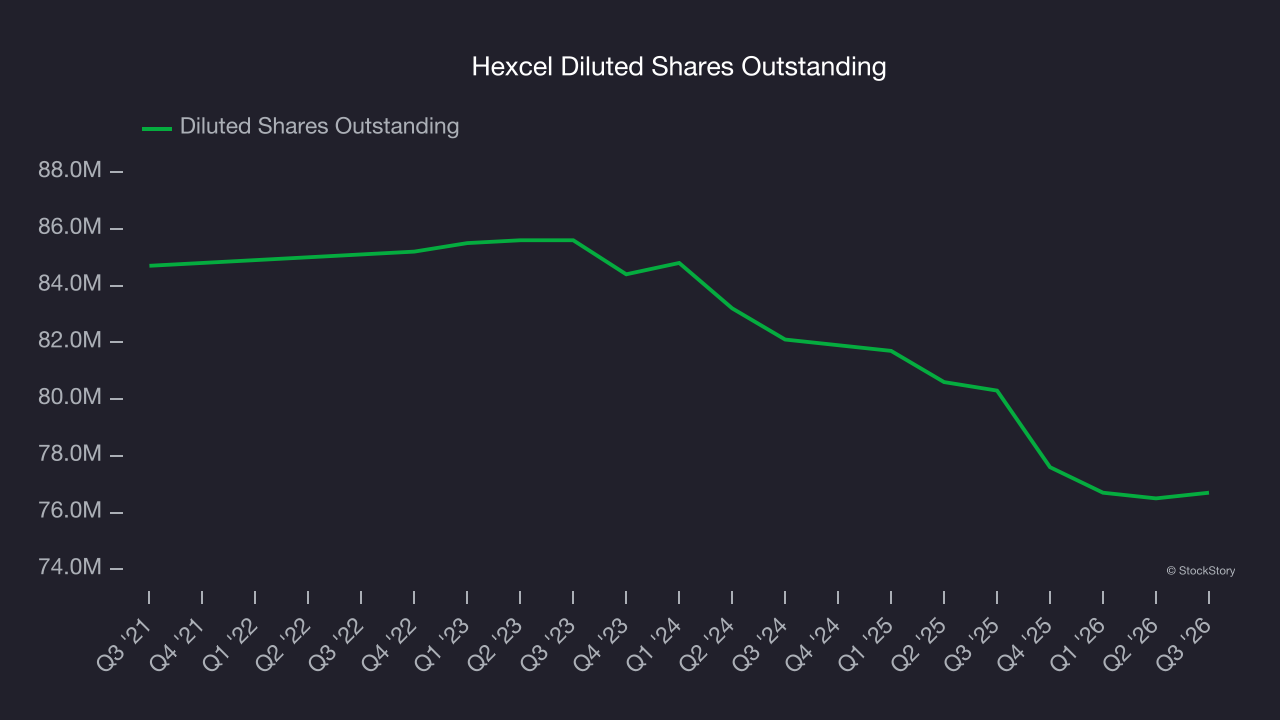
In Q3, Hexcel reported adjusted EPS of $0.50, up from $0.37 in the same quarter last year. This print was close to analysts’ estimates. Over the next 12 months, Wall Street expects Hexcel’s full-year EPS to grow 26.3% from $2.27 to $2.87.
Key takeaways from Hexcel’s Q3 results
We struggled to find many positives in these results. Its full-year EPS guidance missed and its revenue fell slightly short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded down 8.5% to $82.20 immediately following the results.
Hexcel’s earnings report left more to be desired. Let’s look forward to see if this quarter has created an opportunity to buy the stock. If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).