Regional banking company Banner Corporation (NASDAQ: BANR) fell short of the market’s revenue expectations in Q3 2026 as sales rose 3% year on year to $177.3 million. Its non-GAAP profit of $1.51 per share was 3.6% below analysts’ consensus estimates.
Is now the time to buy Banner Bank? Find out by accessing our full research report, it’s free.
Banner Bank (BANR) Q3 2026 highlights:
- Net Interest Income: $161.9 million vs analyst estimates of $165.9 million (7.9% year-on-year growth, 2.4% miss)
- Net Interest Margin: 4.1% vs analyst estimates of 4.2% (in line)
- Revenue: $177.3 million vs analyst estimates of $185 million (3% year-on-year growth, 4.2% miss)
- Efficiency Ratio: 65.3% vs analyst estimates of 59.7% (556.4 basis point miss)
- Adjusted EPS: $1.51 vs analyst expectations of $1.57 (3.6% miss)
- Tangible Book Value per Share: $45.84 vs analyst estimates of $47.14 (2.3% year-on-year growth, 2.8% miss)
- Market Capitalization: $2.32 billion
“Banner’s results for the third quarter reflect the continued strength of our super community bank model, which prioritizes deepening client relationships, maintaining a strong funding base, and delivering exceptional service while upholding a moderate risk profile,” Grescovich continued. “Our earnings for the third quarter of 2026 benefited from loan growth and the completion of the merger with Pacific Financial. These benefits were partially offset by higher non-interest expense, which primarily reflects merger related expenses. Banner continues to build on a foundation of solid credit quality, backed by a well-funded credit loss reserve and a robust capital position that offers both resilience and flexibility for future growth. At the same time, the strategic investments we have made across the organization are delivering tangible results, further positioning Banner for long-term success. We also continue to capitalize on a strong core deposit base, with core deposits representing 90% of total deposits at quarter-end. For more than 136 years, Banner has upheld its core values by consistently doing the right thing for our clients, communities, colleagues, company and shareholders. Our long-standing commitment has enabled us to earn trust, navigate change with confidence and continue building a strong foundation for the future.”
Company overview
Founded in 1890 in Walla Walla, Washington, and evolving through more than a century of economic cycles, Banner Corporation (NASDAQ: BANR) operates Banner Bank, providing commercial banking services, loans, and financial products to individuals and businesses across Washington, Oregon, California, Idaho, and Utah.
Sales growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Regrettably, Banner Bank’s revenue grew at a sluggish 3.2% compounded annual growth rate over the last five years. This was below our standard for the banking sector and is a poor baseline for our analysis.
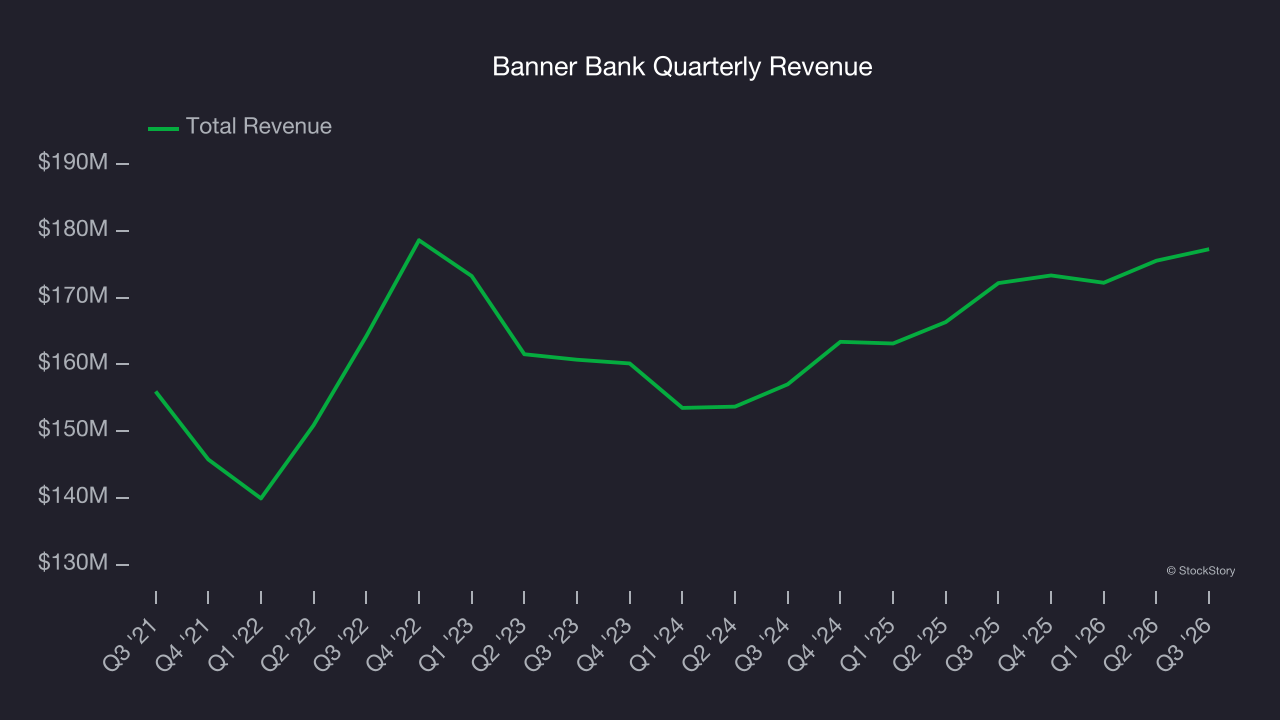
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Banner Bank’s annualized revenue growth of 5.8% over the last two years is above its five-year trend, which is encouraging. 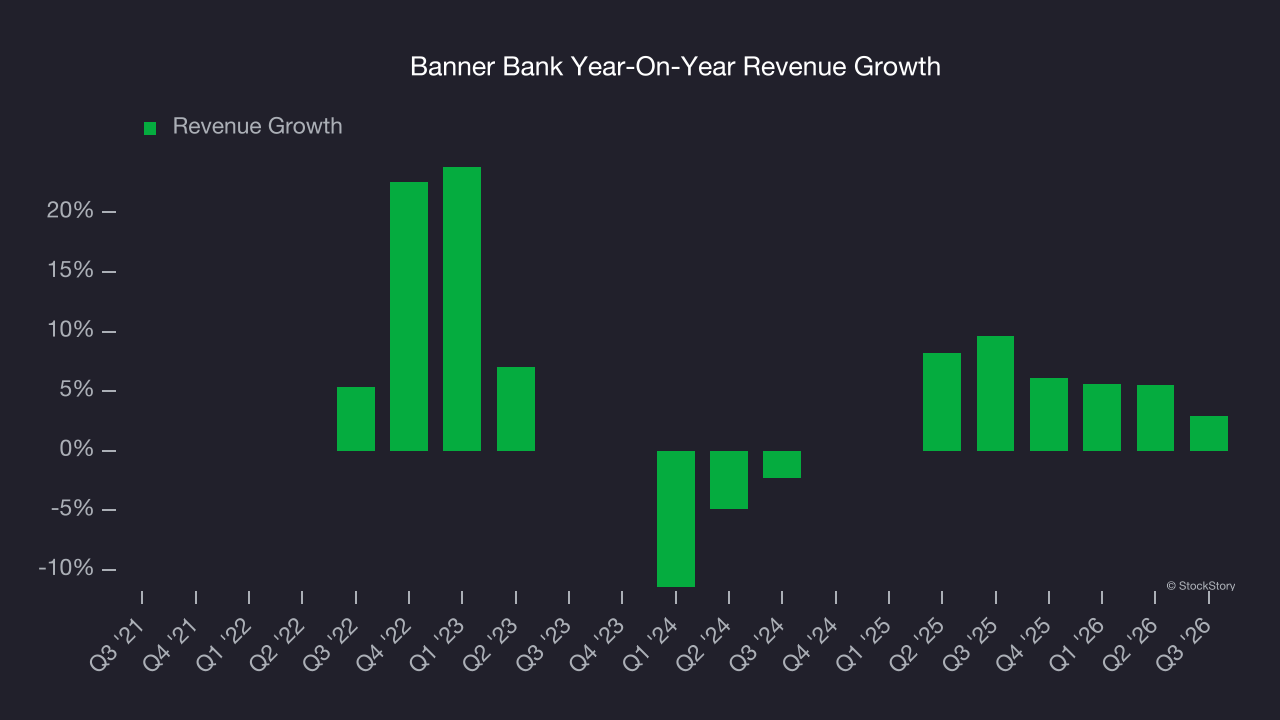 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Banner Bank’s revenue grew by 3% year on year to $177.3 million, falling short of Wall Street’s estimates.
Net interest income made up 87.1% of the company’s total revenue during the last five years, meaning Banner Bank barely relies on non-interest income to drive its overall growth.
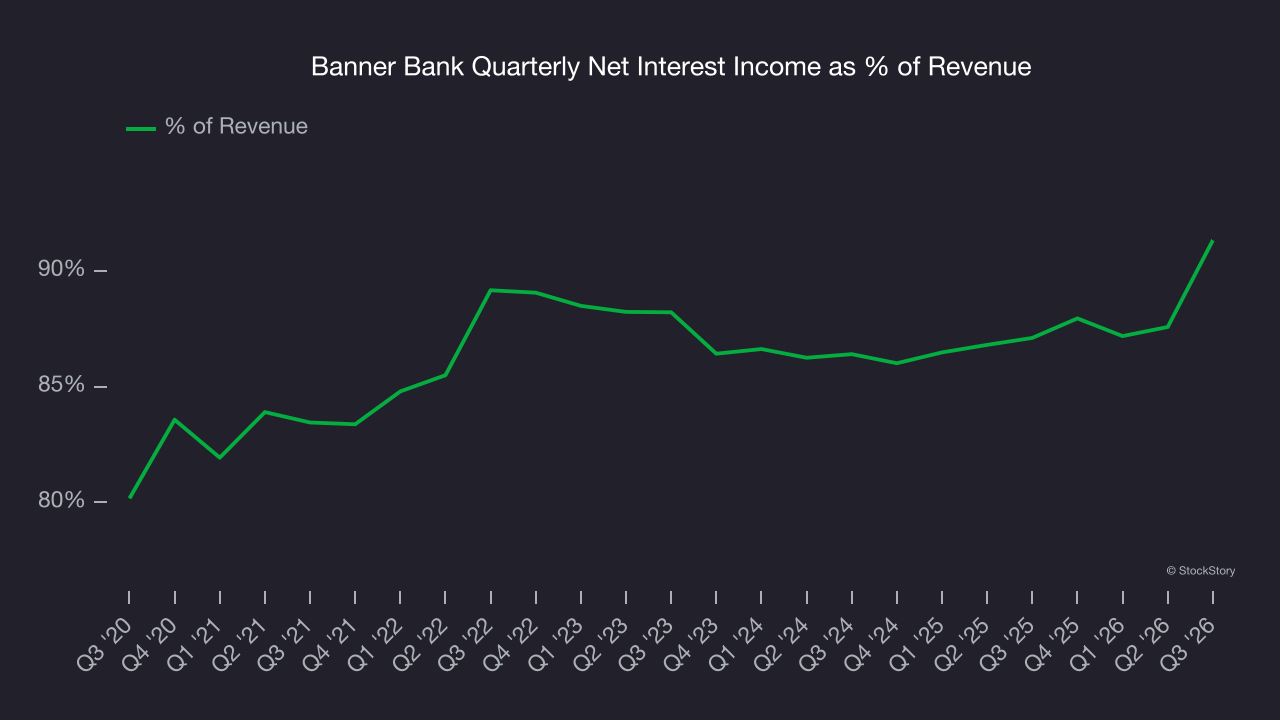
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Tangible book value per share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This explains why tangible book value per share (TBVPS) stands as the premier banking metric. TBVPS strips away questionable intangible assets, revealing concrete per-share net worth that investors can trust. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
Banner Bank’s TBVPS grew at a mediocre 4.2% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 5.6% annually over the last two years from $41.12 to $45.84 per share.
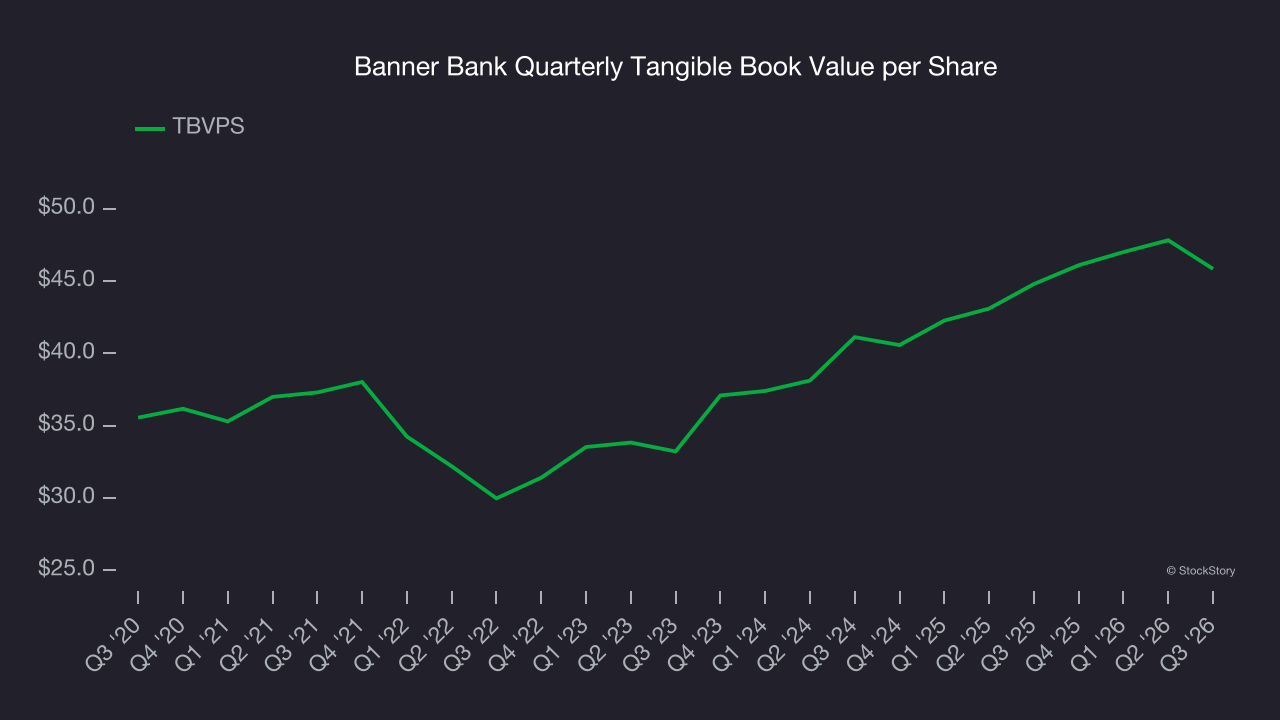
Over the next 12 months, Consensus estimates call for Banner Bank’s TBVPS to grow by 20.3% to $55.15, top-notch growth rate.
Key takeaways from Banner Bank’s Q3 results
We struggled to find many positives in these results. Its revenue missed and its net interest income fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock remained flat at $68.02 immediately after reporting.
So do we think Banner Bank is an attractive buy at the current price? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).