Rivian has been treading water for the past six months, recording a small return of 3.8% while holding steady at $15.05. The stock also fell short of the S&P 500’s 21.1% gain during that period.
Is now the time to buy Rivian, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Rivian Not Exciting?
We’re sitting this one out for now. Here are three reasons you should be careful with RIVN, plus one stock we’d rather own.
1. Demand Slips as Sales Volumes Slide
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Automobile Manufacturing company because there’s a ceiling to what customers will pay.
Rivian’s vehicles delivered came in at 12,194 in the latest quarter, and they declined by 9.2% annually over the last two years. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Rivian might have to lower prices or invest in product improvements to grow, factors that can hinder near-term profitability. 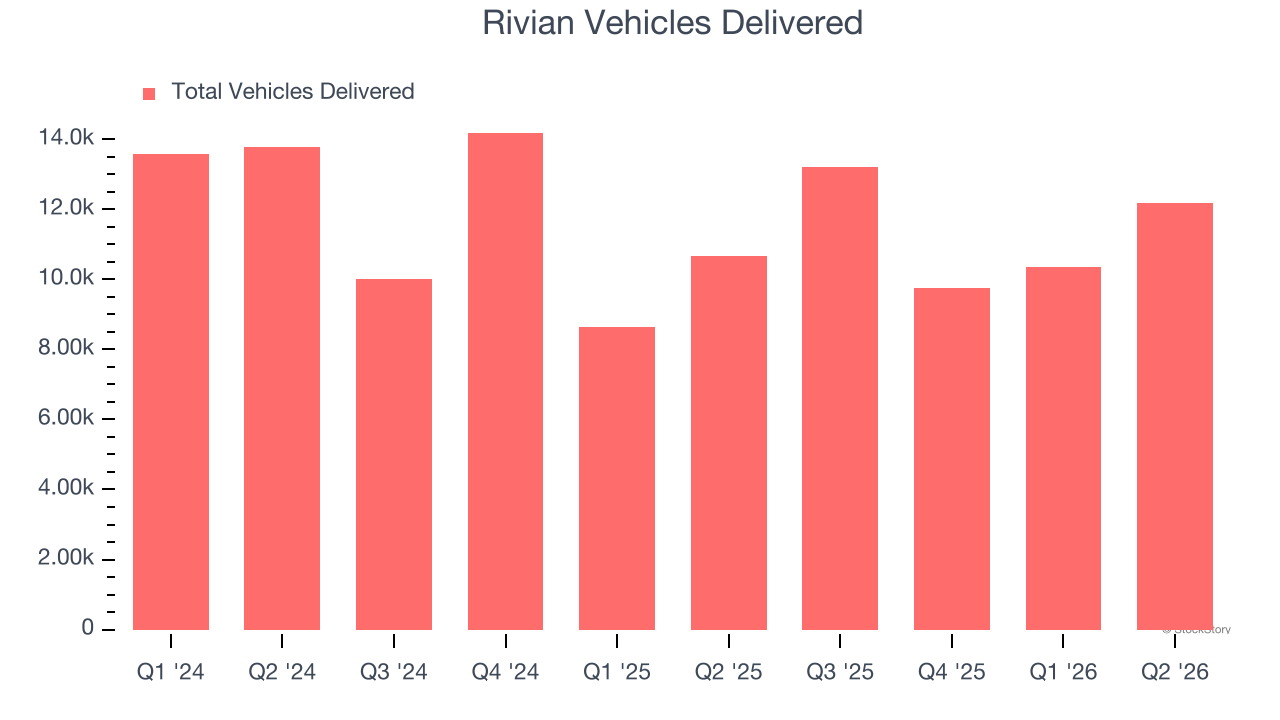
2. Cash Burn Ignites Concerns
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
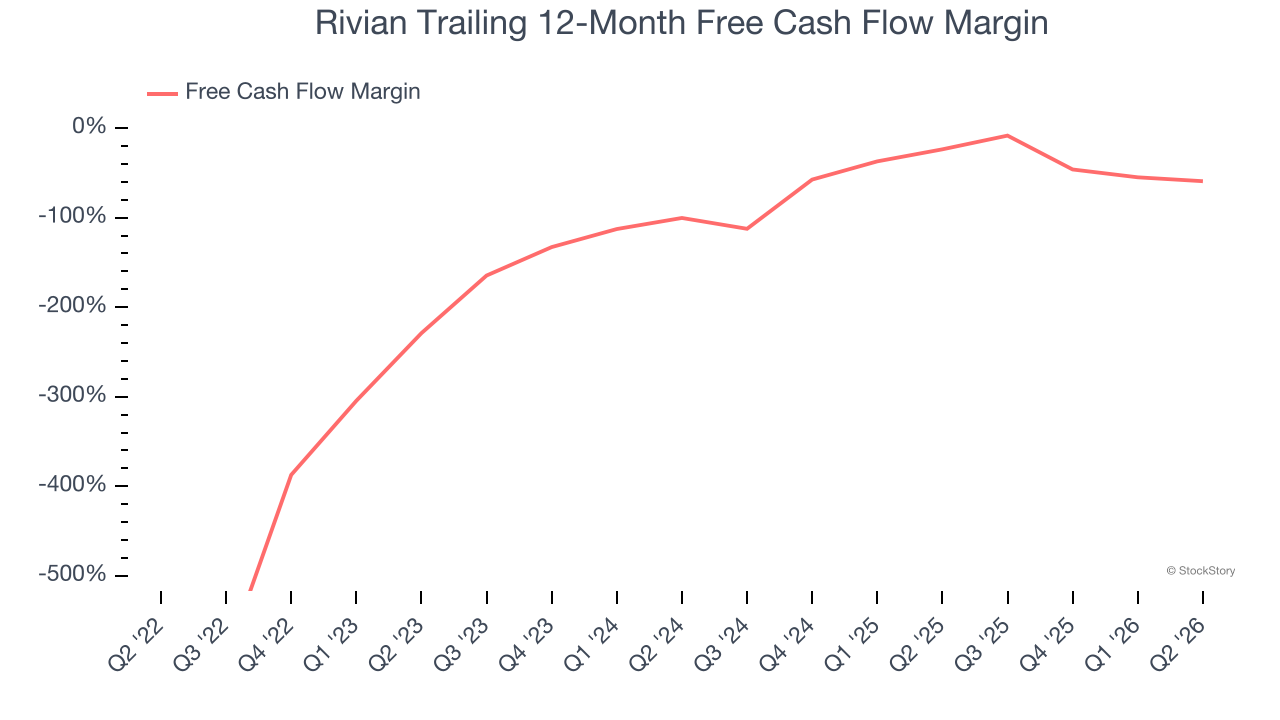
Rivian’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 114%, meaning it lit $113.98 of cash on fire for every $100 in revenue.
3. Short Cash Runway Exposes Shareholders to Potential Dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Rivian burned through $3.49 billion of cash over the last year, and its $6.78 billion of debt exceeds the $5.31 billion of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
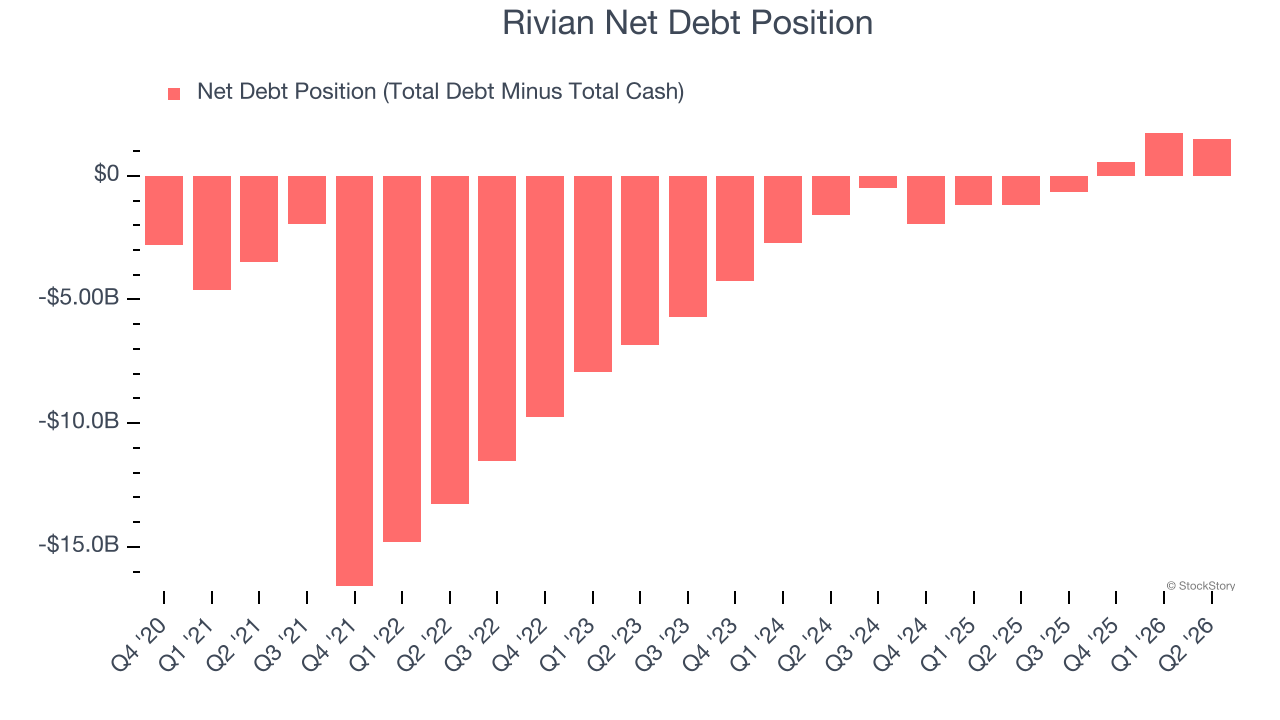
Unless the Rivian’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of Rivian until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final Judgment
Rivian isn’t a terrible business, but it doesn’t pass our quality test. With its shares underperforming the market lately, the stock trades at $15.05 per share (or a forward price-to-sales ratio of 2×). The market typically values companies like Rivian based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. We’d suggest looking at our favorite semiconductor picks and shovels play.
Stocks We Like More Than Rivian
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.