Shareholders of nLIGHT would probably like to forget the past six months even happened. The stock dropped 26.6% and now trades at $39.63. This might have investors contemplating their next move.
Is there a buying opportunity in nLIGHT, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is nLIGHT Not Exciting?
Despite the more favorable entry price, we’re cautious about nLIGHT. Here are three reasons we avoid LASR, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
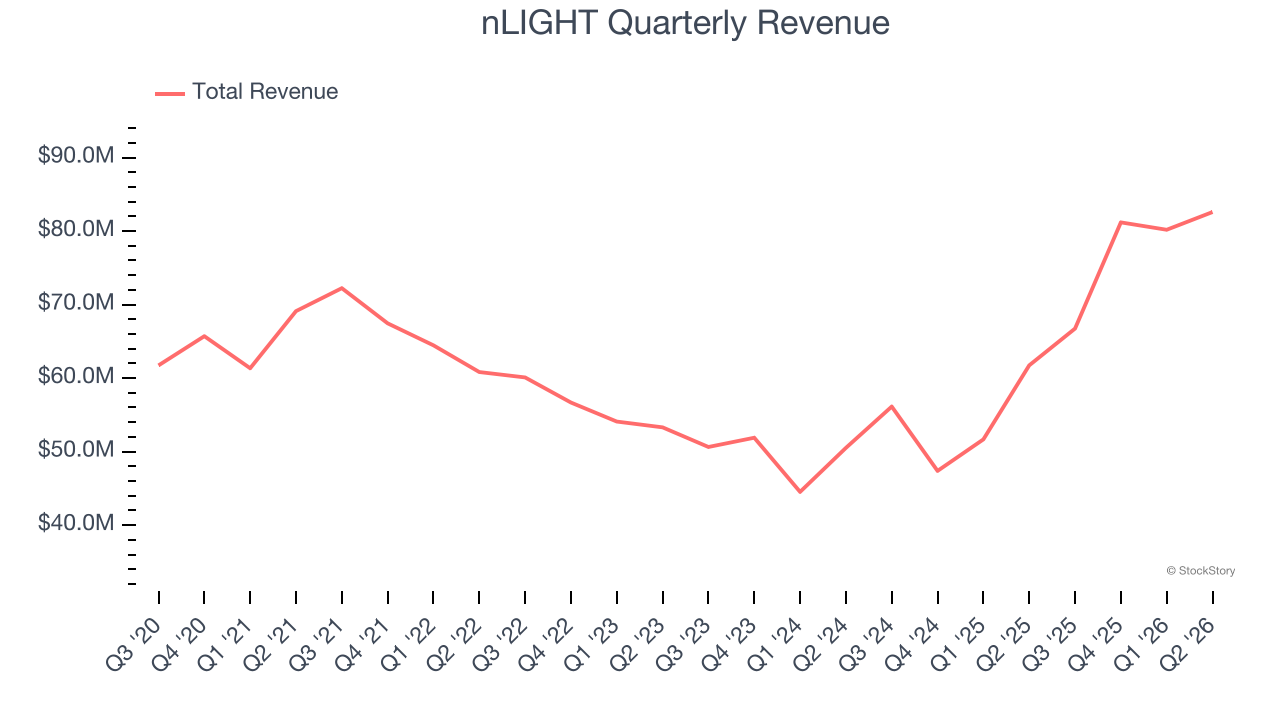
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, nLIGHT grew its sales at a sluggish 3.8% compounded annual growth rate. This was below our standard for the industrials sector.
2. Operating Losses Sound the Alarm
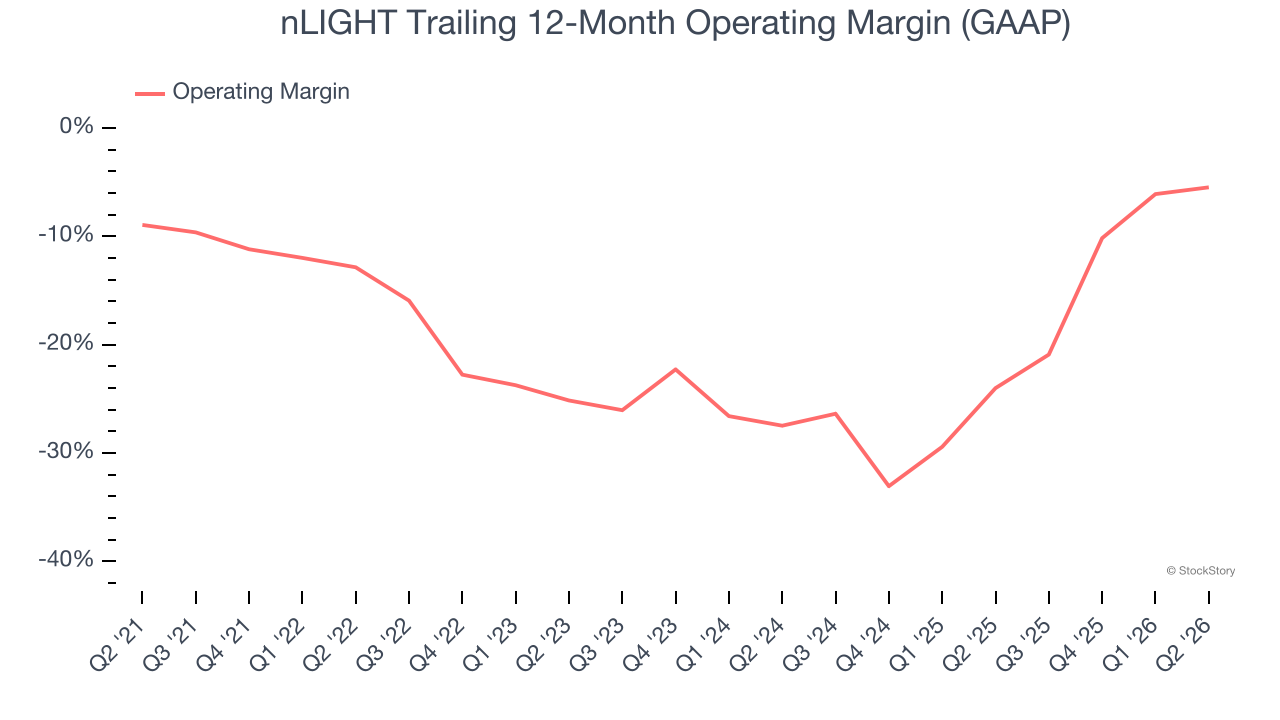
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
nLIGHT’s high expenses have contributed to an average operating margin of negative 17.6% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out. It’s hard to trust that the business can endure a full cycle.
3. Cash Burn Ignites Concerns
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
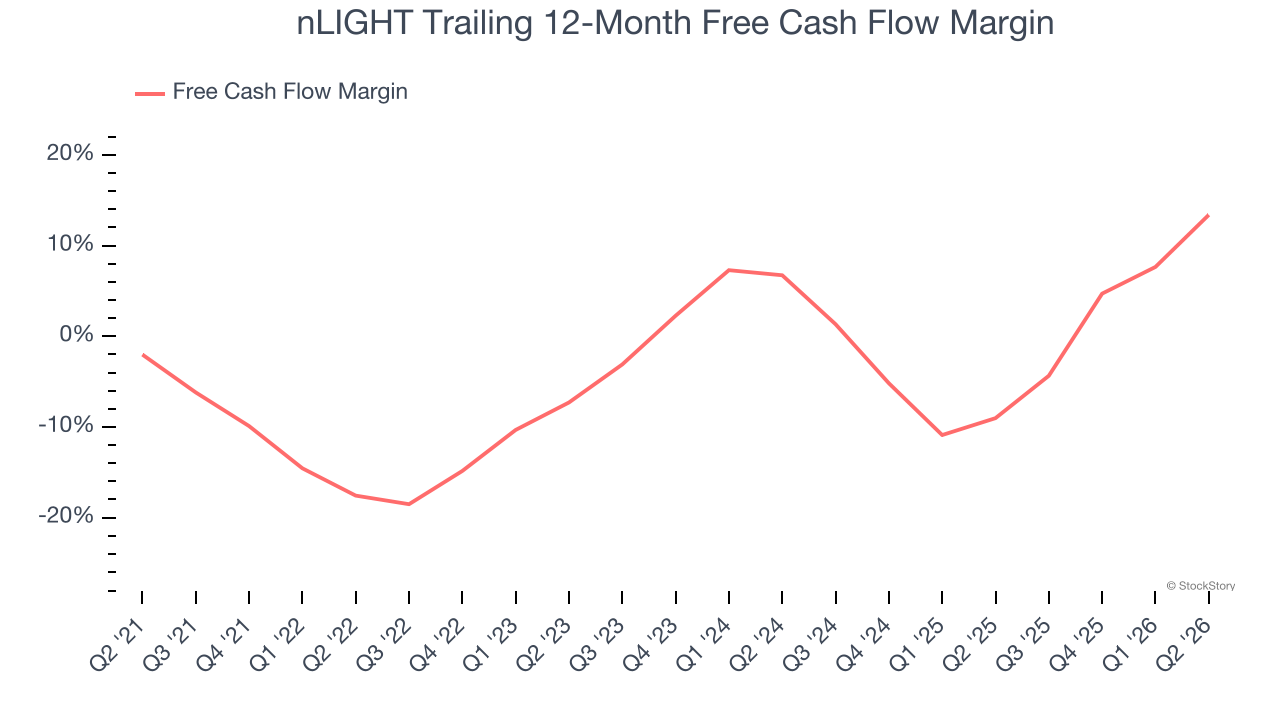
While nLIGHT posted positive free cash flow this quarter, the broader story hasn’t been so clean. nLIGHT’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 2.3%, meaning it lit $2.28 of cash on fire for every $100 in revenue.
Final Judgment
nLIGHT isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 105× forward P/E (or $39.63 per share). This valuation tells us a lot of optimism is priced in - you can find more timely opportunities elsewhere. We’d suggest looking at the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.