Since April 2026, Perma-Fix has been in a holding pattern, posting a small return of 1.9% while floating around $12.93. The stock also fell short of the S&P 500’s 7.5% gain during that period.
Is now the time to buy Perma-Fix, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why do we think Perma-Fix will underperform?
We’re passing on Perma-Fix for now. Here are three reasons why PESI doesn’t excite us, plus one stock we’d rather own.
1. Revenue spiraling downwards
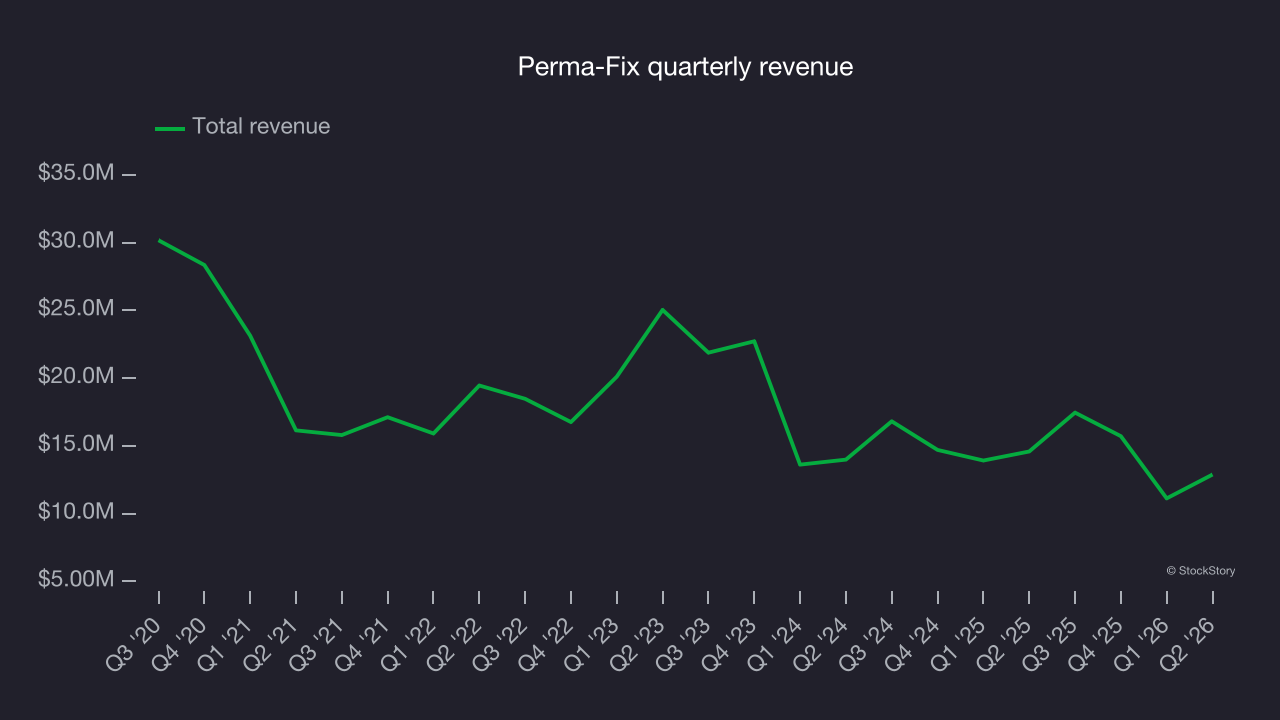
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Perma-Fix’s demand was weak and its revenue declined by 10.2% per year. This was below our standards and is a sign of poor business quality.
2. New investments fail to bear fruit as ROIC declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, Perma-Fix’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
3. Short cash runway exposes shareholders to potential dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Perma-Fix burned through $21.67 million of cash over the last year. With $33.95 million of cash on its balance sheet, the company has around 19 months of runway left (assuming its $2.35 million of debt isn’t due right away).
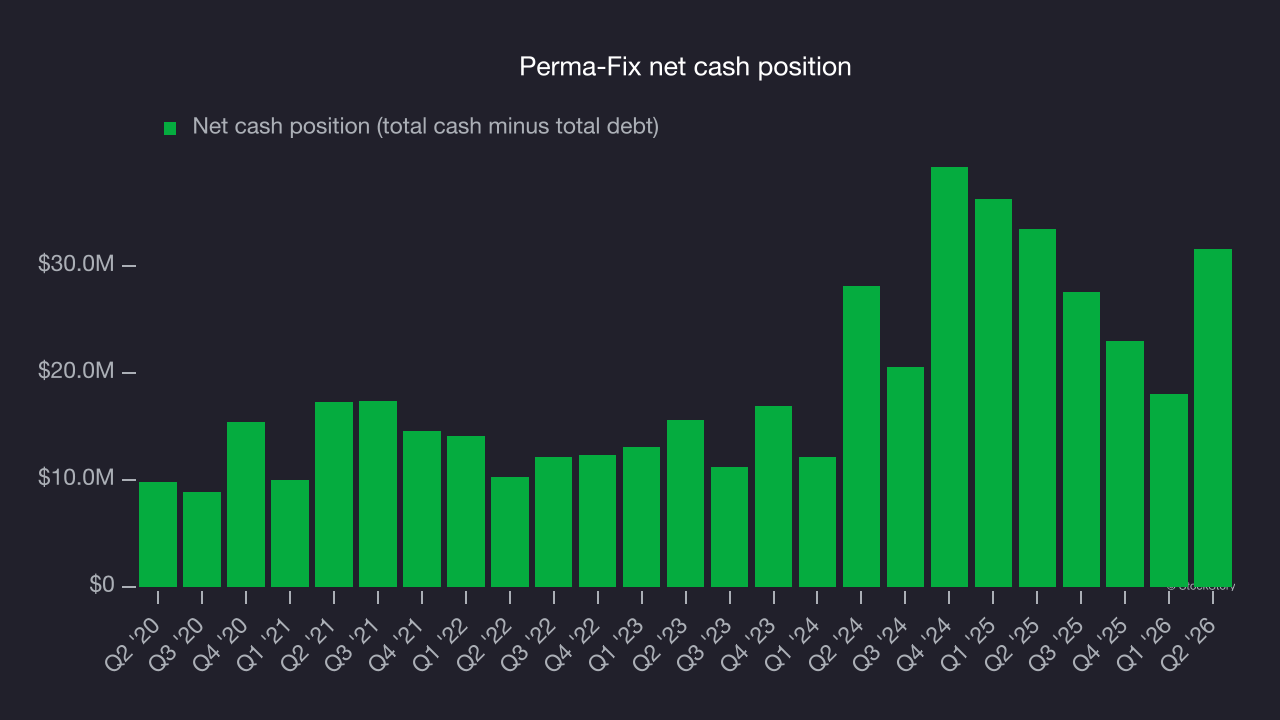
Unless the Perma-Fix’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of Perma-Fix until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final judgment
We see the value of companies helping their customers, but in the case of Perma-Fix, we’re out. With its shares underperforming the market lately, the stock trades at $12.93 per share (or a forward price-to-sales ratio of 3.2×). The market typically values companies like Perma-Fix based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
Stocks we would buy instead of Perma-Fix
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.