Auto and industrial parts retailer Genuine Parts (NYSE: GPC) met Wall Street’s revenue expectations in Q3 2026, with sales up 4.2% year on year to $6.52 billion. Its non-GAAP profit of $2.07 per share was 1.6% above analysts’ consensus estimates.
Is now the time to buy Genuine Parts? Find out by accessing our full research report, it’s free.
Genuine Parts (GPC) Q3 2026 Highlights:
- Revenue: $6.52 billion vs analyst estimates of $6.49 billion (4.2% year-on-year growth, in line)
- Adjusted EPS: $2.07 vs analyst estimates of $2.04 (1.6% beat)
- Management lowered its full-year Adjusted EPS guidance to $7.63 at the midpoint, a 1.6% decrease
- Operating Margin: 5%, in line with the same quarter last year
- Free Cash Flow Margin: 3.7%, similar to the same quarter last year
- Same-Store Sales rose 2.9% year on year, in line with the same quarter last year
- Market Capitalization: $17.95 billion
"Our third quarter performance demonstrates the strength of our market leading businesses and our teams' continued focus on serving customers and executing our strategic priorities," said Will Stengel, Chairman and Chief Executive Officer. "We also achieved important milestones in our separation process and remain on track to launch GPC and Motion as two independent, leading companies in the first quarter of 2027."
Company Overview
Largely targeting the professional customer, Genuine Parts (NYSE: GPC) sells auto and industrial parts such as batteries, belts, bearings, and machine fluids.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $25.33 billion in revenue over the past 12 months, Genuine Parts is one of the larger companies in the consumer retail industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For Genuine Parts to boost its sales, it likely needs to adjust its prices or lean into foreign markets.
As you can see below, Genuine Parts grew its sales at a sluggish 3.2% compounded annual growth rate over the last three years. This shows it failed to generate demand in any major way and is a rough starting point for our analysis.
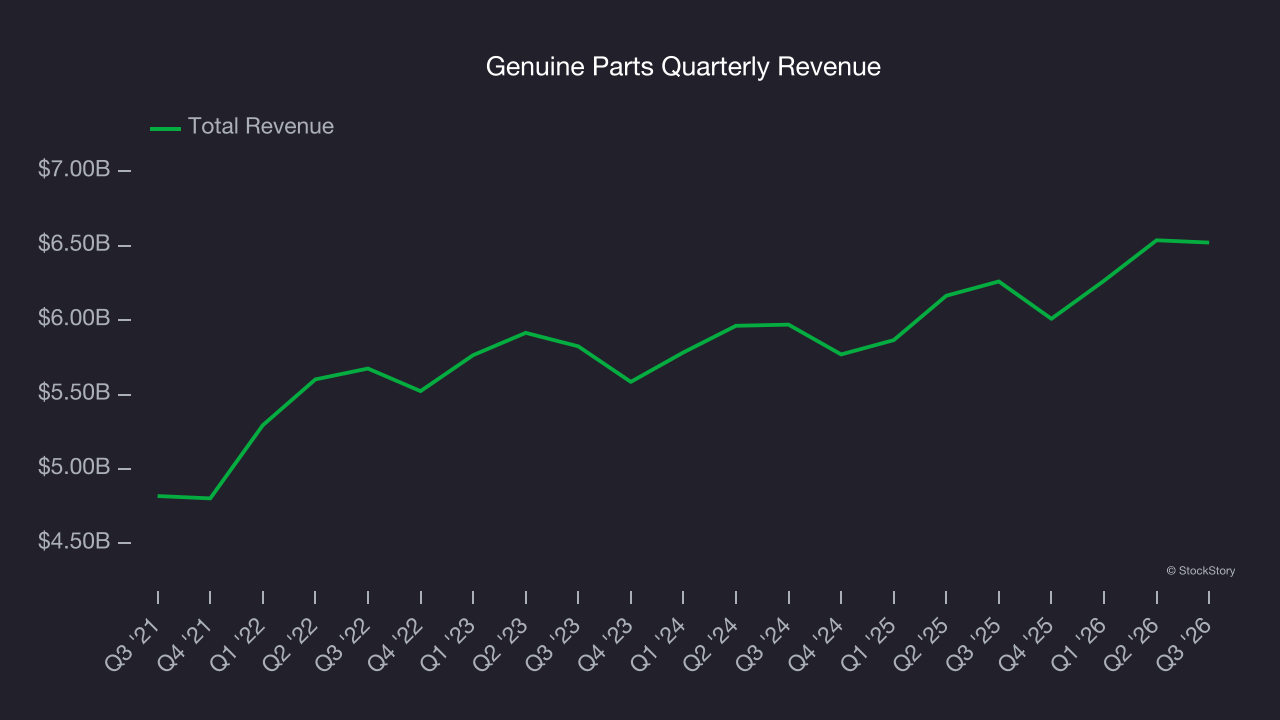
This quarter, Genuine Parts grew its revenue by 4.2% year on year, and its $6.52 billion of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.6% over the next 12 months, similar to its three-year rate. This projection is above the sector average and indicates its newer products will help support its historical top-line performance.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Same-Store Sales
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Genuine Parts’s demand within its existing locations has been relatively stable over the last two years but was below most retailers. On average, the company’s same-store sales have grown by 1.4% per year.
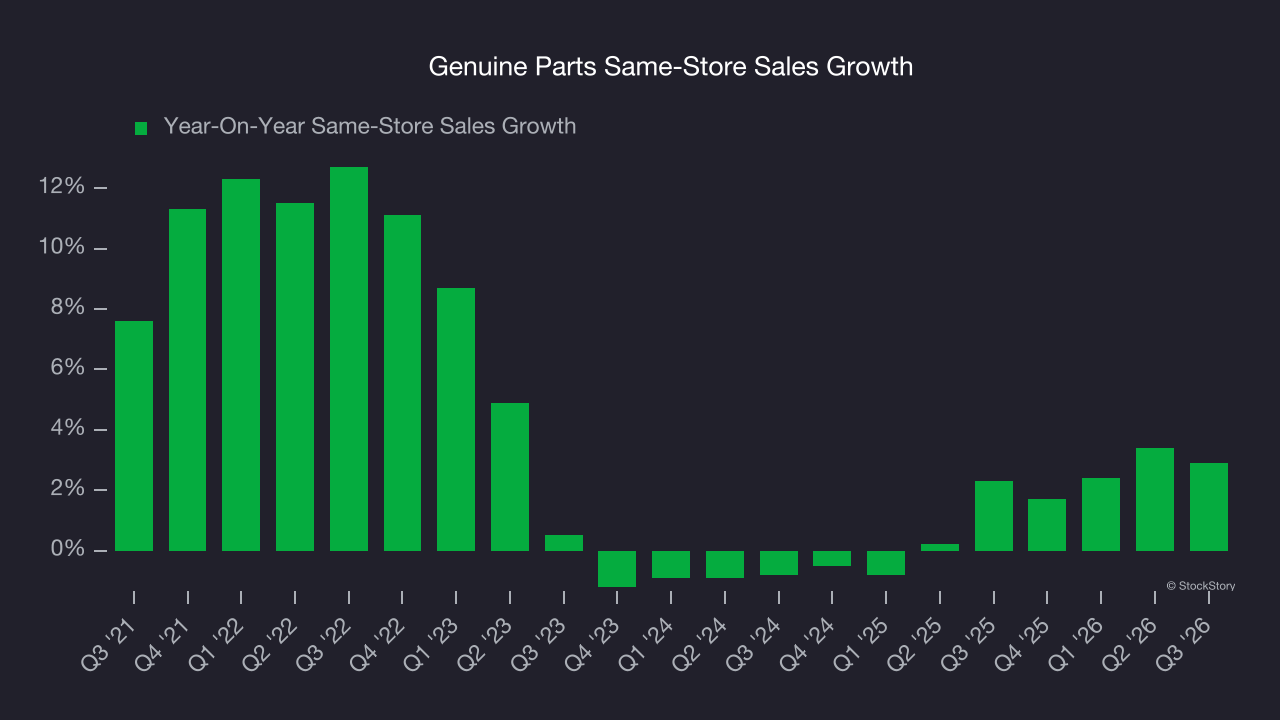
In the latest quarter, Genuine Parts’s same-store sales rose 2.9% year on year. This growth was an acceleration from its historical levels, which is always an encouraging sign.
Key Takeaways from Genuine Parts’s Q3 Results
It was good to see Genuine Parts meet analysts’ revenue expectations this quarter. We were also happy its gross margin narrowly outperformed Wall Street’s estimates. On the other hand, its full-year EPS guidance slightly missed. Overall, this was a softer quarter. The stock traded down 8.4% to $119.20 immediately following the results.
So do we think Genuine Parts is an attractive buy at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).