Consumer products company Colgate-Palmolive (NYSE: CL) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 4.6% year on year to $5.37 billion. Its non-GAAP profit of $0.97 per share was 4.8% above analysts’ consensus estimates.
For more on Colgate-Palmolive, read our free full research report.
Colgate-Palmolive (CL) Q3 2026 highlights:
- Revenue $5.37 billion vs S&P analysts’ consensus estimates of $5.34 billion (4.6% year-on-year growth, 0.6% beat)
- Adjusted EPS $0.97 vs S&P analysts’ consensus estimates of $0.93 (4.8% beat)
- Operating margin 20.3%, in line with the same quarter last year
- Free cash flow margin 19.3%, down from 21.6% in the same quarter last year
- Organic revenue rose 3.6% year on year (beat)
- Sales volumes rose 1.7% year on year (-1.9% in the same quarter last year)
- Market capitalization $74.26 billion
“Despite consumer uncertainty and ongoing macroeconomic volatility, our proactive focus on driving growth while building flexibility into our P&L gives us confidence we can navigate these challenges while continuing to deliver consistent, compounded earnings per share growth and drive long-term shareholder value.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can report a good quarter or two, but the best consistently grow over the long term.
With $21.28 billion in revenue over the past 12 months, Colgate-Palmolive is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to choose where it sells its products, a flexibility many companies lack. However, its scale is a double-edged sword because it’s harder to find incremental growth when its existing brands have penetrated most of the market. To accelerate revenue growth, Colgate-Palmolive likely needs to optimize its pricing or focus on new products and international expansion.
Colgate-Palmolive’s 3.6% annualized revenue growth over the last three years was sluggish, but a positive sign was that consumers bought more of its products.
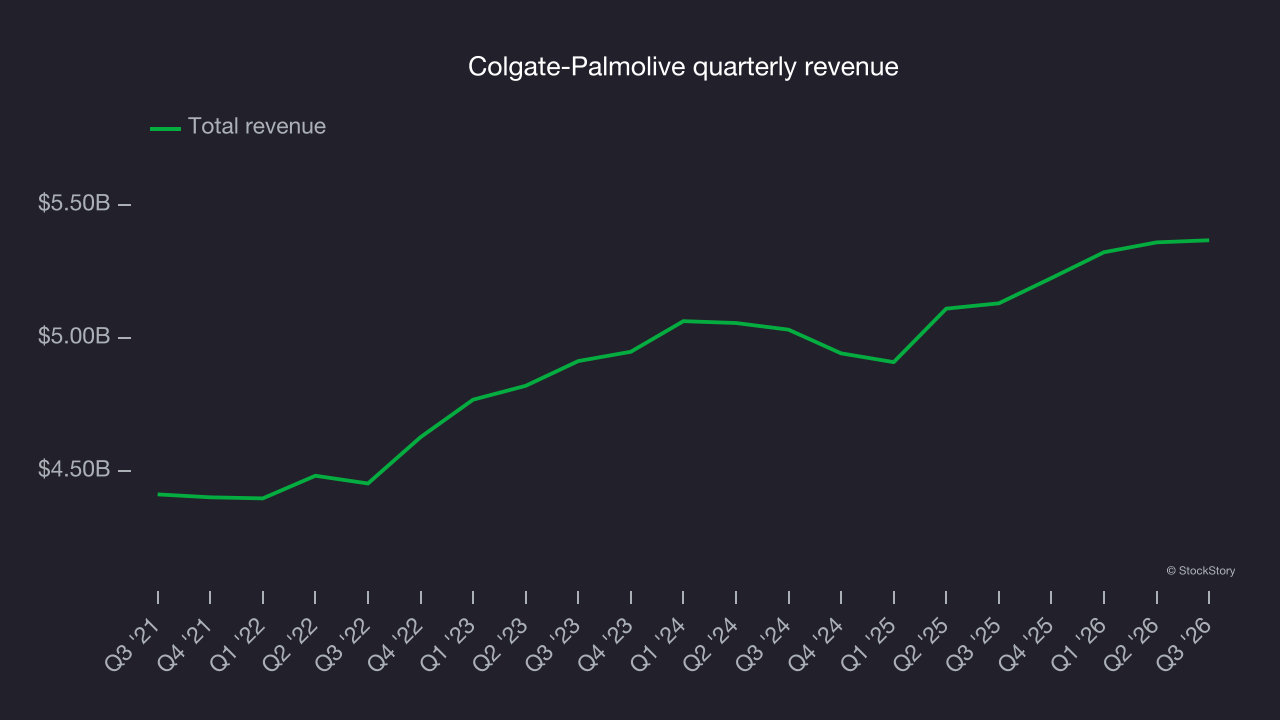
This quarter, Colgate-Palmolive reported modest year-on-year revenue growth of 4.6% but beat Wall Street’s consensus estimates by 0.6%.
Looking ahead, sell-side analysts expect revenue to grow 2.9% over the next 12 months, according to S&P, similar to its three-year rate. This projection is underwhelming and indicates its newer products will not lead to better top-line performance yet. On the positive side, the company is performing well on other measures of financial health.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is central to a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
To analyze whether Colgate-Palmolive generated its growth from changes in price or volume, we can compare its volume growth to its organic revenue growth, which excludes non-fundamental impacts on company financials like mergers and currency fluctuations.
Over the last two years, Colgate-Palmolive’s quarterly sales volumes have, on average, stayed about the same. This stability is normal as the quantity demanded for consumer staples products typically doesn’t see much volatility. The company’s flat volumes also indicate its average organic revenue growth of 2.4% was generated from price increases.
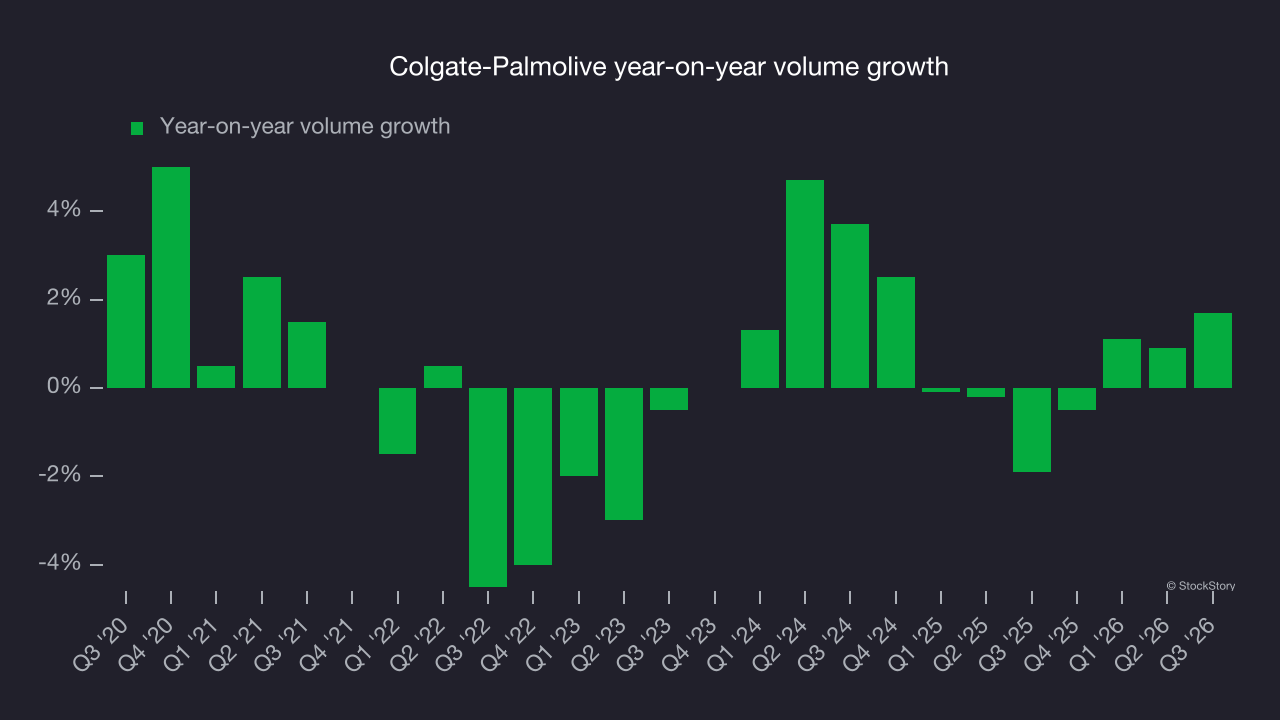
In Colgate-Palmolive’s Q3 2026, sales volumes edged higher by 1.7% year on year. This marked an acceleration from historical levels, a positive signal.
Key takeaways from Colgate-Palmolive’s Q3 results
Colgate-Palmolive’s gross margin and EPS both topped Wall Street’s consensus estimates, making for a solid Q3. Shares surged 5.2% to $98.03 immediately after the report.
When deciding whether to invest in Colgate-Palmolive, the latest quarterly results matter, but longer-term business quality and valuation matter more. Read the full research report here (it’s free).