Agriculture products company SiteOne Landscape Supply (NYSE: SITE) fell short of the market’s revenue expectations in Q3 2026 as revenue rose 2.6% year on year to $1.29 billion. Its GAAP profit of $1.46 per share was 4.3% above analysts’ consensus estimates.
For more on SiteOne, read our free full research report.
SiteOne (SITE) Q3 2026 highlights:
- Revenue $1.29 billion vs S&P analysts’ consensus estimates of $1.30 billion (2.6% year-on-year growth, 0.9% miss)
- EPS (GAAP) $1.46 vs analysts’ consensus estimates of $1.40 (4.3% beat)
- Adjusted EBITDA $138.3 million vs analysts’ consensus estimates of $134.2 million (10.7% margin, 3% beat)
- EBITDA guidance $432.5 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 7.4%, in line with the same quarter last year
- Free cash flow margin 8.4%, down from 9.4% in the same quarter last year
- Organic revenue fell 1% year on year (miss)
- Market capitalization $4.50 billion
“We delivered a solid third quarter performance with 8% growth in Adjusted EBITDA and 60 basis points of Adjusted EBITDA margin expansion despite the continued softness in underlying market demand and a delayed fall season due to hot and dry weather in key markets,” said Doug Black, Chairman and CEO of SiteOne. “Our teams made good progress on our commercial and operational initiatives while maintaining disciplined cost control in the face of lower sales volume. We also completed one acquisition during the quarter and have a very active pipeline of potential deals. While we expect market conditions to be challenging in the near term, we remain focused on the opportunities within our control to gain market share, improve productivity, and strengthen our competitive position. These self-help opportunities combined with our acquisition strategy enable us to drive sustained performance and growth for our shareholders this year and in the years to come.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. SiteOne’s revenue grew at a decent 7.5% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
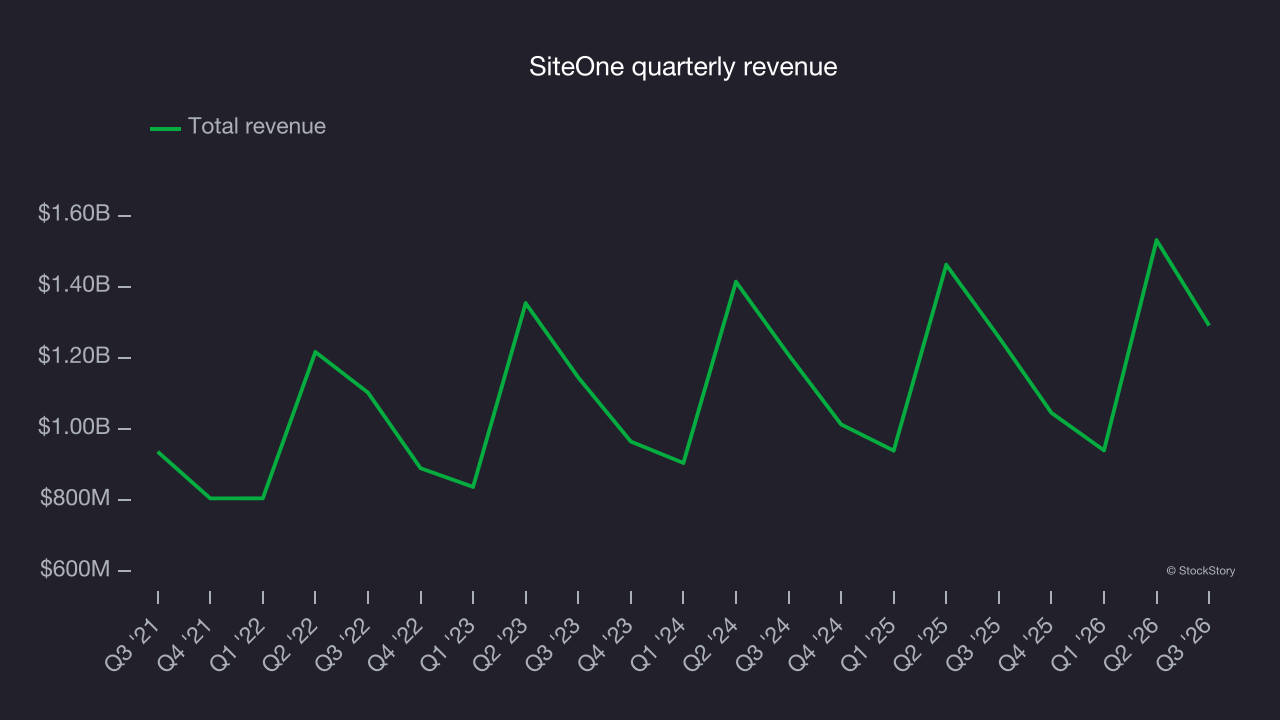
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. SiteOne’s recent performance shows its demand has slowed as its annualized revenue growth of 3.4% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 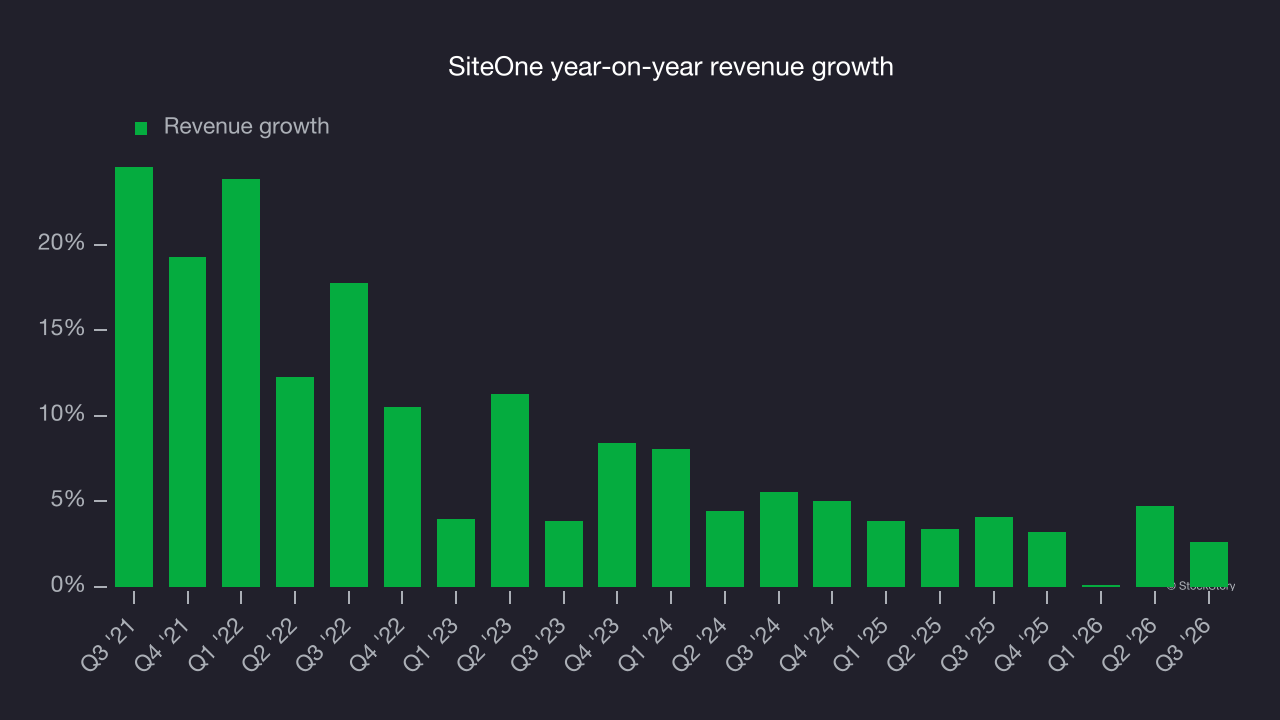
SiteOne also reports organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, SiteOne’s organic revenue was flat. Organic revenue growth trailed its two-year revenue growth, indicating that some combination of acquisitions and foreign exchange rates boosted its headline results. 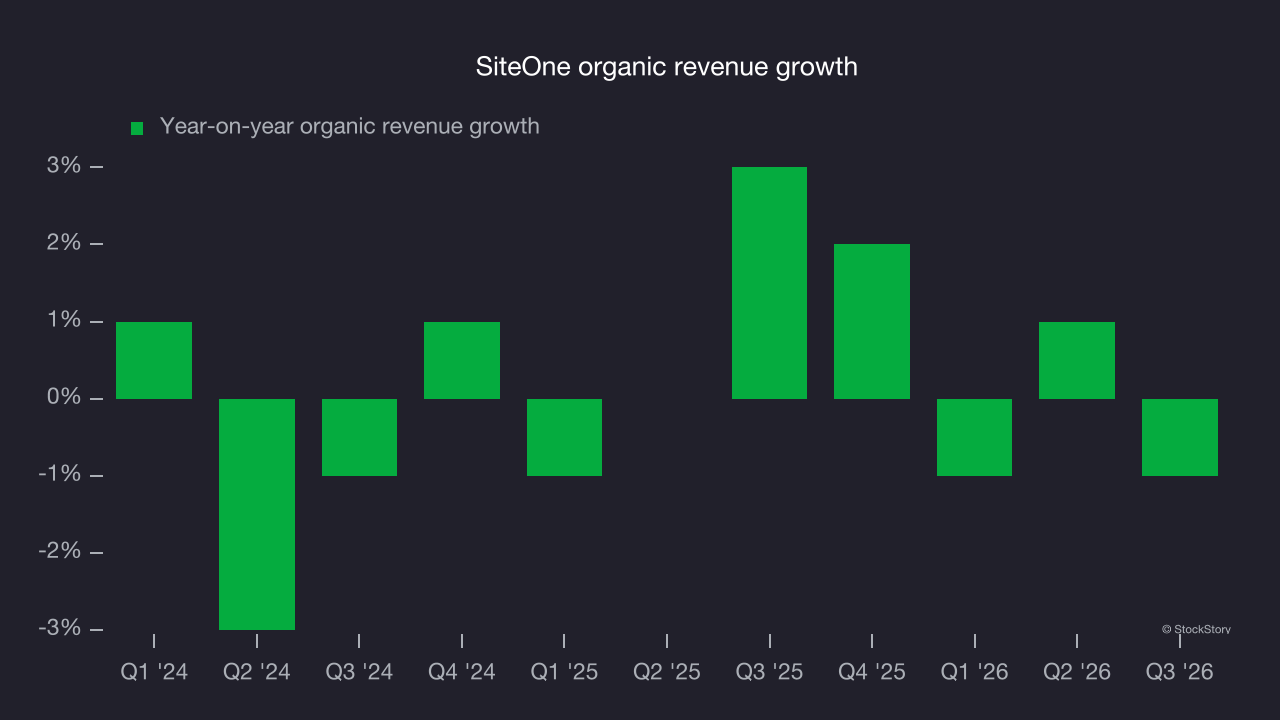
This quarter, SiteOne’s revenue grew by 2.6% year on year to $1.29 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 4.6% over the next 12 months, according to S&P, similar to its two-year rate. Although this projection indicates its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
SiteOne was profitable over the last five years but held back by its large cost base. Its average operating margin of 6% was weak for an industrials business. This result is surprising given its high gross margin baseline.
Looking at the trend in its profitability, SiteOne’s operating margin decreased by 3.9 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. SiteOne’s poor performance shows that costs were rising and it couldn’t pass them on to its customers.
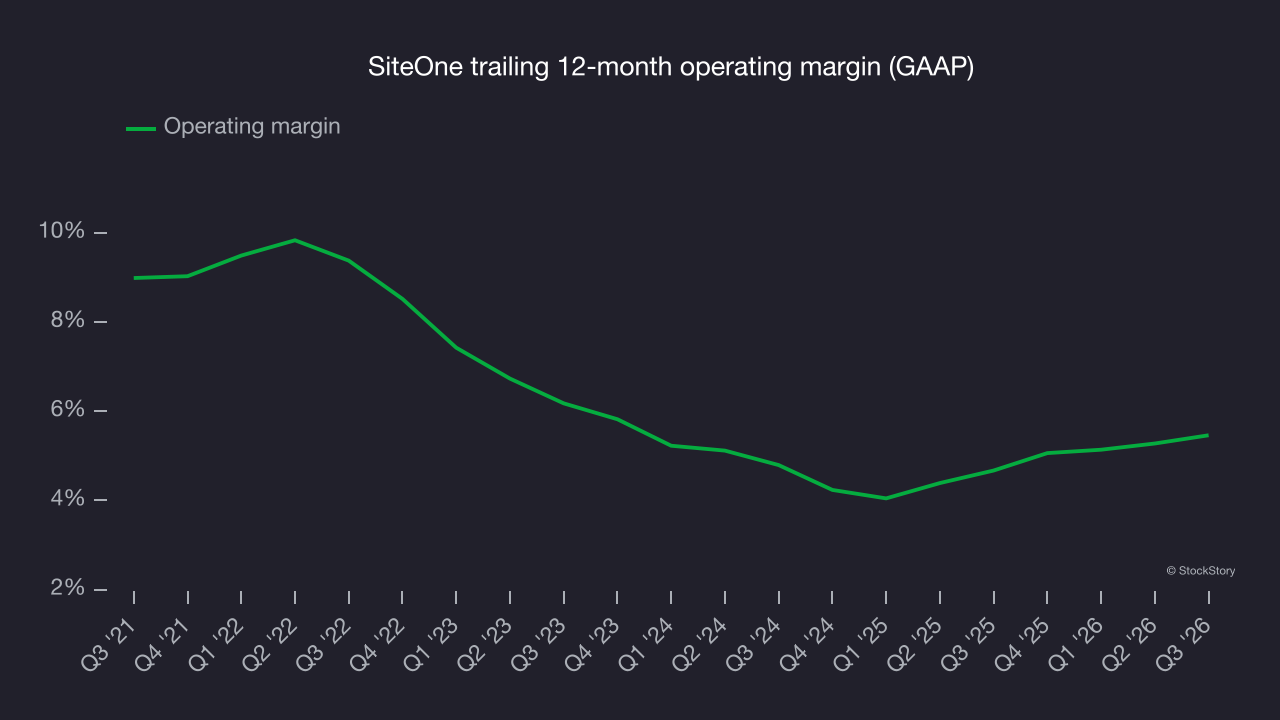
In Q3, SiteOne generated an operating margin of 7.4%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
SiteOne’s EPS declined by 4.8% annually over the last five years while its revenue grew by 7.5%. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
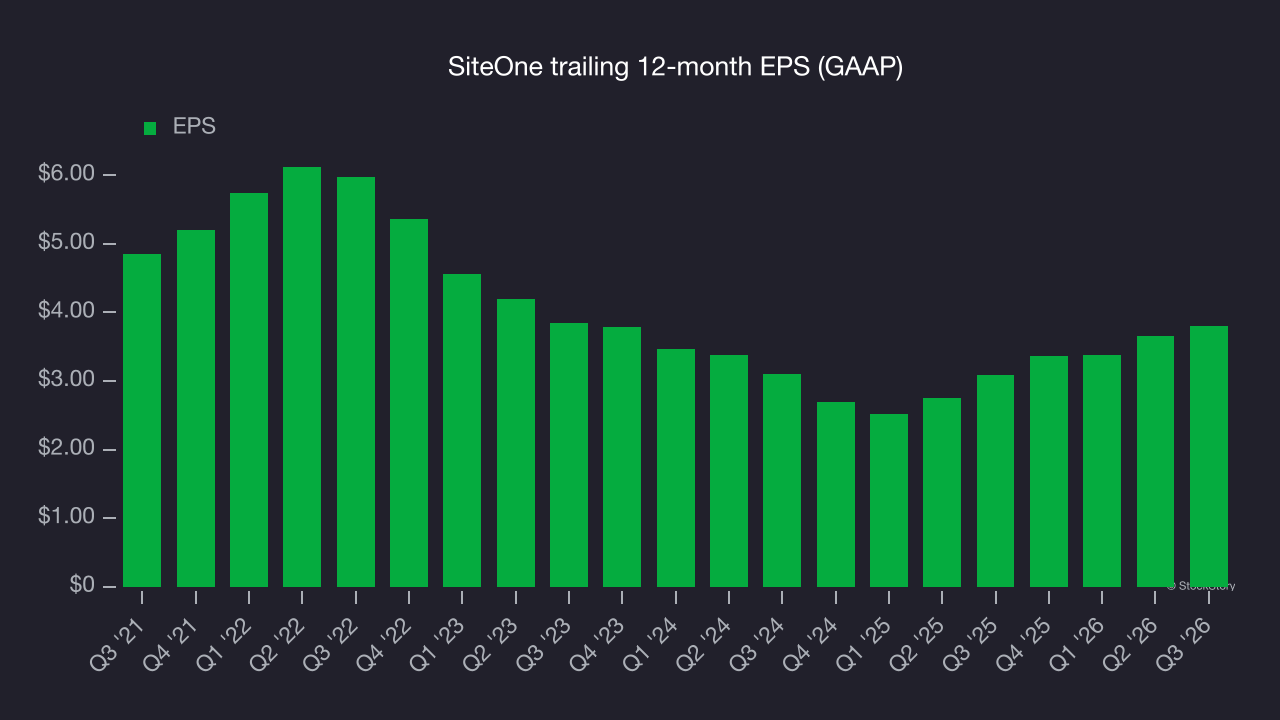
A closer look at SiteOne’s earnings helps explain its performance. As mentioned earlier, SiteOne’s operating margin was flat this quarter but declined by 3.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
For SiteOne, its two-year annual EPS growth of 10.6% was higher than its five-year trend. This acceleration made it one of the faster-growing industrials companies in recent history.
In Q3, SiteOne reported EPS of $1.46, up from $1.31 in the same quarter last year. This result beat analysts’ consensus estimates by 4.3%. Over the next 12 months, Wall Street expects SiteOne’s full-year EPS to grow 16.6% from $3.80 to $4.43, according to S&P.
Key takeaways from SiteOne’s Q3 results
SiteOne’s EBITDA and EPS beat consensus estimates, but organic revenue missed expectations and total revenue fell slightly short of Wall Street’s consensus. Those revenue shortfalls left room for a better quarter despite the earnings beats. Shares fell 4.6% to $98.25 immediately after the results.
SiteOne’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so a closer look can help assess whether the stock is a buy at the current price. The latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. For more on SiteOne, read our full research report here (it’s free).