Let’s dig into the relative performance of Lincoln Educational (NASDAQ: LINC) and its peers as we unravel the now-completed Q2 consumer discretionary - education services earnings season.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Education services companies provide postsecondary instruction, professional certifications, test preparation, and corporate training, both online and in-person. Tailwinds include lifelong-learning demand driven by rapid technological change, employer-sponsored upskilling programs, and growing acceptance of online credentials. Headwinds are substantial: heavy regulatory oversight—particularly around student-loan eligibility and enrollment practices—can abruptly alter business models. Reputational risk from scrutiny over student outcomes and debt burdens constrains marketing strategies. Competition from free or low-cost digital alternatives (MOOCs, employer-built academies) pressures pricing.
The 5 consumer discretionary - education services stocks we track reported a satisfactory Q2. As a group, revenues beat analysts’ consensus estimates by 2.3%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 15.9% since the latest earnings results.
Best Q2: Lincoln Educational (NASDAQ: LINC)
Established in 1946, Lincoln Educational (NASDAQ: LINC) is a provider of specialized technical training in the United States, offering career-oriented programs to provide practical skills required in the workforce.
Lincoln Educational reported revenues of $142.6 million, up 22.4% year on year. This print exceeded analysts’ expectations by 2.6%. Overall, it was a strong quarter for the company with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
“During the second quarter and first half of the year, Lincoln continued to execute our mission of providing superior education and training to our students for high in-demand careers and generated strong operating results. Our performance and current third quarter trends lead to our reiterating our full year 2026 financial guidance,” said Scott Shaw, President & CEO.
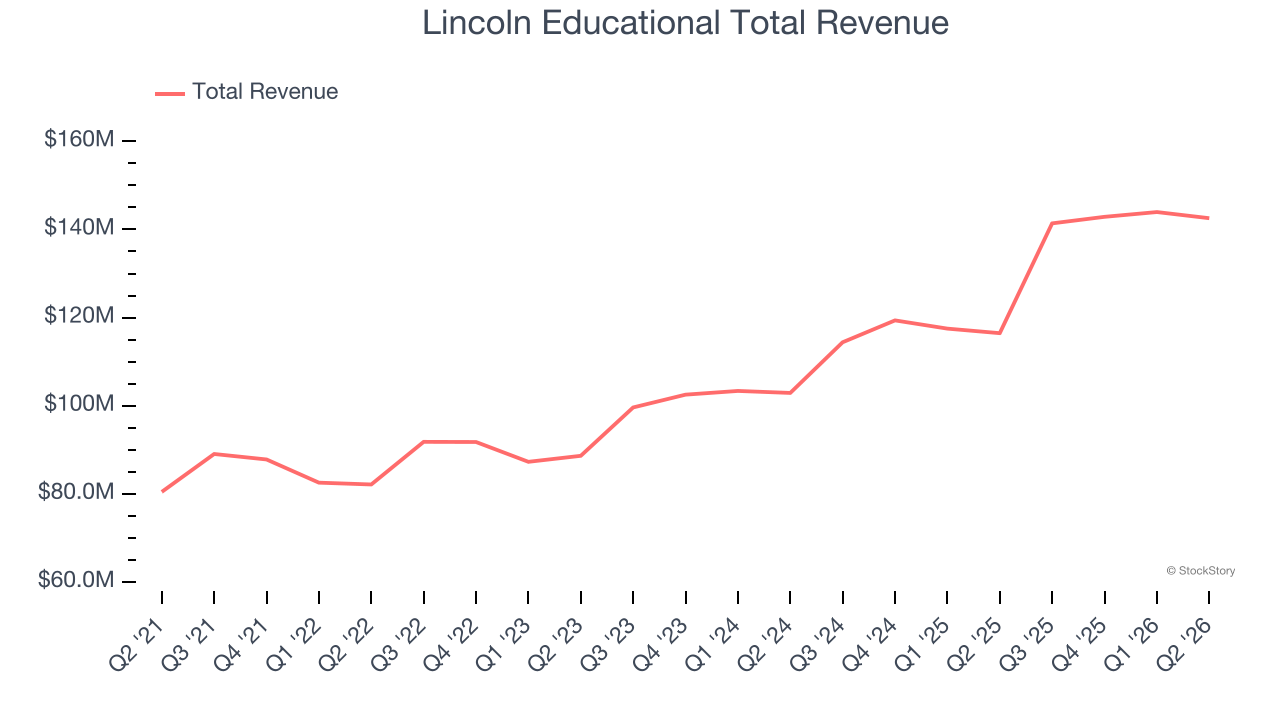
Lincoln Educational achieved the fastest revenue growth in the group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 47.2% since reporting and currently trades at $21.66.
Is now the time to buy Lincoln Educational? Access our full analysis of the earnings results here, it’s free.
Laureate Education (NASDAQ: LAUR)
Founded in 1998 by Douglas L. Becker and based in Miami, Laureate Education (NASDAQ: LAUR) is a global network of higher education institutions.
Laureate Education reported revenues of $615.9 million, up 17.5% year on year, outperforming analysts’ expectations by 2.3%. The business had a satisfactory quarter with full-year revenue guidance slightly topping analysts’ expectations.
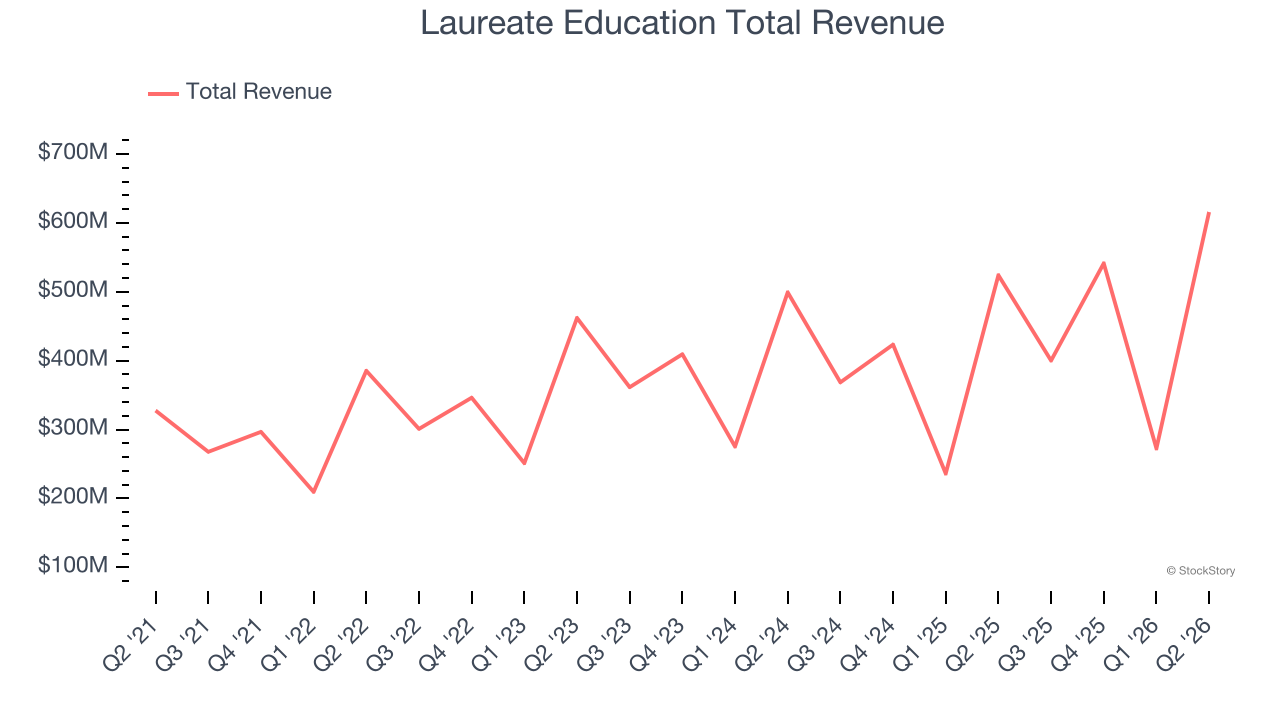
Laureate Education achieved the highest full-year guidance raise of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 2% since reporting. It currently trades at $37.63.
Is now the time to buy Laureate Education? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: Strategic Education (NASDAQ: STRA)
Formed through the merger of Strayer Education and Capella Education in 2018, Strategic Education (NASDAQ: STRA) is a career-focused higher education provider.
Strategic Education reported revenues of $337.3 million, up 4.9% year on year, exceeding analysts’ expectations by 3%. Still, it was a mixed quarter as it posted a significant miss of analysts’ EPS estimates.
Strategic Education delivered the slowest revenue growth in the group. As expected, the stock is down 6.7% since the results and currently trades at $75.90.
Read our full analysis of Strategic Education’s results here.
Covista (NYSE: CVSA)
Formerly known as DeVry Education Group, Covista (NYSE: CVSA) is a global provider of workforce solutions and educational services.
Covista reported revenues of $501.4 million, up 9.7% year on year. This result beat analysts’ expectations by 3.1%. Overall, it was a satisfactory quarter as it also recorded a beat of analysts’ EPS estimates.
Covista pulled off the biggest analyst estimate beat among its peers. The stock is down 5.4% since reporting and currently trades at $117.61.
Read our full, actionable report on Covista here, it’s free.
Bright Horizons (NYSE: BFAM)
Founded in 1986, Bright Horizons (NYSE: BFAM) is a global provider of child care, early education, and workforce support solutions.
Bright Horizons reported revenues of $779.2 million, up 6.5% year on year. This number surpassed analysts’ expectations by 0.6%. Taking a step back, it was a mixed quarter as it also logged a beat of analysts’ EPS estimates but full-year revenue guidance meeting analysts’ expectations.
Bright Horizons had the weakest performance against analyst estimates and weakest full-year guidance update of the whole group. The stock is down 18.2% since reporting and currently trades at $63.74.
Read our full, actionable report on Bright Horizons here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.