Renewable fuels producer Gevo (NASDAQ: GEVO) will be announcing earnings results tomorrow after market close. Here’s what investors should know.
Gevo beat analysts’ revenue expectations last quarter, reporting revenues of $46.5 million, up 7.1% year on year. It was a very strong quarter for the company, with a solid beat of analysts’ EBITDA estimates.
Is Gevo a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Gevo’s revenue to grow 31.3% year on year, slowing from the 2,074% increase it recorded in the same quarter last year.
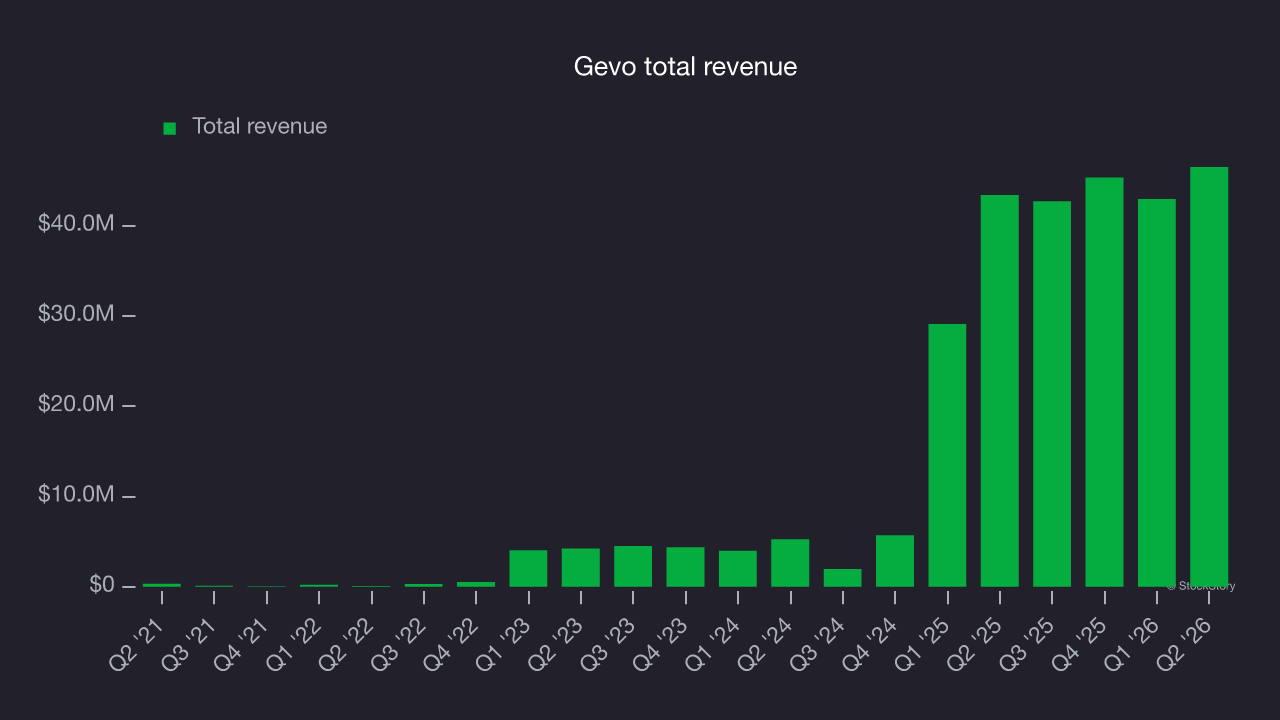
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Gevo has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Gevo’s peers in the mixed or offshore upstream e&p segment, some have already reported their Q3 results, giving us a hint as to what we can expect. APA Corporation delivered year-on-year revenue growth of 41%, beating analysts’ expectations by 6.9%, and Murphy Oil reported revenues up 16.6%, topping estimates by 8.7%. APA Corporation traded down 2.3% following the results while Murphy Oil’s stock price was unchanged.
Read our full analysis of APA Corporation’s results here and Murphy Oil’s results here.
In the last twelve months or so, the market has shifted its attention from one area of macro importance to the next (AI disintermediation and AI capex spending to geopolitical conflict, rates, and whether the economy is on solid footing or not). While some of the mixed or offshore upstream e&p stocks have shown solid performance in this choppy environment, the group has generally underperformed, with share prices down 11.3% on average over the last month. Gevo is up 7.4% during the same time and is heading into earnings with an average analyst price target of $5.05 (compared to the current share price of $1.38).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.