Medical device company ResMed (NYSE: RMD) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q1 2027), with revenue rising 5.9% year on year to $1.41 billion. Its non-GAAP profit of $2.91 per share was 8.9% above analysts’ consensus estimates.
For more on ResMed, read our free full research report.
ResMed (RMD) Q3 CY2026 highlights:
- Revenue $1.41 billion vs S&P analysts’ consensus estimates of $1.39 billion (5.9% year-on-year growth, 1.7% beat)
- Adjusted EPS $2.91 vs S&P analysts’ consensus estimates of $2.67 (8.9% beat)
- Operating margin 32%, down from 33.4% in the same quarter last year
- Free cash flow margin 26.4%, down from 31% in the same quarter last year
- Constant currency revenue rose 7% year on year (8% in the same quarter last year)
- Market capitalization $35.18 billion
“We began fiscal year 2027 with a strong first quarter, driven by continued global demand for our sleep and breathing health solutions and ongoing execution across our business,” said Resmed's Chairman and CEO, Mick Farrell. “Year over year, we grew core constant currency revenue 7%, expanded non-GAAP gross margin by 50 basis points, and increased non-GAAP earnings per share by 14%. Our strong free cash flow and the proceeds from our divestiture of MatrixCare enabled us to both invest in innovation and return more than $1 billion to shareholders during the quarter.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. ResMed’s 11.4% annualized revenue growth over the last five years was decent. Its growth was slightly above the average healthcare company and shows its offerings resonate with customers.
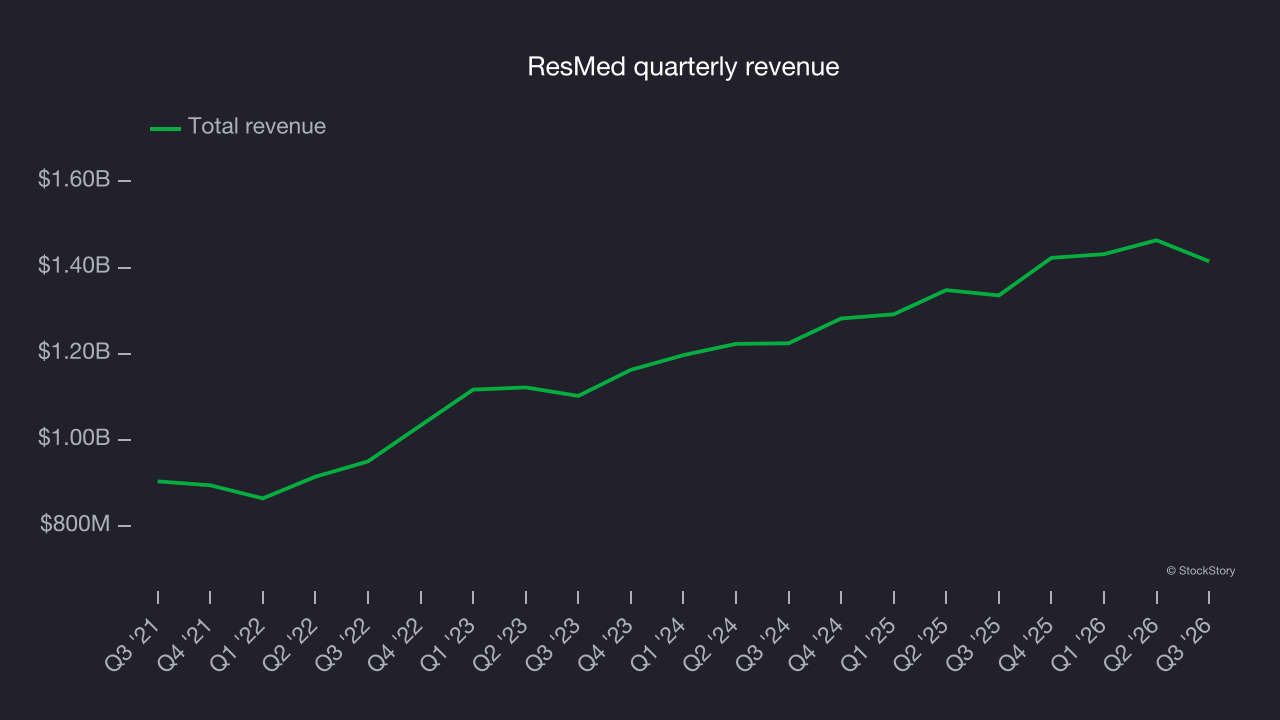
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. ResMed’s annualized revenue growth of 9.2% over the last two years is below its five-year trend, but the results were still respectable. 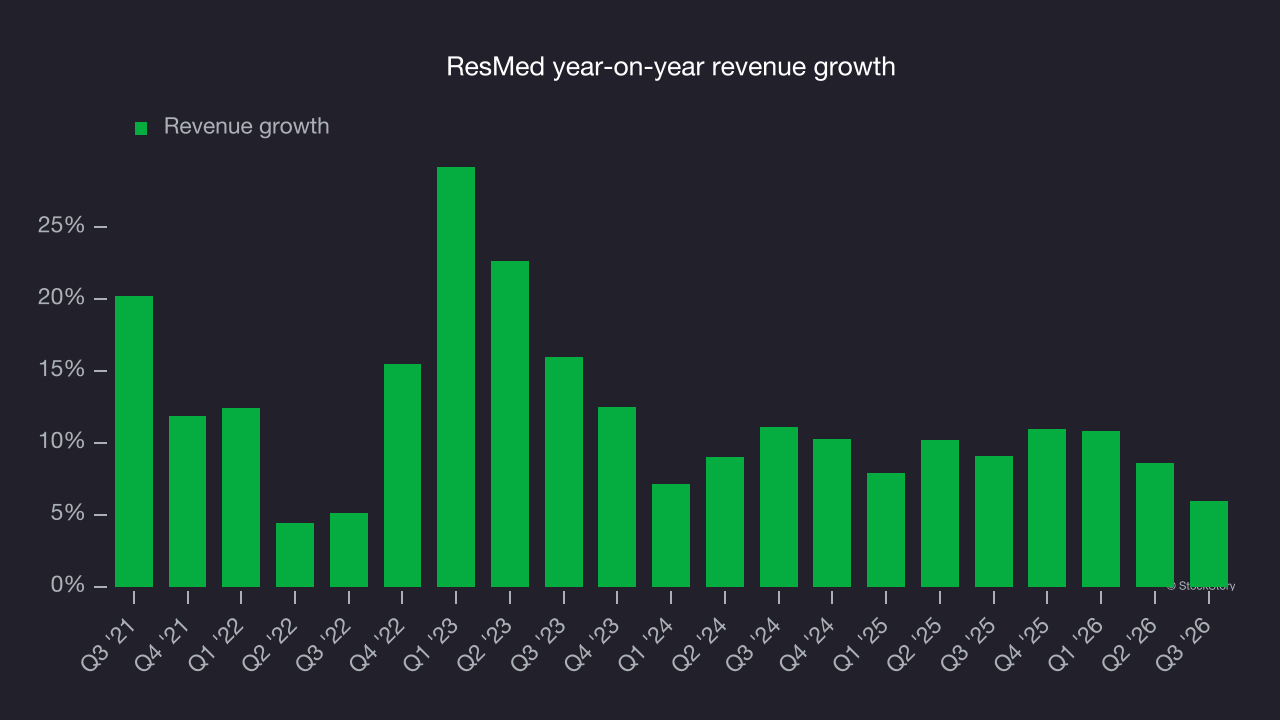
The company’s constant currency revenue offers a closer look at its revenue dynamics by excluding currency movements that are outside its control and not indicative of demand. Over the last two years, its constant currency revenue averaged 8.4% year-on-year growth. This was in line with reported revenue growth, indicating that foreign exchange has not had a meaningful impact on revenue. 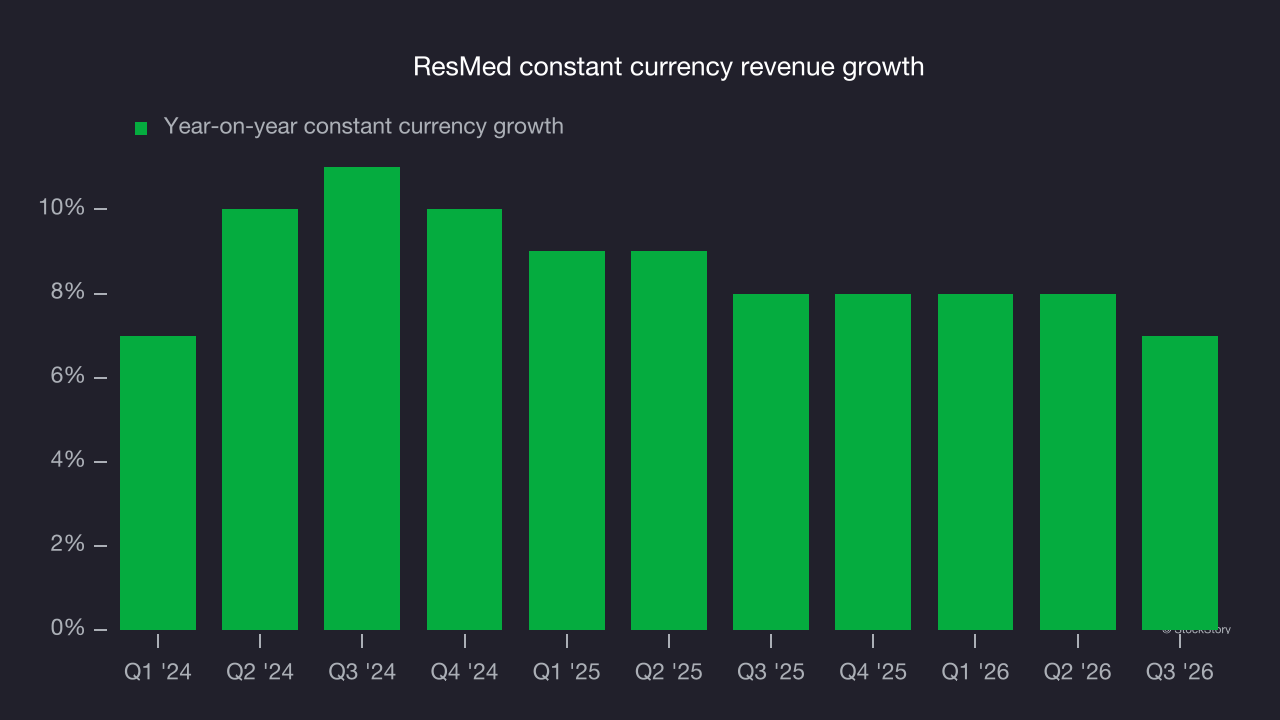
This quarter, ResMed reported year-on-year revenue growth of 5.9%, and its $1.41 billion of revenue exceeded Wall Street’s consensus estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will see some demand headwinds. Still, the company is tracking well on other measures of financial health.
Adjusted operating margin
ResMed has performed well over the last five years. It demonstrated strong profitability for a healthcare business, with an average adjusted operating margin of 32.7%.
Looking at the trend in its profitability, ResMed’s adjusted operating margin rose by 5.7 percentage points over the last five years, as its revenue growth gave it operating leverage. More recently, the company’s trajectory has remained intact, as its margin has also increased by 3 percentage points on a two-year basis. These gains are a positive sign and show continued momentum.
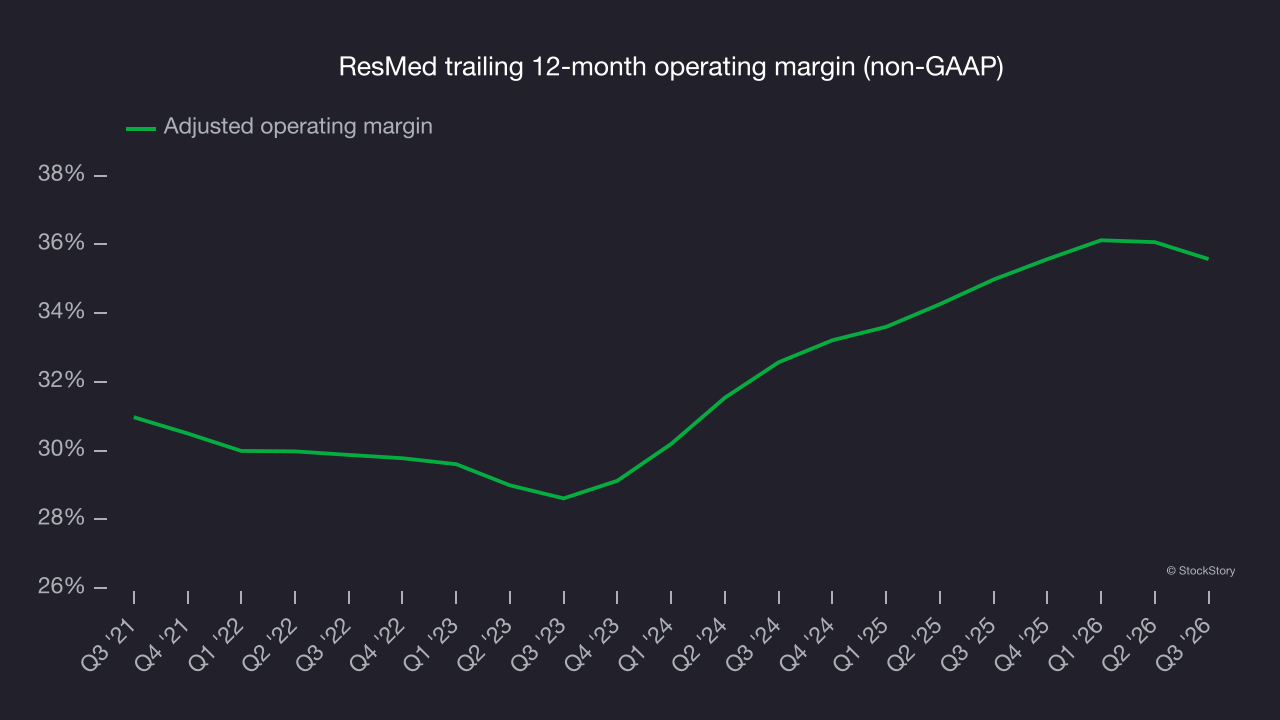
In Q3, ResMed generated an adjusted operating margin of 34.1%, down 2 percentage points year on year. This modest decline indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
ResMed’s EPS grew at a 15.7% compounded annual growth rate over the last five years, higher than its 11.4% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
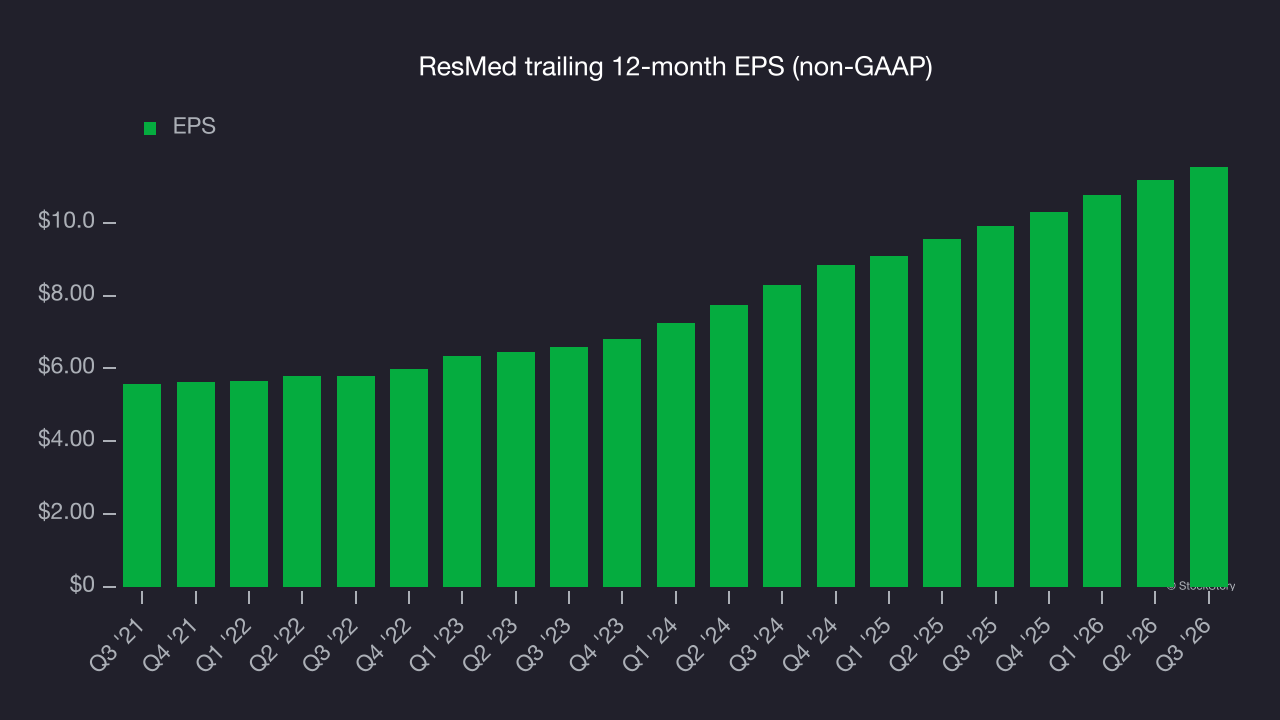
We can take a deeper look into ResMed’s earnings to better understand the drivers of its performance. As we mentioned earlier, ResMed’s adjusted operating margin declined this quarter but expanded by 5.7 percentage points over the last five years. Its share count also shrank by 2.3%, and these factors together are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 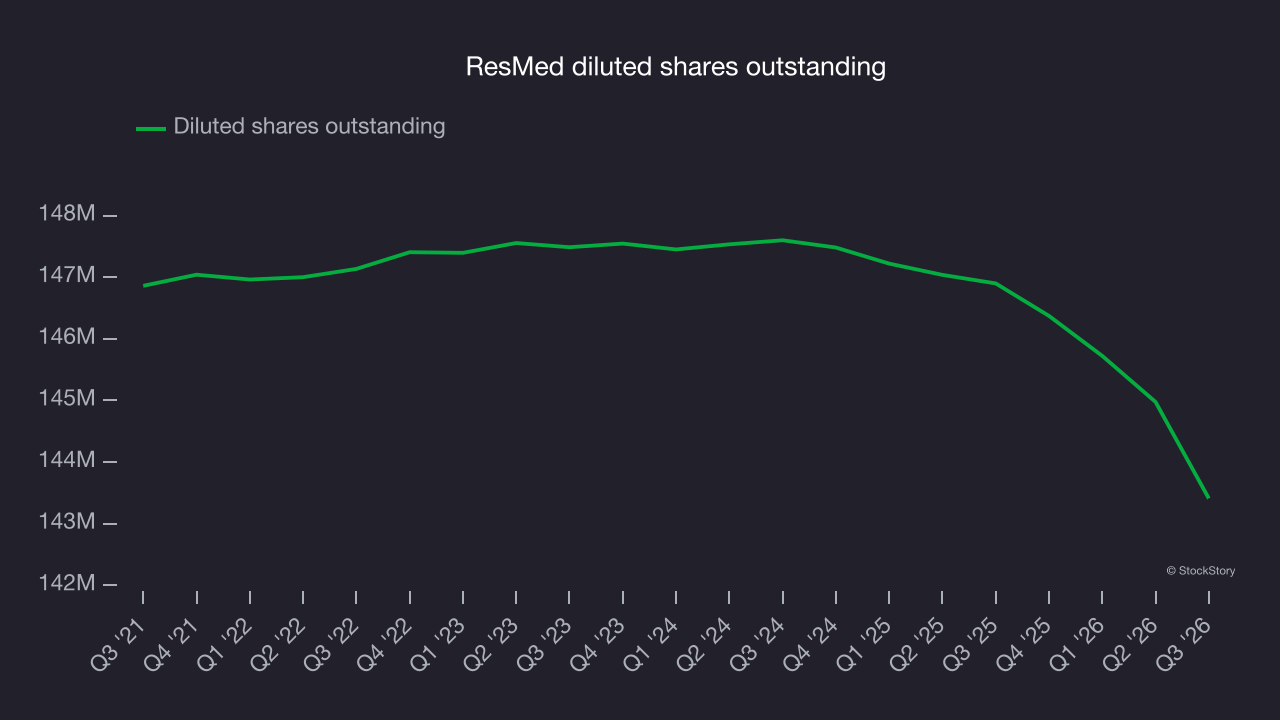
In Q3, ResMed reported adjusted EPS of $2.91, up from $2.55 in the same quarter last year. This result beat analysts’ consensus estimates by 8.9%. Over the next 12 months, Wall Street expects ResMed’s full-year EPS to grow 8.1% from $11.53 to $12.47, according to S&P.
Key takeaways from ResMed’s Q3 results
ResMed delivered a solid quarter, with both EPS and revenue topping analysts’ consensus estimates. Those beats were key positives in the results. Shares rose 3.3% to $260.99 immediately after the release.
ResMed had a solid quarter, but assessing whether the stock is a buy requires a broader view. The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when making that decision. For more on ResMed, read the full research report here (it’s free).