Online freelance marketplace Fiverr (NYSE: FVRR) reported Q3 2026 results exceeding the market’s revenue expectations, but revenue fell by 15.8% year on year to $90.9 million. In addition, next quarter’s revenue guidance ($83 million at the midpoint) was surprisingly strong, coming in 7.4% above analysts’ consensus estimates. Its non-GAAP profit of $0.43 per share was 43.7% above analysts’ consensus estimates.
For more on Fiverr, read our free full research report.
Fiverr (FVRR) Q3 2026 highlights:
- Revenue $90.9 million vs S&P analysts’ consensus estimates of $83.82 million (15.8% year-on-year decline, 8.4% beat)
- Adjusted EPS $0.43 vs S&P analysts’ consensus estimates of $0.30 (43.7% beat)
- Adjusted EBITDA $14.54 million vs analysts’ consensus estimates of $9.74 million (16% margin, 49.3% beat)
- Revenue guidance $83 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $77.3 million
- EBITDA guidance $63 million at the midpoint for the full year, above analysts’ consensus estimates of $57.03 million
- Operating margin -0.7%, in line with the same quarter last year
- Free cash flow margin 10.3%, down from 13.9% in the previous quarter
- Active buyers 2.4 million, down 900,000 year on year
- Market capitalization $290.5 million
“As the landscape shifts from traditional search toward GEO and automated workflows, we are proactively executing on a platform transformation to capture the future of work,” said Micha Kaufman, founder and CEO of Fiverr. “Our upmarket push continues to prove the defensibility and value of complex, high-value work. By upgrading our underlying infrastructure, advancing high-precision outcome matching, and embedding directly into the broader LLM ecosystem, we are rebuilding our traffic vectors while positioning our marketplace as the indispensable, agentic-friendly layer powering the future AI economy.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Fiverr’s revenue grew at a sluggish 4.4% compounded annual growth rate over the last three years, falling short of our standard for the consumer internet sector.
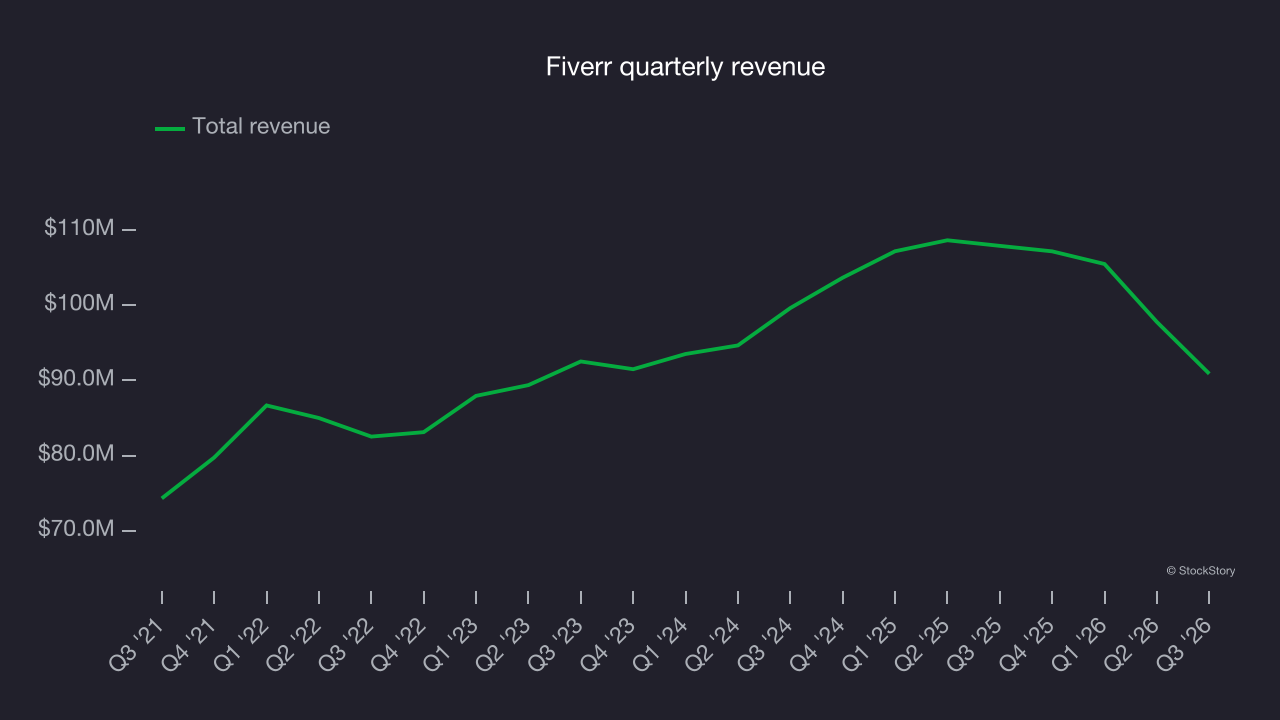
This quarter, Fiverr’s revenue fell by 15.8% year on year to $90.9 million but beat Wall Street’s consensus estimates by 8.4%. Company management is currently guiding for a 22.6% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 22.6% over the next 12 months, according to S&P, a deceleration versus the last three years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Active buyers
Buyer growth
As a gig economy marketplace, Fiverr generates revenue growth by expanding the number of services on its platform (e.g. rides, deliveries and freelance jobs) and raising the commission fee from each service provided.
Fiverr struggled with new customer acquisition over the last two years as its active buyers have declined by 16.2% annually to 2.4 million in the latest quarter. This performance is underwhelming because internet usage is secular, meaning there are typically unaddressed market opportunities. If Fiverr wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 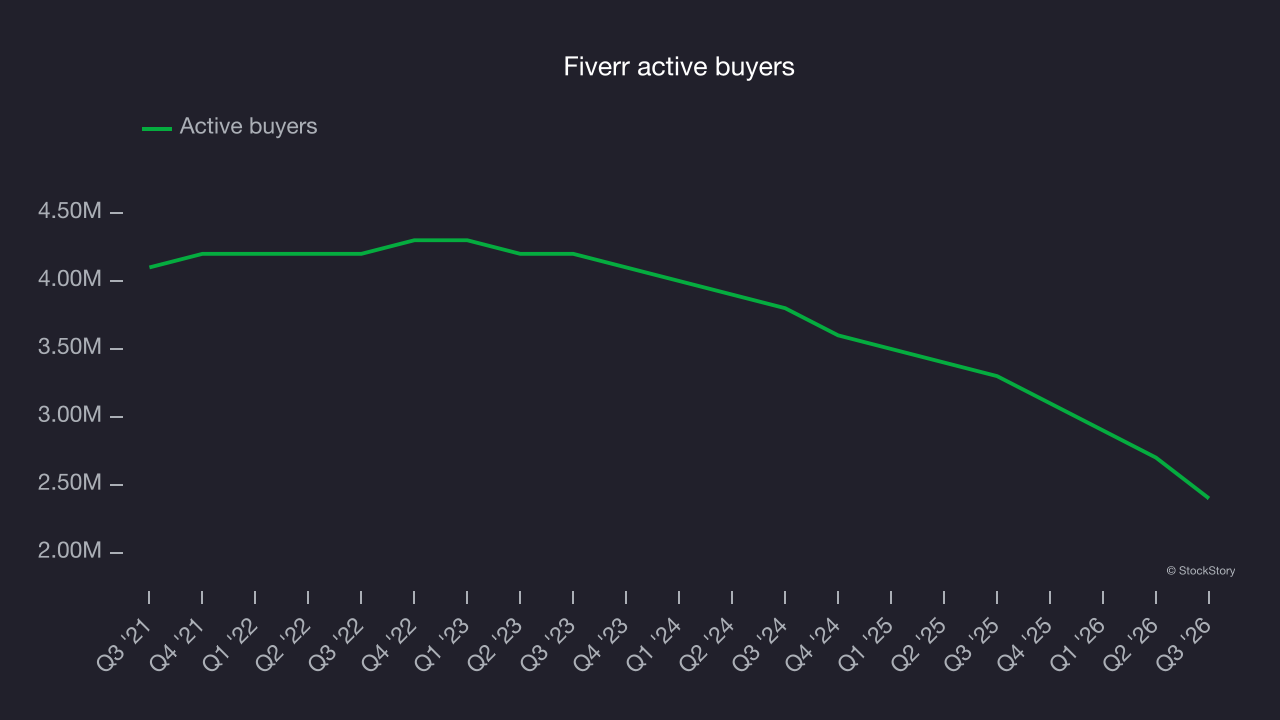
In Q3, Fiverr’s active buyers once again decreased by 900,000, a 27.3% drop since last year. The quarterly print was lower than its two-year result, suggesting its new initiatives aren’t improving buyer trends yet.
Revenue per buyer
Average revenue per buyer (ARPB) is a critical metric to track because it measures how much the company earns in transaction fees from each buyer. This number also provides insight into Fiverr’s take rate, which represents its pricing leverage over the ecosystem, or “cut” from each transaction.
Fiverr’s ARPB growth has been strong over the last two years, averaging 23%. Although its active buyers shrank during this time, the company’s ability to increase monetization demonstrates its platform’s value for existing buyers. 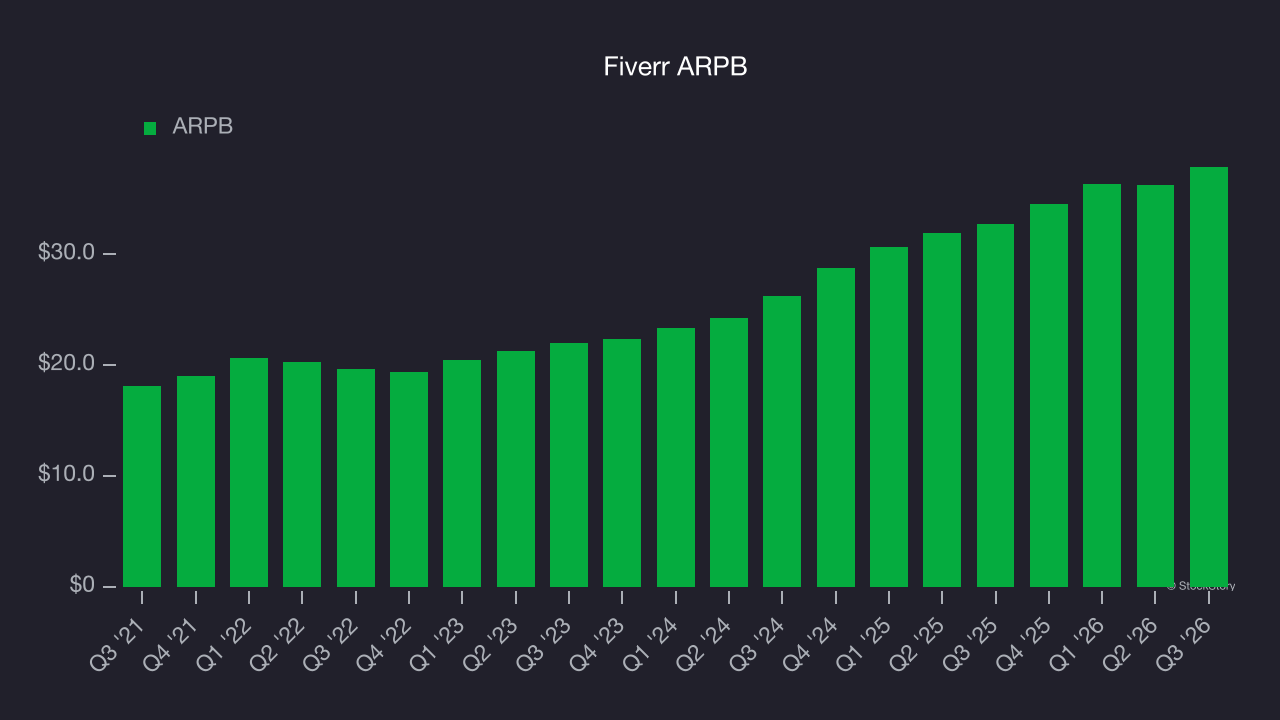
This quarter, Fiverr’s ARPB was $37.87. It grew by 15.8% year on year, faster than its active buyers.
Key takeaways from Fiverr’s Q3 results
Fiverr delivered key positives in Q3, with EBITDA beating Wall Street’s consensus estimates by a wide margin and next-quarter EBITDA guidance also coming in well above analysts’ consensus estimates. The decline in its number of buyers was a downside to the quarter. Shares rose 2% to $8.21 immediately after the results.
Fiverr reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Fiverr, read our full research report here (it’s free).