Over the past six months, Ellington Financial’s stock price fell to $11.78. Shareholders have lost 11.1% of their capital, which is disappointing considering the S&P 500 has climbed by 6.3%. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Ellington Financial, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why do we think Ellington Financial will underperform?
Despite the more favorable entry price, we’re cautious about Ellington Financial. Here are three reasons why EFC doesn’t excite us, plus one stock we’d rather own.
1. EPS barely growing
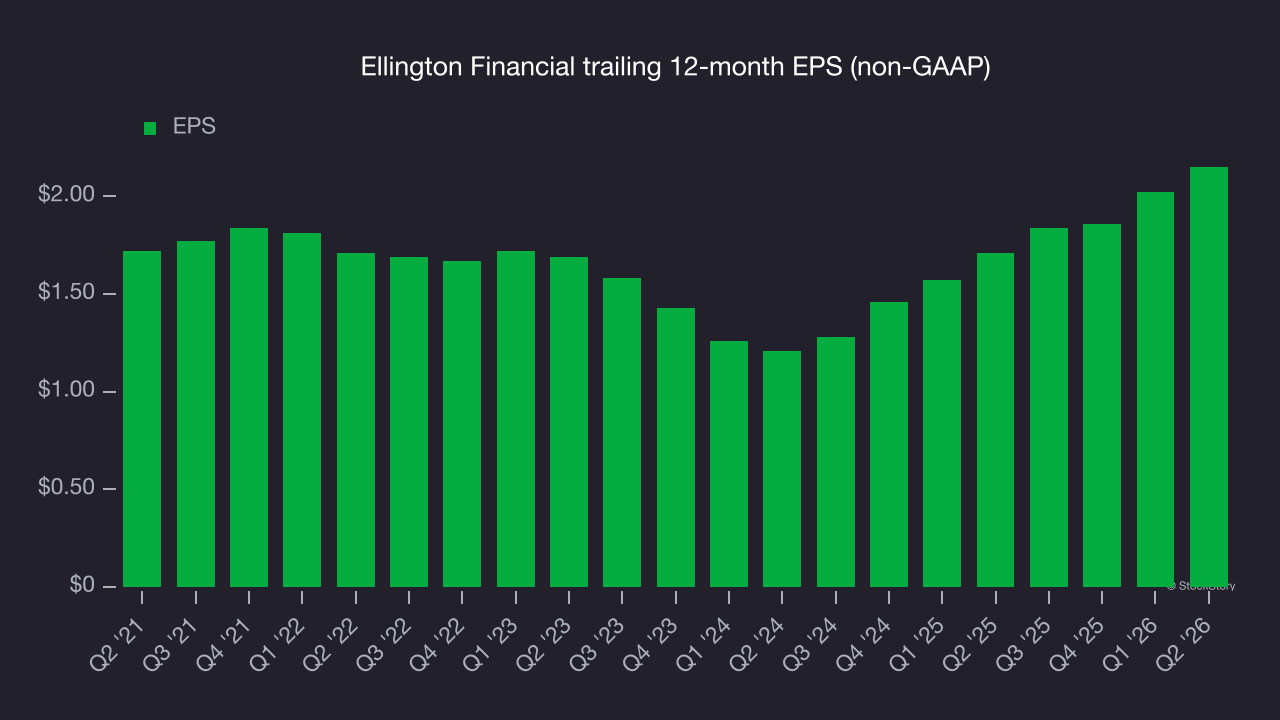
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Ellington Financial’s EPS grew at a weak 4.6% compounded annual growth rate over the last five years, lower than its 17.9% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
2. Declining TBVPS reflects erosion of asset value
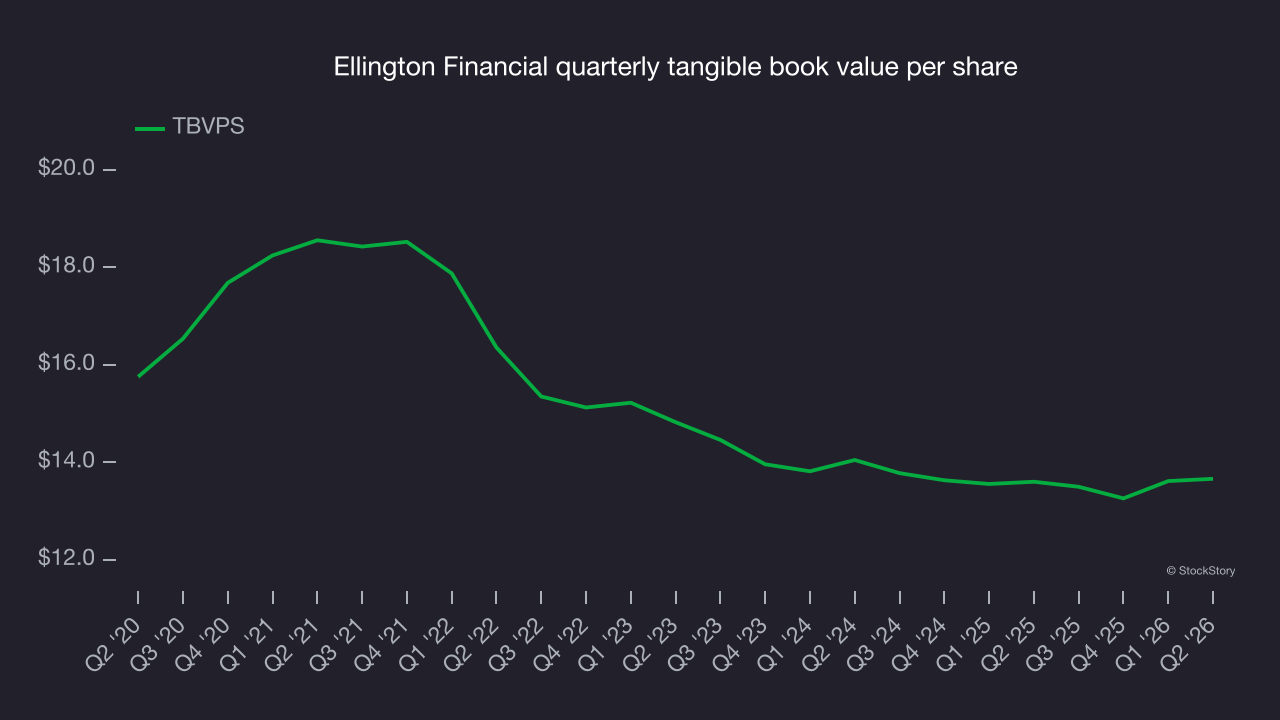
Tangible book value per share (TBVPS) serves as a key indicator of a bank’s financial strength, representing the hard assets available to shareholders after removing intangible assets that could evaporate during financial distress.
Disappointingly for investors, Ellington Financial’s TBVPS declined at a 1.4% annual clip over the last two years.
3. Previous growth initiatives haven’t impressed
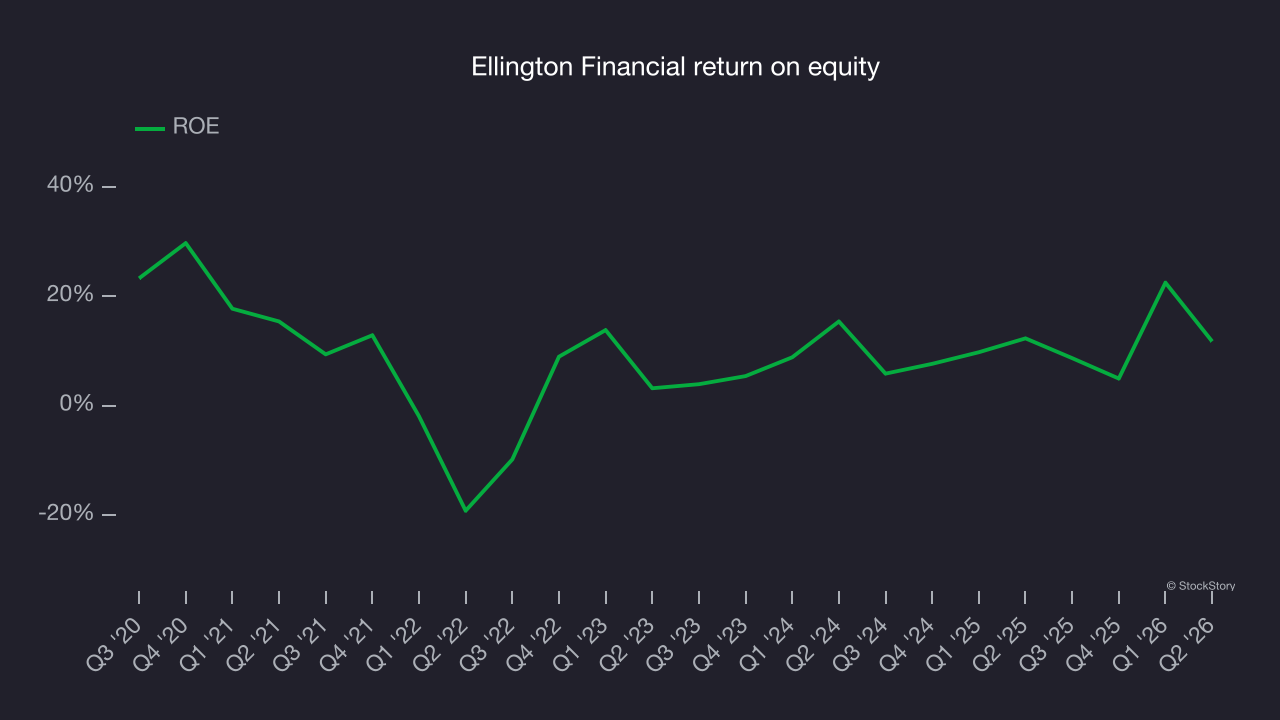
Return on equity, or ROE, tells us how much profit a company generates for each dollar of shareholder equity, a key funding source for banks. Over a long period, banks with high ROE tend to compound shareholder wealth faster through retained earnings, buybacks, and dividends.
Over the last five years, Ellington Financial has averaged an ROE of 6.7%, uninspiring for a company operating in a sector where the average shakes out around 10%.
Final judgment
We cheer for all companies supporting the economy, but in the case of Ellington Financial, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 0.9× forward P/B (or $11.78 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are more exciting stocks to buy at the moment. We’d suggest looking at the most entrenched endpoint security platform on the market.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.