Wrapping up Q2 earnings, we look at the numbers and key takeaways for the payment processing stocks, including EVERTEC (NYSE: EVTC) and its peers.
Payment processors facilitate transactions between merchants, consumers, and financial institutions. Growth comes from e-commerce expansion, declining cash usage globally, and value-added services beyond basic processing. Headwinds include margin pressure from merchant negotiating power, rapid technological change requiring investment, and emerging competition from technology companies entering the payments ecosystem.
The 4 payment processing stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 2%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 9.5% since the latest earnings results.
Best Q2: EVERTEC (NYSE: EVTC)
Operating one of Latin America's leading PIN debit networks called ATH, EVERTEC (NYSE: EVTC) is a payment transaction processor and financial technology provider that enables merchants and financial institutions across Latin America and the Caribbean to accept and process electronic payments.
EVERTEC reported revenues of $274.8 million, up 19.7% year on year. This print exceeded analysts’ expectations by 4.4%. Overall, it was a very strong quarter for the company with an impressive beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
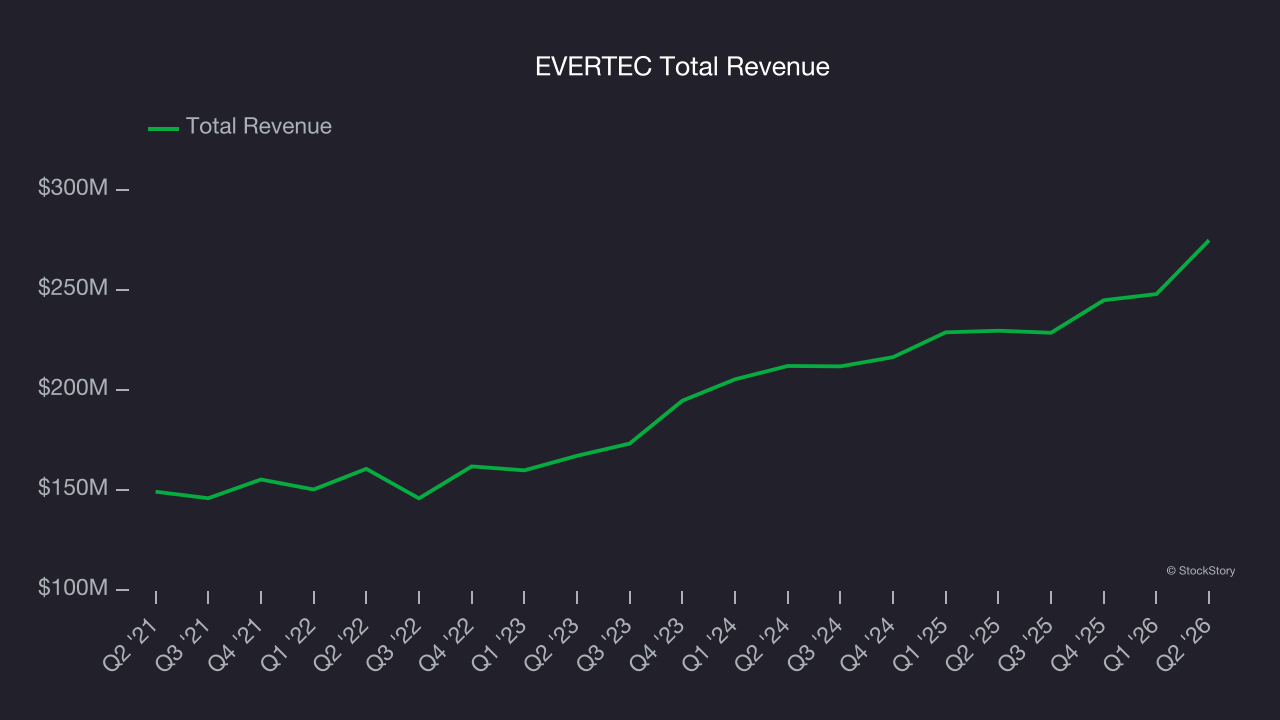
EVERTEC scored the biggest analyst estimate beat and highest full-year guidance raise among its peers. The results were likely priced in, however, and the stock is flat since reporting. It currently trades at $32.27.
We think EVERTEC is a good business, but is it a buy today? Read our full report here, it’s free.
Jack Henry (NASDAQ: JKHY)
Founded in 1976 by two entrepreneurs who saw the need for specialized banking software in the early days of financial computing, Jack Henry & Associates (NASDAQ: JKHY) provides technology solutions that help banks and credit unions innovate, differentiate, and compete while serving the evolving needs of their accountholders.
Jack Henry reported revenues of $633.1 million, up 6.6% year on year, outperforming analysts’ expectations by 1.3%. The business had a strong quarter with a beat of analysts’ EPS estimates and full-year EPS guidance slightly topping analysts’ expectations.
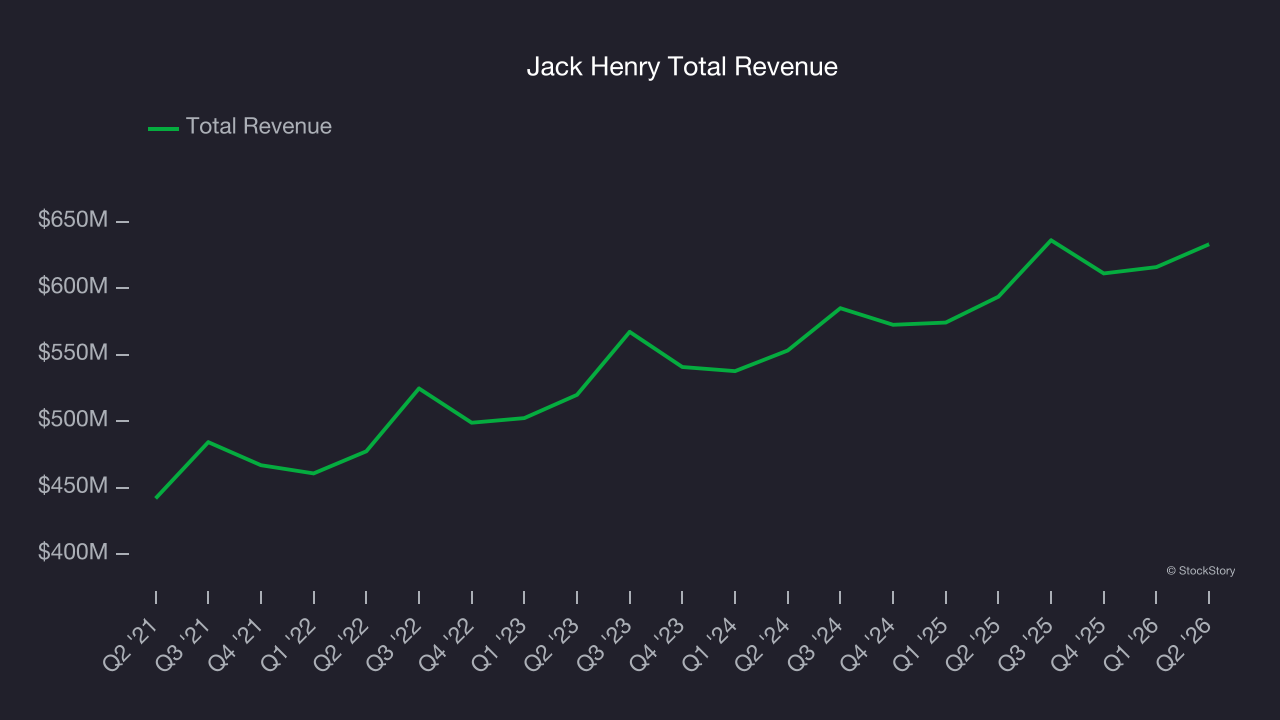
However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $153.44.
Is now the time to buy Jack Henry? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Fiserv (NASDAQ: FISV)
Powering over 1 billion accounts and processing more than 12,000 financial transactions per second globally, Fiserv (NASDAQ: FISV) provides payment processing and financial technology solutions that enable merchants, banks, and credit unions to accept payments and manage financial transactions.
Fiserv reported revenues of $4.96 billion, down 4.5% year on year, falling short of analysts’ expectations by 1.7%. It was a softer quarter as it posted full-year EPS guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
Fiserv delivered the weakest performance against analyst estimates and slowest revenue growth of the whole group. As expected, the stock is down 11.2% since the results and currently trades at $48.03.
Read our full analysis of Fiserv’s results here.
Shift4 (NYSE: FOUR)
Starting as a payment gateway provider in 1999 and now processing over $200 billion in annual payment volume, Shift4 Payments (NYSE: FOUR) provides integrated payment processing solutions and software that help businesses accept and manage transactions across in-store, online, and mobile channels.
Shift4 reported revenues of $1.30 billion, up 34% year on year. This print topped analysts’ expectations by 4%. However, it was a slower quarter as it recorded full-year revenue guidance missing analysts’ expectations significantly and full-year EPS guidance missing analysts’ expectations significantly.
Shift4 pulled off the fastest revenue growth but had the weakest full-year guidance update in the group. The stock is down 26.2% since reporting and currently trades at $39.38.
Read our full, actionable report on Shift4 here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.