Since April 2026, OneWater has been in a holding pattern, posting a small loss of 2.1% while floating around $9.53. The stock also fell short of the S&P 500’s 16.6% gain during that period.
Is there a buying opportunity in OneWater, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think OneWater Will Underperform?
We don’t have much confidence in OneWater. Here are three reasons you should be careful with ONEW, plus one stock we’d rather own.
1. Same-Store Sales Falling Behind Peers
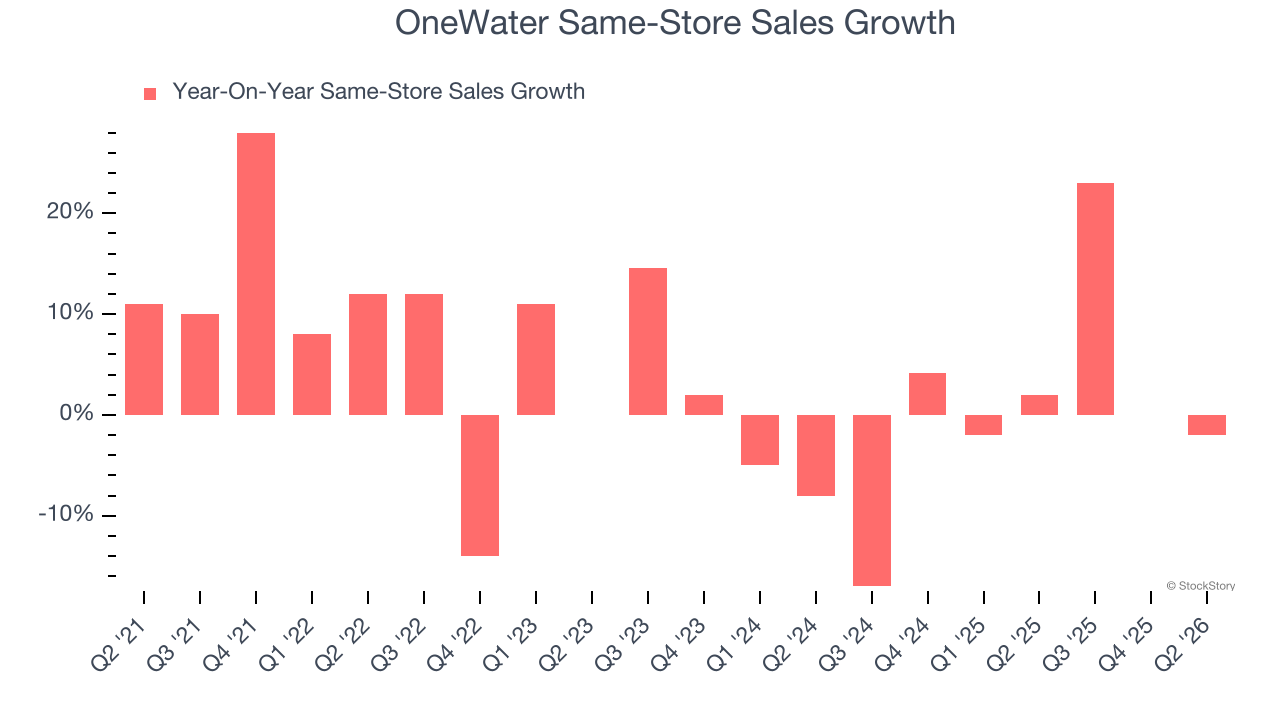
Same-store sales is a key performance indicator used to measure organic growth at brick-and-mortar shops for at least a year.
OneWater’s demand within its existing locations has been relatively stable over the last two years but was below most retailers. On average, the company’s same-store sales have grown by 1.2% per year.
2. EPS Trending Down
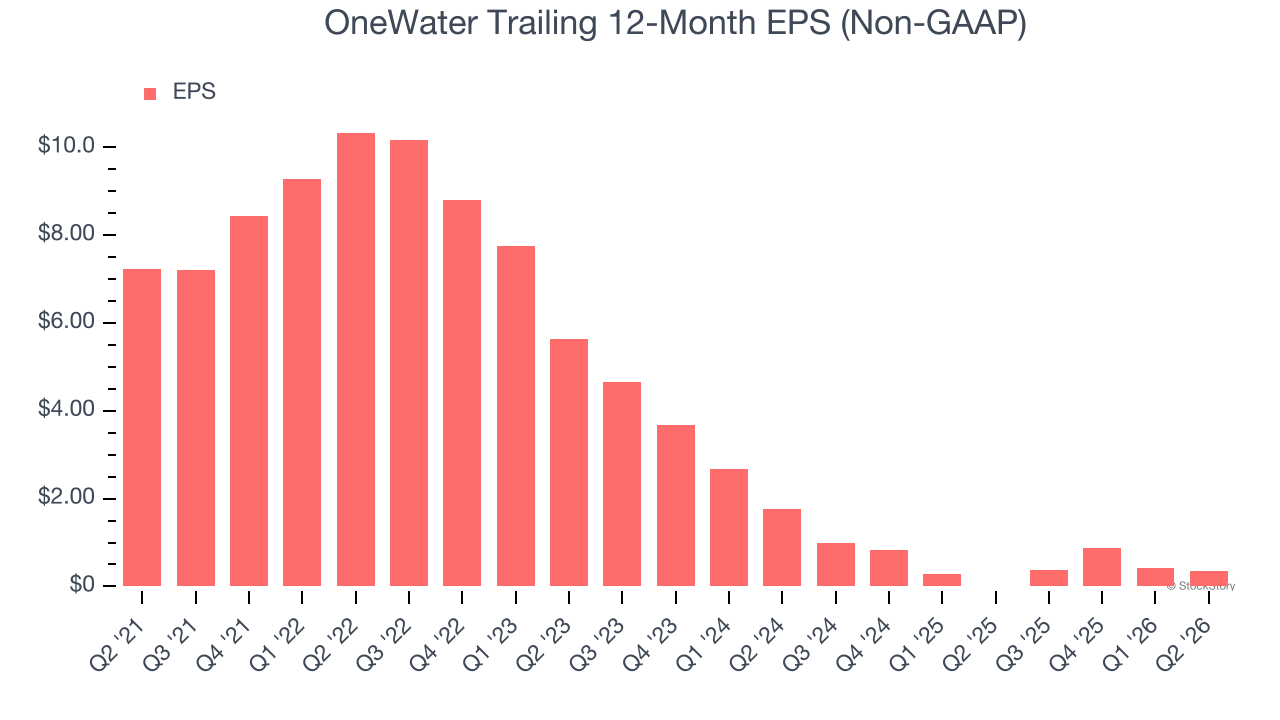
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for OneWater, its EPS declined by 60.4% annually over the last three years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
OneWater’s $468.3 million of debt exceeds the $68.71 million of cash on its balance sheet. Furthermore, its 5× net-debt-to-EBITDA ratio (based on its EBITDA of $75.21 million over the last 12 months) shows the company is overleveraged.
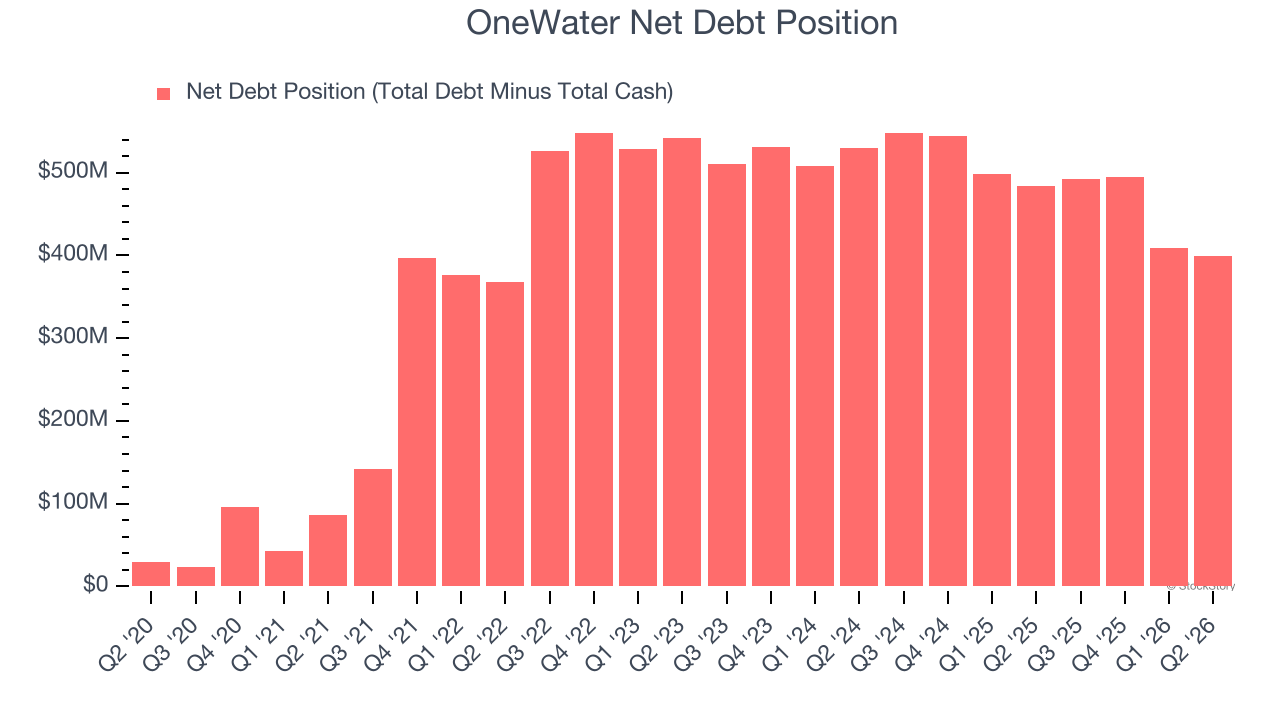
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. OneWater could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope OneWater can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
OneWater falls short of our quality standards. With its shares trailing the market in recent months, the stock trades at 9.1× forward P/E (or $9.53 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are more exciting stocks to buy at the moment. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Would Buy Instead of OneWater
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.